

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Trichloroisocyanuric Acid Market 2026: Why 6.5% CAGR Alone Misses the Real Growth Drivers

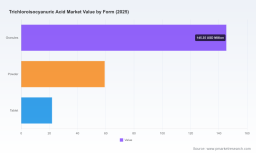
Trichloroisocyanuric Acid Market: Strategic Trends and Commercial Opportunities Through 2032
The trichloroisocyanuric acid market has entered a phase of steady expansion, driven by persistent demand for reliable disinfection solutions and industrial water management. Valued at approximately 226.4 million USD in 2025, the market has grown consistently from 185.5 million USD in 2020, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the market will reach 347.3 million USD by 2032, underscoring a structural shift rather than a temporary cycle. This growth trajectory is supported by expanding applications across sanitation, water treatment, and bleaching sectors, alongside evolving regulatory landscapes that are reshaping supply chains and competitive dynamics.
For decision-makers, the critical question is no longer whether demand will grow, but how to navigate the structural complexities that accompany this expansion. Regional demand concentration, shifting trade policies, and raw material volatility are redefining value creation opportunities. Companies that align their strategies with these macro trends while preparing for regulatory and supply chain disruptions will capture disproportionate market share.
Worldwide Chlorinated Isocyanurates Market
Market Landscape and Core Challenges
The market's growth is not uniform across geographies or application segments. Asia Pacific continues to represent the largest share of revenue, followed by North America and Europe, while Latin America and the Middle East and Africa contribute smaller but growing portions. Form-wise, granular products dominate the market, reflecting preferences for ease of handling and dosing control in commercial and municipal applications. Powder and tablet formats serve more specialized use cases, often tied to specific regulatory approvals or end-user operational requirements. In terms of application, disinfection and sanitation remains the largest segment, absorbing the majority of production output, while bleaching and water treatment applications provide complementary demand streams.
PW Consulting
Despite the positive growth outlook, three structural challenges are reshaping how companies operate and compete.
Raw Material Volatility and Cost Structure Pressures
Production economics for trichloroisocyanuric acid are tightly linked to the pricing of cyanuric acid and chlorine derivatives. In 2024, cyanuric acid prices rose by 9.6 percent and chlorine prices increased by 6.2 percent, driven by supply chain disruptions and environmental regulatory caps in China. These cost pressures compress margins for manufacturers that lack diversified sourcing strategies or integrated production capabilities. The volatility also creates pricing uncertainty for downstream buyers, complicating long-term procurement planning and prompting some end-users to explore alternative disinfectants.
Regulatory Fragmentation and Trade Barrier Risks
Compliance requirements are diverging across major markets, creating a fragmented regulatory environment that penalizes companies without robust certification strategies. The EU Commission Implementing Regulation (EU) 2025/2216 imposed definitive anti-dumping duties on imports of trichloroisocyanuric acid originating in China following a partial interim review. Simultaneously, the US Department of Commerce and International Trade Commission maintained countervailing duty orders on chlorinated isocyanurates from China. These measures, alongside broader export controls, introduce supply chain concentration risks for EU and US markets that rely heavily on Chinese production capacity.
For manufacturers, navigating these duties requires either diversifying sourcing origins, investing in localized production, or securing regulatory approvals that can mitigate trade barriers. The cost of non-compliance or delayed certification is significant, as market access can be restricted or rendered unprofitable by duty structures.
Competitive Concentration and the Need for Differentiation
The market remains highly concentrated, with the top three players capturing approximately 68.5 percent of revenue and the top five accounting for 85.2 percent. This concentration reflects the capital intensity of scale production, the importance of regulatory approvals, and the value of established customer relationships in sanitation and water treatment sectors. While concentration provides stability for leading players, it also raises the barrier for new entrants and intensifies competition among incumbents to defend share through product differentiation, certification leadership, and supply chain reliability.
Companies that compete solely on price face margin erosion, particularly as raw material costs and compliance expenses rise. Sustainable advantage increasingly depends on operational efficiency, regulatory foresight, and the ability to offer tailored formulations or service support that aligns with specific end-user requirements.
Key Drivers Shaping Market Trajectory
Technical Innovation in Product Formulations and Application Efficiency
Innovation in trichloroisocyanuric acid products is shifting from basic commodity production toward performance optimization and application-specific solutions. Manufacturers are investing in granules with controlled dissolution rates, tablets with improved handling safety, and formulations that reduce byproduct formation or improve stability under varying storage conditions. These improvements address end-user concerns around dosing precision, safety, and operational efficiency, particularly in swimming pool sanitation and municipal water treatment where consistency and compliance are critical.
Recent certification milestones illustrate how regulatory compliance and technical validation are becoming competitive differentiators. EPA conditional reregistration issued for trichloroisocyanuric acid (TCCA 90) product registration in April 2025, and EU BPR approvals received by multiple manufacturers including Ercros S.A. and representatives from the IIAHC member network in November 2025, signal that regulatory clearance is increasingly a prerequisite for sustained market access in developed regions. Companies that secure and maintain these approvals can command premium positioning and reduce the risk of market disruption from compliance changes.
Policy and Regulatory Environment as Both Constraint and Catalyst
Regulatory dynamics are reshaping where and how value is created. Anti-dumping duties and countervailing measures on Chinese-origin trichloroisocyanuric acid have redirected trade flows and incentivized non-Chinese producers to expand capacity or strengthen their certifications. For the EU and US markets, this environment creates both risk and opportunity. Import-dependent buyers face supply chain concentration risks, while compliant manufacturers with diversified origins or local production capabilities can capture displaced demand.
At the same time, environmental and safety regulations are pushing manufacturers toward more transparent sourcing, improved handling standards, and documentation that supports downstream compliance. Companies that treat regulatory compliance as a strategic capability rather than a cost center are better positioned to expand into higher-value segments and maintain continuity in the face of policy shifts.
Demand-Side Shifts in Sanitation, Water Treatment, and Industrial Use
Demand growth is being sustained by several structural factors. Public and commercial sanitation requirements remain elevated as facilities prioritize reliable disinfection protocols. Swimming pool and recreational facility operators continue to rely on trichloroisocyanuric acid for its efficacy and ease of use, particularly in granular and tablet formats that support controlled application. Water treatment applications, both municipal and industrial, are expanding as regions invest in infrastructure upgrades and stricter water quality standards. Bleaching applications provide additional demand, especially in textile and paper sectors where chlorinated isocyanurates offer effective whitening and disinfection properties.
The demand pattern is also shifting toward buyers who value supply reliability and certification assurance over lowest-cost procurement. This is particularly evident in regulated markets where compliance documentation and product consistency are non-negotiable. Manufacturers that can demonstrate stable supply, validated product quality, and responsive technical support are gaining preference in these segments.
Supply Chain Reconfiguration and Capacity Expansion
Capacity expansion is a central theme in the market's evolution. Production facility expansions of approximately 20,000 metric tons annually have been reported in 2024 and 2025, aimed at meeting export demand and strengthening supply resilience. These expansions reflect the expectation of continued volume growth and the strategic importance of securing sufficient capacity to serve key export markets.
At the same time, supply chain diversification is becoming a priority for buyers and manufacturers alike. The combination of raw material price volatility, trade duties, and regulatory approvals is pushing companies to evaluate multi-sourcing strategies, regional production footprints, and inventory management practices that can buffer against disruptions. For exporters, this means that capacity alone is insufficient; competitiveness increasingly depends on the ability to deliver compliant products with predictable lead times and transparent documentation.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of established Chinese manufacturers, European branded producers, and specialized Indian and Japanese players. Hebei-based manufacturers such as Hebei Kaihong Chemical Co., Ltd. and Hebei Xingfei Chemical Co., Ltd. maintain strong positions in granular, tablet, and powder formats for pool sanitation, water treatment, and disinfection. Heze Huayi Chemical Co., Ltd. and Zhucheng Taisheng Chemical Co., Ltd. extend the Chinese manufacturing base with additional capacity focused on industrial and water treatment applications, while Shandong Lantian Disinfection Technology Co., Ltd. and Puyang Cleanway Chemicals, Ltd. serve as active suppliers in powder and granular segments. Zhengzhou Mahaco Industrial Co., Ltd. and Taian Huatian Chemical Co., Ltd. round out the Chinese export-oriented landscape, emphasizing water treatment and pool use cases.
In Europe, Ercros S.A. stands out with its Delsa and Bluei branded products targeting swimming pools and recreational facilities, combining regional brand recognition with regulatory alignment. In India, Bodal Chemicals Ltd. positions itself as the country's first and only manufacturer of TCCA 90 for water purification and disinfection, leveraging local production to serve domestic demand and potentially regional exports. In Japan, Nippon Soda Co., Ltd. and Sikoku Chemicals Corporation focus on industrial water treatment and disinfection applications, benefiting from technical credibility and proximity to regulated end markets.
Strategic Positioning and Differentiation
Leading players are differentiating along several dimensions. Scale and capacity expansion allow exporters to meet large-volume demand and reduce per-unit costs, but this advantage is only sustainable when paired with reliable compliance and logistics. Regulatory certification leadership provides access to premium segments and reduces the risk of trade barriers or market access restrictions. Brand building, particularly in European and recreational facility markets, supports customer loyalty and price resilience. Product form specialization, such as controlled-release granules or safety-oriented tablets, addresses specific application needs and can justify differentiated pricing.
Companies that combine multiple advantages—such as capacity, certification, and application-focused product design—are best positioned to defend share and expand into higher-value segments. Those that rely on a single strength, such as low-cost production without compliance depth, face greater exposure to margin pressure and regulatory risk.
Market Evolution Trends
The market is likely to see consolidation among smaller producers who struggle with certification costs, raw material volatility, and trade barriers, while larger and well-capitalized players expand capacity and strengthen their compliance portfolios. At the same time, there is room for niche differentiation, particularly in specialized applications or regions where local production and regulatory alignment create barriers for generic commodity suppliers. New entrants will find it challenging to compete on scale alone; success will depend on securing regulatory approvals early, building reliable supply chains, and targeting segments where product performance and documentation matter more than price.
Export-oriented manufacturers will increasingly need to navigate a dual reality: strong demand growth in many regions, but also a complex web of duties, approvals, and sourcing expectations. Those that can balance capacity expansion with regulatory readiness and supply chain diversification will be most resilient.
Future Trends and Commercial Opportunities (2026–2032)
Continued Capacity Expansion with a Compliance-First Posture
Over the next three to five years, capacity expansion is expected to continue, particularly in regions that can support export growth while managing regulatory requirements. The 6.5 percent CAGR projected through 2032 implies that demand will grow by more than 100 million USD in cumulative value over the forecast period. Suppliers that add capacity with integrated compliance strategies—securing relevant certifications, aligning with destination-market regulations, and ensuring documentation readiness—will be able to capture displaced demand from trade barriers and benefit from the overall market uptrend.
For buyers, this trend creates an opportunity to diversify supply sources and reduce dependence on any single origin. Procurement strategies that combine multiple certified suppliers, regional inventory buffers, and long-term agreements with compliance assurances will be more resilient to duty changes and raw material shocks.
Premiumization and Application-Specific Solutions
As the market matures, differentiation through product performance and application support will become more valuable. Granular formats are likely to maintain dominance due to ease of use, but there is room for innovation in dissolution profiles, packaging safety, and formulation stability that reduce handling risks and improve operational outcomes. Tablet and powder segments may see targeted growth in specialized disinfection and industrial use cases where precise dosing or specific handling requirements justify a premium.
Manufacturers that invest in technical service, application guidance, and consistent quality documentation can shift the competitive basis from price to value. This is especially relevant for water treatment and municipal sanitation buyers who prioritize reliability and compliance over marginal cost savings. The opportunity lies in building repeatable, application-focused offerings that reduce total cost of ownership for end-users, even if unit prices are higher.
Cyanuric Acid Market
Supply Chain Regionalization and Risk Mitigation as a Competitive Edge
Regulatory duties and raw material volatility are accelerating interest in regionalized supply chains. EU and US buyers are increasingly aware of concentration risks from reliance on Chinese-origin imports, and the imposition of definitive anti-dumping duties and continued countervailing orders reinforces the incentive to diversify. This does not necessarily mean a full exit from Chinese sourcing, but it does favor multi-region strategies that balance cost with compliance and continuity.
Commercial opportunities will emerge for suppliers that can offer transparent origin documentation, certified product quality, and flexible logistics that adapt to changing duty structures. Manufacturers with production footprints or partnerships in multiple regions can position themselves as lower-risk options for procurement teams seeking to stabilize supply. At the same time, buyers that invest early in qualifying alternative sources will be better prepared to switch or blend suppliers without disruption when trade policies shift.
Risks and Uncertainties to Monitor
Several uncertainties could alter the trajectory. Raw material price spikes may recur if environmental caps tighten or supply chain disruptions emerge, compressing margins and destabilizing pricing. Regulatory reviews could expand or intensify, affecting not only Chinese-origin products but also the broader competitive balance if duties are extended or if certification requirements become more stringent. Demand growth could slow in specific segments if alternative disinfectants gain traction or if economic constraints reduce discretionary spending on pool and recreational facility maintenance. Finally, capacity expansions could outpace demand in certain sub-segments, leading to localized oversupply and price competition.
Monitoring these risks requires continuous attention to raw material markets, regulatory announcements, and end-user adoption trends. Companies that build scenario planning into their procurement, production, and sales strategies will be better equipped to respond quickly when conditions change.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
Prioritize certification and regulatory readiness as core capabilities rather than administrative tasks. Securing and maintaining EPA, EU BPR, and other relevant approvals is increasingly a determinant of market access and customer trust. Pair capacity expansion with compliance depth so that new volume can be commercially absorbed in regulated markets. Diversify raw material sourcing where feasible to reduce exposure to price spikes, and consider integrated or strategic partnerships that improve cost predictability.
Differentiate through application-focused product design and technical support. Controlled-release granules, safer tablet formats, and consistent quality documentation can justify premium positioning and reduce the risk of pure price competition. Build customer-facing capabilities that help end-users meet their own compliance and operational requirements, turning product sales into longer-term service relationships.
For Investors and Capital Allocators
Focus on companies that combine scale with regulatory resilience and supply chain flexibility. Capacity expansion alone is not a sufficient investment thesis; the more durable opportunities lie in producers that can navigate trade duties, maintain certifications, and serve multiple regions or applications without over-concentration. Evaluate exposure to raw material volatility and the company's mitigation strategies, including sourcing diversity, pricing mechanisms, and inventory management.
Watch for consolidation opportunities as smaller producers face certification costs and compliance complexity. Well-capitalized players with established approvals and diversified customer bases are likely to be both defensive and acquisitive, creating potential for value creation through share gains and selective integration. At the same time, assess end-market demand durability in sanitation, water treatment, and industrial segments to ensure that growth assumptions are grounded in structural trends rather than short-term cycles.
For Procurement and Supply Chain Leaders
Treat supply resilience as a strategic priority, not just a cost optimization exercise. Diversify approved suppliers across regions and product forms to mitigate concentration risk from duties and raw material volatility. Establish qualification processes that prioritize certification status, documentation reliability, and consistent product quality alongside price. Consider long-term agreements with suppliers that can demonstrate compliance readiness and flexible logistics, and maintain contingency options for rapid supplier transitions if trade policies change.
Engage early with suppliers on application requirements and compliance expectations. Aligning on product specifications, handling safety, and documentation needs reduces the risk of disruptions and improves total cost outcomes over time. Where possible, build inventory buffers for critical applications and monitor raw material price trends to time procurement decisions more effectively.
Navigating the Next Phase
The trichloroisocyanuric acid market is positioned for sustained growth, but the value creation opportunities are increasingly tied to regulatory agility, supply chain resilience, and application-focused differentiation. The combination of a 6.5 percent CAGR through 2032, evolving trade duties, and ongoing capacity expansion creates a complex but navigable environment for companies that plan strategically.
Decision-makers who understand where concentration risks lie, which certifications matter most in their target markets, and how raw material dynamics affect cost structures will be better prepared to capture growth while managing downside exposure. Detailed segmentation data, company-level profiling, and region-specific regulatory tracking can sharpen these decisions further, enabling more precise planning for capacity, sourcing, and market entry.
For a deeper dive into the market's segmentation dynamics, competitive benchmarking, and region-specific regulatory outlook, the full market research report provides comprehensive data and tailored scenarios to support strategic planning across manufacturing, investment, and procurement functions.
For detailed analysis of this topic, please visit the official page: Trichloroisocyanuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com