

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
DIP Switches Market 2026: Why Asia Pacific's 175M$ Lead & 3.6% CAGR Redefine Strategy

The DIP Switches Market: Strategic Shifts and Commercial Opportunities in a Mature Landscape
Market Overview: A Resilient but Evolving Landscape
The DIP switches market has demonstrated steady, disciplined growth over the past half-decade, reflecting its entrenched role as a reliable interface component across a broad spectrum of electronic systems. From 2020 through 2025, global revenue expanded at a measured pace, moving from approximately 350 million USD to 425 million USD. This trajectory underscores a market that is neither in rapid expansion nor in structural decline, but rather in a phase of incremental maturation where value creation depends on differentiation, supply chain resilience, and targeted application penetration. Looking ahead, the forecast period through 2032 points to continued growth, with a compound annual growth rate of 3.6 percent, suggesting that demand will remain anchored by legacy industrial, consumer, and automotive applications while gradually integrating into newer electronics architectures.
Several structural realities shape this outlook. First, the market operates with notably high concentration among established manufacturers, which creates both barriers to entry and opportunities for incumbents to leverage scale, certification portfolios, and long-standing customer relationships. Second, the product mix is distributed across multiple mechanical configurations, each serving distinct actuation, packaging, and environmental requirements. This diversity means that no single form factor dominates the entire value chain; rather, success depends on matching switch characteristics to application constraints. Third, regional demand is spread across mature and emerging markets, with Asia Pacific representing the largest share of revenue, followed by Europe and North America. This geographic dispersion reflects both manufacturing footprints and end-market consumption patterns, but it also introduces complexity in navigating trade policies, logistics, and localization requirements.
Against this backdrop, the DIP switches market faces a set of interconnected challenges that will define competitive positioning over the next several years. These are not existential threats, but they are meaningful inflection points that require deliberate strategic responses.
RF Switches Market
Key Challenges and Inflection Points
The first challenge is the tension between mature demand profiles and the need for continuous product evolution. DIP switches remain valuable for configuration, calibration, and manual control functions, but many end markets are simultaneously adopting digital alternatives, firmware-based settings, and software-configurable interfaces. This does not eliminate demand for electromechanical switches, but it does shift the battleground toward applications where tactile feedback, field serviceability, safety certification, or fail-safe behavior justify a physical switching solution. Manufacturers that treat DIP switches as commodity components risk margin compression, while those that frame them as reliability-critical interface elements can defend pricing and deepen customer lock-in.
A second challenge arises from cost and sourcing pressures that ripple through the electromechanical supply chain. Input cost inflation, extended lead times for critical components, and an increasingly layered tariff environment have altered the economics of procurement and production planning. For DIP switches, which depend on materials such as copper-based contacts, plastics, and precision machining, these dynamics affect both manufacturing cost and inventory strategy. Buyers are increasingly weighing total cost of ownership against unit price, and suppliers are being asked to demonstrate consistency, certification readiness, and contingency capabilities rather than simply offering the lowest quotation.
A third challenge is the broadening expectation that even small components meet rigorous quality, environmental, and traceability standards. In automotive, medical, industrial control, and defense-related applications, switch selections are often gated by qualification requirements and long validation cycles. The practical implication is that time-to-value becomes as important as technical performance. Suppliers that can navigate certification frameworks, provide documented reliability data, and support customer engineering processes gain a structural advantage. Those that cannot may find themselves restricted to less demanding segments where competition is more price-driven and switching costs are lower.
Core Drivers Reshaping the DIP Switches Market
Market evolution in this segment is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers interact in ways that create both risk and opportunity, and they help explain why the market continues to expand even as it matures.
Technological Innovation and Product Differentiation
Innovation in DIP switches is less about radical redesign and more about refining mechanical reliability, packaging efficiency, and application-specific performance. Manufacturers are expanding product families with variations in actuation style, position count, terminal materials, and environmental protection. This matters because the value of a DIP switch often lies in how well it fits a specific use case: a device that must withstand vibration, temperature extremes, or extended cycling will require different engineering than one intended for benign consumer environments. The result is a market where portfolio breadth and specification clarity increasingly determine win rates.
Recent product activity illustrates this trajectory. In mid-2026, one manufacturer expanded its DIP switch range by adding over 100 new items to distributors, with a noticeable emphasis on industrial control and automation applications. This kind of expansion signals a strategic focus on coverage, availability, and segment relevance rather than a single breakthrough product. It also reflects the broader reality that distributors and design engineers often value accessible documentation, standardized packaging, and well-defined specifications as much as the underlying mechanical performance. In the same period, updated datasheets for established through-hole DIP switch series were released, reinforcing the importance of maintaining current technical information for recurring designs.
For businesses, the practical takeaway is that technical differentiation in DIP switches is often achieved through incremental enhancements that accumulate into meaningful competitive separation. Low-profile designs, dustproof or waterproof options, stackable configurations, and three-stage or normally open/closed variants all address real engineering constraints. Suppliers that align these features with clearly defined application narratives can command more stable demand than those competing primarily on generic part numbers.
Policy, Regulation, and Trade Policy Dynamics
The regulatory and trade environment has become a more prominent factor in component sourcing and production planning. Tariff adjustments on certain imported goods, including electronics-related categories, have raised input costs across multiple manufacturing sectors. Alongside this, duties on semi-finished copper products have added another layer of cost pressure for suppliers dependent on metal-intensive components. These changes do not fundamentally alter the demand for DIP switches, but they do influence where and how components are sourced, stocked, and priced.
Rotary DIP Switches Market
Trade policy uncertainty also affects the calculus of regional sourcing. Companies that rely heavily on single-country procurement are increasingly examining alternative manufacturing locations, buffer inventory strategies, and qualification of secondary sources. For DIP switch suppliers, this environment creates an opening for manufacturers that can demonstrate geographic flexibility, transparent cost structures, and consistent compliance support. Buyers are not simply looking for the cheapest part; they are looking for a sourcing partner that reduces exposure to disruption and helps them navigate an unpredictable trade landscape.
In practical terms, the policy environment is pushing both suppliers and buyers toward more disciplined supply chain design. That means stronger emphasis on documentation, regional stock strategies, and multi-source qualification. It also means that regulatory and tariff-aware sourcing decisions are becoming part of the commercial evaluation, not just an afterthought.
Demand-Side Shifts in Consumer, Industrial, and Automotive Segments
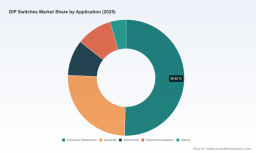
Demand for DIP switches is shaped by a mix of enduring and evolving application needs. Consumer electronics continue to represent the largest application share, reflecting the broad use of switches in devices that still benefit from physical configuration controls. Industrial applications form a substantial second pillar, where switches are used in control panels, equipment calibration, and field-serviceable settings. Automotive and telecommunications segments contribute meaningful demand as well, though they often impose more stringent quality and reliability expectations.
PW Consulting Health Care Research Center
What makes this demand environment strategically interesting is that the switching behavior is not uniform across segments. In consumer products, cost sensitivity and design compactness can dominate. In industrial and automotive settings, durability, vibration resistance, temperature tolerance, and certification credentials often carry more weight than absolute unit cost. This segmentation creates an opportunity for suppliers to build reputation-based positions in higher-value niches, even if they do not lead in total volume. It also explains why some manufacturers emphasize automotive-quality certifications, environmental management standards, and extended-cycle durability in their product narratives.
At the same time, demand-side behavior is being influenced by equipment manufacturers’ need to reduce lifecycle risk. In many cases, a DIP switch is selected not because it is the most advanced interface option, but because it offers a straightforward, serviceable, and verifiable method of configuration. This endurance is a competitive strength, but only if suppliers can support it with consistent quality and dependable availability. The most successful players are those that treat demand as application-specific rather than generic, tailoring their messaging and product breadth accordingly.
Supply Chain and Cost Structure Pressures
Cost structure changes are reshaping how DIP switches are produced, stored, and delivered. Raw material price increases have affected manufacturing inputs, with average increases observed in 2025 and continued pressure projected into 2026. These costs intersect with longer lead times for critical components, which have been reported in manufacturer supply chains with extensions averaging several weeks. The combined effect is a stronger incentive for planning discipline: suppliers and buyers alike are managing inventories with more caution, and the cost of disruption is being priced into sourcing decisions.
For DIP switch manufacturers, the supply chain environment rewards scalability, packaging efficiency, and reliability in delivery. Tape-and-reel formats, stackable designs, and standardized through-hole packaging can reduce handling complexity and improve integration into automated assembly processes. For buyers, the emphasis shifts toward suppliers that can maintain consistent lead times, communicate availability clearly, and reduce the risk of line-down scenarios. In this context, operational reliability becomes a commercial differentiator.
The broader implication is that cost pressure does not simply compress margins; it also accelerates consolidation around suppliers that can absorb variability without sacrificing service levels. Companies that can demonstrate stable input planning, efficient logistics, and transparent communication are better positioned to retain high-value customers, especially in segments where downtime or re-qualification costs are significant.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The DIP switches market features a mix of long-established global suppliers, regional specialists, and volume-oriented manufacturers. Competitive positioning often depends on the intersection of product breadth, certification capability, distribution reach, and segment focus. Rather than a single dominant business model, the market supports multiple viable strategies, each with its own risks and value drivers.
How Leading Players Differentiate
One common differentiation path is application-led specialization. Some manufacturers emphasize precision rotary designs for demanding environments such as medical devices, military electronics, and industrial control, where reliability and consistent performance are paramount. Others build their identity around broad mechanical variety, offering multiple actuation styles, mounting configurations, and terminal options to serve a wide range of electronics applications. This breadth can be attractive to design engineers who prefer to source from a supplier that can cover many requirements without fragmenting the bill of materials across too many vendors.
A second differentiation path centers on certification and qualification portfolios. In segments where customers must satisfy automotive, environmental, or quality management standards, suppliers that hold relevant certifications and can document process control gain a meaningful advantage. This is particularly important in markets where validation cycles are long and switching costs are high. Manufacturers that highlight vibration resistance, temperature tolerance, and extended cycle life are effectively positioning their products for environments where failure is costly.
A third path is distribution-led availability and catalog expansion. Some manufacturers have focused on increasing the number of items accessible through distributors, adding new series with detailed specifications, and improving the ease with which design engineers can evaluate and procure parts. This approach does not always depend on producing the most technically advanced switch; instead, it aims to reduce friction in sourcing and shorten the path from specification to purchase. In mature component markets, availability and information clarity can be as influential as raw performance.
A fourth path is price and volume orientation, often associated with through-hole standard products and commodity-focused production. This model can win in cost-sensitive applications, but it typically operates in a more competitive and less differentiated space. The strategic challenge for volume-oriented players is to maintain efficiency while avoiding races to the bottom that erode profitability. For buyers, the challenge is to ensure that lower unit prices do not introduce unacceptable risk in quality, delivery, or lifecycle support.
Market Structure and Evolution Trends
The competitive landscape is evolving along several axes. First, consolidation pressure remains relevant in mature component markets, where larger players can leverage scale, certification infrastructure, and global distribution. This does not mean that smaller or regional manufacturers are disadvantaged in every scenario; many compete effectively by focusing on specific applications, serving regional demand with shorter response times, or providing specialized configurations that larger portfolios may not prioritize.
Second, new-entry dynamics are shaped less by brand recognition than by supply chain access and qualification readiness. A manufacturer may have a technically capable product, but if it cannot meet the documentation, certification, or delivery expectations of target customers, its growth will be limited. This practical reality favors suppliers that invest early in the operational capabilities that high-value segments require.
Third, the market is likely to see continued segmentation rather than homogenization. Some product lines will compete as reliable standards in high-volume consumer and industrial applications, while others will be positioned as qualified solutions for automotive, medical, or defense-adjacent use cases. The most resilient companies are those that understand which segment they are serving and do not blur the distinction between commodity competitiveness and reliability-led differentiation.
For businesses evaluating the competitive field, a useful lens is whether a supplier competes on convenience, certification, application fit, or cost leadership. Each model can succeed, but the strategic requirements differ. Convenience-led players must excel in catalog completeness, distributor relationships, and specification clarity. Certification-led players must manage process control and qualification overhead efficiently. Application-fit players must maintain engineering relevance and segment-specific credibility. Cost leaders must protect margins through scale, process efficiency, and disciplined sourcing.
Future Outlook: Trends Shaping the Next Three to Five Years
Looking forward, the DIP switches market is likely to be shaped by a small number of reinforcing trends. These trends do not point to dramatic disruption, but they do indicate where value will migrate and where strategic attention will be rewarded.
Trend 1: Reliability as a Value Driver, Not Just a Feature
As electronics systems become more integrated into critical workflows, the perceived value of dependable manual interface components is likely to increase in select segments. DIP switches will not replace digital configuration everywhere, but they remain useful where physical feedback, field serviceability, and independent operation matter. Over the next few years, suppliers that can demonstrate consistent reliability, document performance across environmental conditions, and reduce the risk of failure in demanding applications will be better positioned to retain and expand share in higher-value niches.
The commercial opportunity here is not simply to sell switches, but to position them as risk-reduction elements in larger system designs. That can support more stable demand, stronger customer relationships, and greater tolerance for justified pricing. The risk is that suppliers overpromise on reliability without backing it with disciplined manufacturing and documentation, which can quickly erode trust in qualification-heavy segments.
Trend 2: Supply Chain Resilience Becomes a Core Purchasing Criterion
Tariff volatility, input cost variation, and lead time extensions are likely to keep supply chain resilience high on the procurement agenda. Buyers will continue to evaluate suppliers not only on unit price, but also on availability, geographic sourcing flexibility, and the ability to maintain continuity during disruptions. This favors manufacturers that can offer predictable delivery, clear communication, and alternative sourcing options.
For the market overall, this trend may encourage more deliberate inventory planning and broader qualification of secondary sources. It may also increase the importance of distributor networks as buffer and accessibility points. Companies that treat supply chain dependability as a strategic capability rather than an operational detail will have an advantage in retaining customers who cannot afford disruption.
Trend 3: Application-Focused Portfolio Strategy Will Outperform Generic Breadth
As the market matures, the most effective portfolio strategies are likely to be those that align product breadth with application needs rather than simply expanding part numbers. This means building credible positions in segments such as industrial control, automotive-adjacent electronics, medical devices, and consumer products, each with its own specification priorities and qualification expectations. Suppliers that understand these differences can tailor their messaging, packaging, and support to the customers they actually want to serve.
The opportunity lies in using application focus to reduce competitive noise. When a supplier is known for serving a specific segment credibly, it becomes easier to win design-in discussions and maintain repeat business. The risk is spreading too widely and becoming indistinguishable in a crowded field. In a market with high concentration and many established players, clarity of positioning is a meaningful advantage.
Strategic Recommendations for Decision Makers
The DIP switches market rewards disciplined strategy because it is mature, application-diverse, and sensitive to both cost and reliability considerations. The following actions can help different stakeholders navigate the landscape with greater confidence.
For Manufacturers and Brand Owners
- Clarify segment positioning before expanding product breadth. A wider catalog is only valuable if it reinforces a credible application narrative or distribution advantage.
- Invest in documentation, packaging, and specification clarity. In mature component markets, accessible technical information and standardized formats can accelerate design-in and reduce sales friction.
- Manage sourcing and input cost exposure proactively. Where tariffs and material inflation are relevant, transparent cost planning and alternative sourcing options can protect both margins and customer trust.
- Use certification and reliability messaging carefully and accurately. Claims carry weight in high-value segments, but they must be supported by consistent process control and real product performance.
For Investors and Strategic Planners
- Focus on durable differentiation rather than volume growth alone. In a market growing at a moderate pace, value creation often comes from segment strength, repeat demand, and customer stickiness.
- Assess exposure to trade and input-cost volatility. Companies with flexible sourcing, geographically diversified production, or strong distributor reach may be better positioned to absorb disruption.
- Look for evidence of application-led strategy. Suppliers that serve specific high-reliability or high-value segments with clear qualification support are often more resilient than undifferentiated commodity players.
- Track portfolio and catalog activity as a leading indicator of commercial intent. New item releases, datasheet updates, and distributor availability can signal where a company is trying to build future demand.
For Procurement and Engineering Leaders
- Evaluate total cost of ownership, not just unit price. In applications where re-qualification, downtime, or field service matter, delivery reliability and documentation can outweigh marginal price differences.
- Qualify secondary sources for critical switch functions. Supply chain uncertainty makes it prudent to maintain alternatives for parts that are difficult to substitute once designs are locked.
- Align switch selection with actual environmental and service requirements. Over-specifying can increase cost unnecessarily, while under-specifying can create reliability risk in demanding environments.
- Keep specifications and sourcing documentation current. Updated datasheets and clear part parameters reduce engineering friction and support smoother lifecycle management.
Closing Perspective
The DIP switches market is not defined by rapid transformation, but by the steady accumulation of application-specific value, supply chain discipline, and competitive positioning. Growth is expected to continue at a moderate pace, supported by enduring demand across consumer, industrial, automotive, and telecommunications applications. Yet the real strategic question is not whether the market will expand, but how companies will navigate concentration, cost pressure, certification expectations, and shifting sourcing realities.
Businesses that succeed in this environment tend to treat DIP switches as more than simple electromechanical parts. They align product portfolios with real application constraints, maintain credible quality and documentation practices, and build sourcing resilience into their operating model. For readers seeking a deeper dive into segment-level revenue structures, regional dynamics, company-level positioning, and customized strategic scenarios, the full PW Consulting industry report provides a more granular view of the market and its forward trajectory.
For detailed analysis of this topic, please visit the official page: DIP Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com