

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PEMFC Market Outlook 2026: Strategic Imperatives for Decision-Makers
Executive summary
The Proton Exchange Membrane Fuel Cell (PEMFC) market is entering a decisive phase as organizations across mobility, stationary power, and industrial applications move from pilot projects to scaled commercialization. Our analysis shows the market expanding from approximately USD 163 million in 2020 to roughly USD 215 million in the base year (2025), with a projected compound annual growth rate (CAGR) of 16.5% across the 2026–2032 forecast window. By 2032, the industry is expected to approach the upper hundreds of millions in revenue, driven by more mature stack platforms, vehicle OEM adoption, and infrastructure alignment.
Proton Exchange Membrane Fuel Cell (PEMFC) Market
This introduction previews the strategic value of PW Consulting’s full PEMFC Market study for corporate leaders planning capital allocation, product roadmaps, and supply chain investments in 2026. It is designed as a high-fidelity teaser: we present the analytic posture, key dynamics, and competitive implications while intentionally withholding granular segment-level numbers and proprietary model outputs to encourage access to the full report.
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Why this study matters for 2026 decisions
-
Timing of investment: With the sector growing at a double-digit CAGR, 2026 will be a pivot year for converting technological parity into commercial scale. Companies deciding on manufacturing footprint, vertical integration, or long-term supplier commitments need a defensible view of market trajectories and scenario-based demand curves.
Proton Exchange Membrane Fuel Cell (PEMFC) Market -
Platform choices: PEMFC stack architectures and balance-of-plant decisions made in 2026 will define cost structures and upgrade pathways for a decade. Firms must weigh high-power density platforms against manufacturability and supply risk.
-
Procurement and sourcing strategies: As the industry moves from prototype to production, procurement windows for critical components—membranes, bipolar plates, and catalysts—will open and close rapidly. The full study provides procurement playbooks tied to vendor maturity and lead-time scenarios.
Market overview (what the macro numbers mean)
The PEMFC market’s historical trajectory (2020–2025) demonstrates a recovery from early commercialization bumps into sustained growth driven by fleet-level adoption and industrial stationary pilots. The base-year sizing in 2025 represents an inflection where modular, higher-power stacks and system-level integration improvements translate into clearer TCO pathways for end customers.
Projecting forward, the modeled 16.5% CAGR captures a convergence of factors: declining stack costs through volume and design-for-manufacturing gains; broader hydrogen ecosystem investments; and regulatory pushes that favor zero-emission heavy-duty and niche commercial platforms. The forecast horizon to 2032 presents a range of viable outcomes; the central scenario anticipates continued technology maturation and steady policy support, but upside and downside pathways are explicitly modeled in the report’s scenario suite.
What the PW Consulting PEMFC report contains (practical, actionable content)
-
Proprietary market-sizing methodology and transparent assumptions, calibrated to 2020–2025 historicals and stress-tested across demand scenarios for 2026–2032.
-
Supply-chain heat maps identifying concentration risks (critical materials, tooling, long-lead suppliers), supplier maturity tiers, and recommended dual-sourcing strategies for risk mitigation.
-
Technology deep dives—stack architectures, bipolar plate materials, membrane chemistries, and system integration trade-offs—benchmarked by power density, durability, and manufacturability.
-
Commercialization playbooks for OEMs and tier suppliers covering product roadmap sequencing, pilot-to-production gating criteria, and contracting templates aligned with performance warranties.
-
Regulatory and standards tracker focused on heavy-duty validation protocols, automotive low-temperature resistance requirements, and certification roadmaps that affect time-to-market.
-
Investor-grade competitive intelligence: leadership profiles, capability matrices, partnership ecosystems, recent deals, and scenario-based share trajectories for near-term strategy planning.
-
Financial models with sensitivity analyses (price curves, learning rates, capex/OPEX trade-offs) and a set of investment decision frameworks for M&A, joint ventures, and greenfield manufacturing.
Competitive landscape — what to watch in 2026
The PEMFC market remains moderately fragmented, with the top players accounting for a plurality but not a dominant share—an environment that benefits nimble technology leaders and well-funded incumbents alike. Key companies and their strategic positions include:
-
Ballard Power Systems (Vancouver, Canada) — Ballard’s FCgen platform targets mobility with high-power-density stacks. Recent commercial agreements signal a transition from development partnerships to volume-enabling supply relationships in the bus and coach segments. For corporate decision-makers, Ballard represents a partner of choice for mobility integrators seeking established stack platforms with system engineering support.
-
EKPO Fuel Cell Technologies (Dettingen/Erms, Germany) — EKPO is positioning production-ready NM-series modules for light- and medium-duty vehicles. Their public product showcases indicate a leap toward automotive-grade modules, which matters for OEMs planning platform integration within automotive supply chains and for suppliers assessing qualification timelines.
-
Cummins Inc. (Columbus, Indiana, USA) — Cummins brings deep systems integration experience and modular hydrogen engine products aimed at on- and off-highway transport. Their approach combines traditional OEM reliability engineering with fuel-cell-specific scaling strategies, making them a credible partner for truck and bus OEMs seeking turnkey system solutions.
-
Toyota Motor Corporation (Toyota City, Japan) — Toyota’s third-generation PEM systems emphasize durability and commercial-sector readiness. As a major OEM with vertically integrated capabilities, Toyota’s product developments set important benchmarks for lifecycle requirements and durability expectations in commercial deployments.
-
Intelligent Energy Limited (Cheltenham, UK) — Intelligent Energy’s high-power modules target both automotive and stationary markets. Their ability to bridge use cases offers partnership options for companies pursuing cross-market product lines or diversified revenue streams.
-
ElringKlinger / EKPO joint venture (Dettingen/Erms, Germany) — With bipolar-plate expertise and stack-module deliveries, the JV is strategically positioned to influence material choices and manufacturability. Their role underscores the importance of in-house materials capability for companies aiming to manage cost and weight trade-offs.
-
Hyundai Motor Company (Seoul, South Korea) — Hyundai’s integrated approach to stack and system development—often via joint collaborations—remains pivotal for commercial vehicle deployment strategies and for alliances seeking an OEM-led route to market.
-
Nedstack Fuel Cell Technology BV (Almelo, Netherlands) — Nedstack’s focus on mission-critical, high-power stacks positions them for niche opportunities where uptime and reliability are non-negotiable, such as rail or remote industrial power.
-
PowerCell Sweden AB (Aalborg, Denmark) — PowerCell’s systems for on-road, rail, and marine propulsion highlight cross-domain applicability and the importance of marine/rail certification pathways for firms targeting diversified mobility portfolios.
Recent signals and why they matter
-
Strategic commercial agreements—such as newly announced supply deals for bus engines—illustrate maturation in buyer-supplier contracting and the emergence of repeatable procurement cycles.
-
Product showcases and production-ready stack modules at major trade events are indicative of vendors closing the gap between lab performance and manufacturability; procurement teams should accelerate technical qualification timelines accordingly.
-
OEM product development milestones—particularly announcements of next-generation PEM systems—serve as durable benchmarks for expected lifecycle and durability targets in commercial fleets.
Technology, materials, and supply-chain dynamics
Material choices and manufacturing techniques remain the fulcrum of competitive advantage. Bipolar plates, for example, account for the vast majority of a stack’s weight and are therefore central to efforts in lightweight integration for automotive PEMFC systems. Advances in polymer and composite substrates (including high-performance PPS variants) can meaningfully improve durability and cost-per-kilowatt through simplified assembly and longer service intervals.
Regulatory and testing frameworks are also tightening. Heavy-duty PEMFC deployments are increasingly validated under accelerated stress test protocols designed to mimic high-temperature and dynamic-load conditions. For manufacturers, meeting these protocols is a gating criterion for fleet adoption. Parallel to this, light-duty production follows automotive standards emphasizing low-temperature resistance and common part procurement—requirements that shape supplier selection and design-for-assembly choices.
Risks, accelerators, and decision levers
-
Risk: supply concentration for critical components and catalysts can create lead-time bottlenecks that inflate capex and slow product rollouts. Mitigation strategies include long-term offtake agreements and localized manufacturing partnerships.
-
Accelerator: coordinated policy and infrastructure investments (refueling networks, incentives) materially shorten commercialization timelines and improve fleet economics.
-
Decision lever: choose platform partners based on a composite of power density, durability validation, and supplier maturity rather than single-metric comparisons. Our vendor scorecards quantify these trade-offs for procurement and strategic sourcing teams.
How to use the full PW Consulting PEMFC study in 2026
-
Board-level scenario planning: incorporate our scenario outputs into capital allocation and M&A playbooks to stress-test investments under different policy and technology uptake conditions.
-
Procurement roadmaps: align supplier qualification schedules with our recommended gating criteria to avoid time- and cost-overruns during pilot-to-production transitions.
-
Product strategy: use technology benchmarking to prioritize R&D investments that close the gap between lab metrics and field durability requirements.
-
Partnership evaluation: apply our competitive intelligence to select co-development partners and to negotiate fair-value commercial terms that reflect stage-of-maturity risk.
Closing and next steps
The 2026 decision window will reward clarity of assumptions and speed of execution. PW Consulting’s full PEMFC Market report provides the granular segmentation, regional and application-level forecasts, vendor matrices, and financial models needed to convert strategic intent into executable plans. This introduction has surfaced the principal dynamics, the competitive field, and the practical levers available to leadership teams—but the complete dataset, scenario outputs, and supplier-level insights are reserved for the full study.
To access the end-to-end models, detailed segment-level forecasts, and procurement playbooks that underpin the conclusions summarized here, please refer to the PW Consulting report landing page or contact our industry team for a briefing and customized decision-support package.
For detailed analysis of this topic, please visit the official page: Proton Exchange Membrane Fuel Cell (PEMFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mica Tape for Insulation Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise but analytically rigorous primer on the mica tape for insulation market — intended to orient executives and investment committees preparing for decisions in 2026. This briefing synthesizes macro growth dynamics, competitive posture, supply-side risks, and actionable playbooks. It deliberately demonstrates the analytical depth behind our full study while withholding granular segment tables and proprietary carve-outs that are available in the complete report.
Mica Tape for Insulation Market
Why this market matters now
Mica tape remains a mission-critical material across electrical insulation, high-temperature cable systems, and rotating machinery. Between 2020 and 2025 the market demonstrated resilient expansion, and our base-year analysis (2025) shows the industry at roughly USD 160 Million (revenue unit: Million). Under the baseline scenario, the market is projected to grow at a compound annual growth rate (CAGR) of 6.49% through our forecast horizon (2026–2032), reaching an estimated USD ~247 Million by 2032.
Mica Tape for Insulation Market
For industrial suppliers, OEMs in electrification and renewables, and private equity investors, this combination of steady growth and specialized application makes mica tape a classic “niche-essential” market: modest absolute size, high technical barriers, and meaningful value capture for differentiated players. That profile shapes the strategic choices available in 2026 — from bolt-on acquisitions to targeted manufacturing upgrades.
Mica Tape for Insulation Market
What the full PW Consulting report delivers (practical, transaction-ready)
- Market sizing and validated growth trajectories (2020–2025 historical base plus 2026–2032 forecasts), with sensitivity runs that stress-test raw-material shocks and regulatory tightening.
- Commercially oriented segmentation analysis (by product-type, application, and region) with addressable-market calculations and buyer personas to inform go-to-market and pricing strategies. Note: this executive brief intentionally omits the detailed splits; see the full report for tables and downloadable models.
- Supplier benchmarking and scorecards for the leading manufacturers, including manufacturing footprint, product breadth, quality certifications, and go-to-customer channels.
- Supply-chain and procurement playbook: raw mica sourcing maps, alternative-material pathways (including synthetic mica options), inventory & hedging templates, and multi-sourcing implementation guides.
- Regulatory and ESG risk assessment: mapping of extraction-related compliance, traceability frameworks, and practical roadmaps to demonstrate responsible sourcing to large OEMs.
- Commercial diligence toolkit for M&A and JV candidates: valuation sensitivities, integration checklists, and three-year synergy models tailored to small-cap consolidation targets.
- Scenario planning and decision triggers: a compact dashboard of KPIs and event triggers (price, capacity, regulatory milestones) that convert market intelligence into executable 90–180 day programs.
Competitive landscape — who matters and why
The industry displays moderate concentration: the top three players account for roughly one-third of market volume, with the top five covering less than half. This structure creates a mid-market environment where specialized capabilities, production reliability, and customer relationships — rather than sheer scale — determine commercial wins.
- Established European and Swiss producers (e.g., Von Roll, ISOVOLTA) maintain positions through premium phlogopite-based products and deep relationships with transformer and high-voltage equipment OEMs.
- US-based specialists (Axim Mica, Electrolock, Asheville Mica) compete on custom tape formats, VPI-compatible products, and service for motors/generators, supplying a strong aftermarket and OEM channel in North America.
- Asian manufacturers (including several Chinese producers) scale on cost and synthetic mica innovations, emphasizing fire-resistant cable segments and higher-volume cable coatings.
- Mid-sized niche players and converters (e.g., Cogebi, Krempel, Chhaperia) differentiate with custom slitting, adhesive systems, and application engineering support for motors, transformers and specialty cables.
Recent industry activity underscores incremental innovation and market engagement: Cogebi showcased new taping systems at a major wire show in Düsseldorf (April 2026), and several players presented EV-focused, fire-resistant mica tapes at global composites and electrical events in 2025. These moves indicate two concurrent trends — product specialization toward electrification and elevated marketing of compliance/traceability credentials.
Market dynamics and risk vectors
Four structural dynamics will govern outcomes in 2026 and beyond:
- Raw-material volatility and upstream concentration. The mica-paper value chain exhibits significant price sensitivity: a broader mica-paper market is estimated at over USD 1 billion, and a substantial share of manufacturers report price volatility. Procurement leaders should expect periodic price shocks and plan for flexible sourcing and hedging mechanisms.
- Regulatory and ESG pressure at extraction sites. Environmental regulation affects a material proportion of global mica extraction operations. For any supplier or buyer dependent on traceable, compliant mica, proving chain-of-custody and remediation commitments is no longer optional.
- Product innovation driven by electrification and compact motor design. OEMs are investing in thinner, more flexible mica tapes to meet higher power density and thermal-management requirements. R&D and co-development programs with key customers will be a growth lever.
- Supply-chain resilience and conversion capability. Manufacturers with converter capabilities (slitting, VPI-compatible coatings, adhesive systems) and near-market operations capture outsized value during tight supply windows.
Strategic imperatives for 2026 decisions
Executives evaluating capital allocation, M&A, or partnership strategies in 2026 should anchor their choices around three imperatives:
- Secure raw-material optionality and ESG traceability. Build a two-tier sourcing approach: (1) long-term offtake relationships with compliant phlogopite suppliers and (2) validated alternative suppliers (including synthetic mica producers) to mitigate single-source disruptions. Implement traceability pilots now to comply with buyer expectations in the next 12–18 months.
- Invest in application-focused R&D and converter assets. Thin, flexible mica products and adhesive systems tailored for EV motors and fire-resistant cable demand higher engineering input. Capex directed at precision slitting and coating yields both margin uplift and stickier customer relationships.
- Pursue selective consolidation and partnership models. With the market concentrated but not dominated, targeted acquisitions of regional converters or niche technology owners yield rapid route-to-market and incremental scale. Joint development partnerships with OEMs (motors, transformers, cable manufacturers) accelerate adoption and shorten sales cycles.
Decision playbook — practical steps for the first 180 days
- Day 0–30: Execute a supply-risk audit — identify single-source exposures, validate traceability, and model the P&L sensitivity to +/‑20% raw mica price swings.
- Day 30–90: Prioritize two pilot initiatives — a product co‑development with a target OEM for thinner tapes, and a dual-sourcing contract with an alternative material supplier. Establish KPIs (lead times, scrap rates, adhesion performance) and go/no-go gates.
- Day 90–180: Validate an inorganic roadmap — shortlist 3–5 acquisition targets or strategic JV partners that deliver conversion capability, geographic coverage, or proprietary tape technology. Use our commercial diligence checklist to run parallel valuations and integration planning.
Key indicators and decision triggers to monitor in 2026
Transform market intelligence into governance by tracking a compact set of leading indicators:
- Raw mica spot prices and availability: rapid increases should accelerate hedging and dual-sourcing moves.
- Regulatory milestones in major extraction jurisdictions: new restrictions will favor vertically integrated or synthetic-mica-backed suppliers.
- R&D adoption signals from OEMs (spec release or pilot orders for thinner tapes): prioritize manufacturing upgrades and capacity allocation.
- Major trade show product rollouts and partnerships (e.g., wire and EV-focused conferences): these are often a precursor to order flow.
Why PW Consulting’s full study is needed for execution
This briefing provides the conceptual playbook and high-level macro anchors (notably the 6.49% CAGR and the market scale trajectory from 2020 through 2032). The full PW Consulting Mica Tape for Insulation market report equips executives with the ground-level data and tools to implement these strategies: downloadable market models, deal checklists, supplier scorecards, and an M&A valuation framework tailored to this market’s dynamics. Our analysis translates the market’s steady growth into concrete action items that materially reduce execution risk.
Closing
For 2026, the mica tape market presents a classic opportunity for focused value capture: predictable secular tailwinds from electrification and thermal-management needs, coupled with supply-side frictions that reward operational excellence and proximate supply strategies. Whether your objective is to deepen technical differentiation, secure supply, or effect bolt-on consolidation, the right combination of procurement, product, and M&A moves — executed against the triggers described here — will convert market growth into reliable margin and strategic advantage.
To access the full dataset, segmented forecasts, company scorecards, and our actionable templates, consult the complete PW Consulting report. The detailed segment breakdowns and our interactive financial model are available exclusively in that release and are essential for transaction and budgetary decisions in 2026.
For detailed analysis of this topic, please visit the official page: Mica Tape for Insulation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dye-Sensitized Solar Cell Market: 12.44% CAGR to USD 378.76 Million by 2032 - PW Consulting
By pmarketresearch, 2026-07-30
Dye‑Sensitized Solar Cell Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Chief Industry Analyst and lead author of our latest Dye‑Sensitized Solar Cell (DSSC) Market study, I present a focused, actionable briefing to orient executive decisions in 2026. This market is at the confluence of material science innovation, building electrification, and the proliferation of connected devices — a rare intersection where small‑form factor photovoltaic modules can create outsized strategic advantage. Our research (base year 2025) synthesizes historical performance (2020–2025) with a rigorous forecast (2026–2032) to deliver a decision‑grade view of where investment, product development, and partnerships will create value.
Dye Sensitized Solar Cell Market
Why this research matters in 2026
-
Capital allocation: Distinguish between scalable product bets (e.g., BIPV, flexible modules) and niche pilots that require prolonged subsidy support.
Dye Sensitized Solar Cell Market -
Go‑to‑market timing: Use our near‑term market trajectory to optimize launch windows and pilot rollouts when procurement cycles in construction and IoT accelerate.
Dye Sensitized Solar Cell Market -
Supply chain prioritization: Identify which materials and sub‑components to secure now to avoid bottle‑necks during scale‑up.
-
M&A and partnership screening: Evaluate targets and partners with an evidence‑based view of market concentration, capability gaps, and technology differentiators.
-
Regulatory & standards readiness: Map product certifications and recycling obligations against anticipated policy shifts to reduce go‑to‑market friction.
Snapshot: market trajectory and what it implies
Our top‑line market sizing shows a clear growth story. The DSSC market expanded from a modest commercial base in 2020 and reached a material scale by the 2025 base year. Under our central forecast, the market continues to expand rapidly, reflecting strong adoption across indoor ambient harvesting, building‑integrated applications, and lightweight portable uses. The forecast period (2026–2032) is modelled with a compound annual growth rate of 12.44%, driving the market materially higher by the end of the horizon.
For executives, two implications follow immediately: first, the window for establishing meaningful share with differentiated products is narrow but real; second, companies that delay technology de‑risking and supply alignment risk becoming price takers as manufacturing and distribution scale.
What the PW Consulting report delivers — practical, transaction‑ready outputs
The report is designed for executives who need to act. It combines quantitative market architecture with hands‑on playbooks and decision frameworks:
-
Market sizing and methodology: Transparent assumptions, sensitivity scenarios, and clear delineation between end‑use demand, module shipments, and revenue streams.
-
Scenario modelling: Stress‑tested growth paths under conservative, central, and aggressive adoption cases to support capex and portfolio decisions.
-
Technology roadmaps: Comparative analysis of solid‑state vs liquid electrolyte approaches, dye chemistries (organic vs metal‑based), and encapsulation strategies tied to performance and lifetime trade‑offs.
-
Cost‑curve and manufacturing playbook: Unit cost breakdowns, scale thresholds, and recommended process investments to reach target margins at volume.
-
Commercial pilots and BIPV business cases: Ready‑to‑use templates for construct‑industry partners, LCOE estimates, and sample procurement specifications.
-
Supply‑chain stress tests & sourcing playbook: Prioritised sourcing actions for dyes, electrolytes, TiO2 and encapsulation materials plus contract templates for offtake and tolling.
-
Competitive benchmarking and M&A candidate shortlists: Profiles and capability gaps for incumbent and emerging players, with acquisition rationales and integration risks.
-
Regulatory mapping & recycling pathways: Jurisdictional impacts on product design, end‑of‑life logistics, and potential circularity commercial models.
Note: The report contains the full, detailed segmentation tables and region/application breakdowns necessary for tactical planning. This briefing intentionally omits those granular tables to preserve the primary value of the full dataset available in the published report.
Competitive landscape — who matters and why
The DSSC ecosystem today is comprised of specialized module manufacturers, chemistry innovators, and system integrators. Market concentration is moderate: the top three firms account for a meaningful share of commercial deployments, and the top five increase that share further — an important backdrop for partnership and pricing strategies.
-
Ricoh Company, Ltd. (Tokyo) : Ricoh’s focus on solid‑state DSSC modules optimized for indoor and ambient light positions it as a prime partner for IoT OEMs and smart‑space integrators. Their work on low‑lux performance and compact modules makes Ricoh a benchmark for indoor energy autonomy.
-
Solaronix SA (Aubonne) : Solaronix’s strength lies in high‑performance modules and chemistry (including ionic liquid electrolytes). Their recent strategic moves around organic dye synthesis (see developments) signal an intent to control more of the value chain and accelerate metal‑free dye options for large scale manufacturing.
-
G24 Power Ltd. (New South Wales) : G24’s GCell brand exemplifies commercial success in flexible, lightweight and semi‑transparent modules—attributes critical for BIPV and novel form factors.
Recent industry developments highlight the accelerating pace of commercialization: advanced encapsulation technologies, targeted acquisitions to secure dye pipelines, and construction industry partnerships to integrate DSSC into building envelopes. Each event reshapes the competitive calculus: durability and integration capability are quickly becoming as important as nominal cell efficiency.
Supply‑chain and raw material dynamics
The production economics of DSSC are governed by a small set of materials and component choices. Dye chemistry, electrolytes, and the semiconductor scaffold (commonly TiO2) are persistent cost drivers. Two material themes deserve executive attention in 2026:
-
Organic dyes versus ruthenium complexes: Organic formulations present a clear route to cost reduction and supply diversification, but require investment in synthesis scale‑up and stability enhancement.
-
Encapsulation and longevity: Advances such as laser‑assisted hermetic encapsulation materially improve lifetime and reduce balance‑of‑system costs; companies that internalize or secure these technologies will lower total ownership costs for their customers.
Procurement strategies should therefore prioritize long‑lead chemistry supplies, multi‑source electrolytes, and partnership agreements with encapsulation specialists to avoid costly rework after pilot deployments.
Policy, standards and integration opportunities
Public programs and standards are increasingly favorable to DSSC adoption in built environments. European initiatives that sponsored smart glass integration and subsequent policy analyses highlight two durable tailwinds: (1) regulatory encouragement for energy‑generating façades and (2) early support for recycling and material recovery frameworks. These policy levers lower adoption friction in construction and public procurement and are likely to create first‑mover advantages for suppliers aligned with recyclability and certification pathways.
Decision playbook for 2026 — prioritized actions
-
Immediate (0–6 months) : Commission a focused proof‑of‑concept with a BIPV or IoT partner using a solid‑state module; secure conditional supply agreements for critical dyes and electrolytes; audit IP exposure and freedom‑to‑operate for target chemistries.
-
Near term (6–18 months) : Execute a pilot that validates lifecycle metrics (degradation, encapsulation performance) and builds reference projects; initiate partnerships with construction firms or building product distributors; evaluate targeted acquisitions or licensing deals for dye synthesis capability.
-
Medium term (18–36 months) : Scale manufacturing to reach cost thresholds defined in the report’s cost curve, deploy standardized module SKUs, and close multi‑year offtake contracts with system integrators.
Closing: how to use this briefing
This briefing synthesizes the strategic conclusions of PW Consulting’s full DSSC Market study and outlines the actions most likely to create value in 2026. For teams making capital, product, or M&A decisions, the full report provides the granular segmentation tables, regional and application breakouts, supplier scorecards, and financial models necessary for transaction execution. Reach out to PW Consulting to access the complete dataset, tailored scenario modelling, and advisory support to convert this market growth into firm value.
For detailed analysis of this topic, please visit the official page: Dye Sensitized Solar Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Li-ion Ternary Precursor Market to Grow at 9.5% CAGR through 2032 | PW Consulting
By pmarketresearch, 2026-07-30
Li‑ion Battery Ternary Precursor Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As battery supply chains rewire around electrification, energy storage and regulatory imperatives, the global market for ternary precursors (NMC/NCA hydroxide precursors) has moved from niche commodity to strategic raw material. PW Consulting’s new market research (base year 2025; historical window 2020–2025; forecast 2026–2032) models this transition with a 9.5% compound annual growth rate across the forecast period and a clearly accelerating revenue profile beginning 2026. For corporate leaders who must set sourcing, capacity and partnership decisions in 2026, this briefing distills the implications our full study surfaces — while deliberately omitting the granular regional and application splits that are available only in the full report.
Li-ion Battery Ternary Precursor Market
Why this matters for 2026 strategy
- Timing of capacity decisions: 2026 is the inflection year where demand visibility, capex lead times and supply‑chain reconfiguration converge. Manufacturers who finalize investment plans in 2026 will be executing into a market materially larger than the 2025 baseline.
- Procurement and raw material risk: Price volatility (including recent movements in precursor and nickel feedstock pricing) is compressing margins for some producers and creating windows for secured‑volume strategies.
- Regulatory compliance and circularity: Rising traceability and recycling requirements are shifting supplier evaluation criteria from price alone to provenance, CO2 footprint and recycling integration.
- Competitive intensity and concentration: The market exhibits moderate concentration (CR3 and CR5 metrics indicate room for scale players to influence flows, while also leaving niches for specialized entrants).
Market trajectory — what the top‑line numbers tell you
PW Consulting’s topline modelling shows a sustained expansion from the 2025 base toward a substantially larger market by the end of the 2026–2032 forecast window, driven by EV penetration, stationary storage deployments and higher nickel content recipes in cathode chemistries. A single percentage CAGR masks structural shifts beneath: a rising share of high‑nickel chemistries, differentiated requirements between power and consumer applications, and a growing role for recycled feedstocks. Taken together, the headline 9.5% CAGR is best interpreted as demand growth plus compositional change — not uniform price expansion.
Li-ion Battery Ternary Precursor Market
Immediate signals to act on in 2026
- Secure feedstock chains now: Upstream nickel and precursor pricing dynamics have shown short cycles of disruption. For example, recent market reports note a measured uptick in precursor NCM811 pricing (reported at about 12.03 RMB/kg with modest month‑on‑month movement) while nickel sulfate costs eased slightly (reported near 9.48 RMB/kg). These movements create windows to renegotiate contracts or lock in fixed volumes.
- Prioritize traceable, recyclable supply: Regulatory developments such as the EU Battery Regulation are increasing the compliance burden for suppliers and OEMs. Buyers that can demonstrate traceability and recycling integration will minimize regulatory risk and extract premium access to certain markets.
- Differentiate by product portfolio and technical capability: High‑nickel precursors and single‑crystal offerings are increasingly rewarded in power applications. Evaluate suppliers not just on capacity but on capability to supply high‑Ni grades with consistent quality.
- Plan for strategic stockpiling but avoid stranded inventory: Policy stimuli (notably past subsidies and incentive programs) have previously prompted stockpiling behaviour. In 2026, companies should balance buffer inventory for continuity with flexible contracts to avoid exposure to rapid chemistry shifts.
What our full report delivers (practical, transaction‑ready insights)
PW Consulting’s Li‑ion Battery Ternary Precursor Market study is built for executives who need actionable intelligence rather than descriptive narrative. The full deliverable includes:
Li-ion Battery Ternary Precursor Market
- Market sizing and model logic (2020–2032) with sensitivity scenarios tied to EV adoption, grid storage rollouts and high‑Ni chemistry penetration.
- Demand drivers and elasticity analysis — segmented by application archetypes and product type — with the modelling assumptions fully auditable.
- Supply‑side mapping: plant locations, capacity build‑outs, feedstock linkages and technology differentiators (sintered vs. hydroxide, single‑crystal process steps, recycled precursor streams).
- Cost stacks and margin curve benchmarking under multiple feedstock price scenarios to inform pricing, hedging and procurement strategies.
- Regulatory and trade overlays — including traceability requirements, recycling quotas and subsidy regimes — with compliance roadmaps per major jurisdiction.
- Deal support: M&A screening, JV partner scorecards and an acquisition valuation framework calibrated to precursor market dynamics.
- An interactive dashboard that lets users re‑run the forecast under custom inputs (chemistry mix, regional demand ramps, feedstock inflation), enabling rapid scenario testing for board presentations.
Competitive landscape — what to watch among active players
The precursor supplier set includes incumbent scale producers, specialized technology firms and recycling‑focused entrants. Competitive posture matters: a supplier’s ability to offer integrated recycling, feedstock security or differentiated high‑nickel grades is increasingly decisive.
- GEM Co., Ltd (Shenzhen, China) — A vertically integrated player combining precursor production with recycling and nickel resource projects. Strategic partnerships and capital markets moves (including recent H‑share listing activity and collaboration with major battery manufacturers) position GEM to compete on both scale and circularity.
- CNGR Advanced Material Co., Ltd (Tongren, China) — Broad product lineup covering common ternary formulations and higher‑nickel variants. CNGR’s refreshed catalog and product development emphasize responsiveness to EV power battery requirements.
- Zhejiang Huayou Cobalt — Known for high‑performance power battery precursors and an emphasis on high‑nickel materials; strong upstream positions in cobalt and cobalt processing support integrated value propositions.
- Umicore (Brussels, Belgium) — European incumbent with strengths in closed‑loop recycling and sustainability credentials; well‑placed to serve OEMs prioritizing compliance and lifecycle performance.
- Ascend Elements (United States) — An emerging differentiator through recycled hydroxide precursors and cathode material production; recent product launches underline commercial maturity in recycled NMC grades for EV, defense and grid markets.
- Regional specialists (Tanaka Chemical, Ronbay, Greatpower, Kelong, Fangyuan) — A mix of high‑purity suppliers and high‑nickel innovators serving national champions and regional OEM clusters. These firms often compete on technical quality, speed to qualification and cost efficiency for local customers.
Recent developments underscore strategic trends: partnership deals to build recycling networks, product catalog expansions into high‑nickel grades, and new recycled precursor product launches. These moves illustrate a two‑track competition — scale and integration versus technical differentiation.
Strategic playbook for 2026
- Supply security first: Negotiate multi‑year offtakes with performance clauses tied to chemistry mix. For OEMs, prioritize suppliers offering both feedstock transparency and recycling pathways.
- Capex discipline: For producers, prioritize brownfield expansions and modular capacity that can be reconfigured for different grades; defer large greenfield spend until offtake commitments are secured.
- Regulatory arbitrage: Map regulatory timelines across commercial markets and align production or recycling investments to jurisdictions where compliance premiums are largest.
- M&A and partnering: Target assets that add either feedstock security (mines, hydromet capabilities) or recycling and refining that shorten the loop from scrap to precursor. Use earnouts to bridge valuation gaps given chemistry evolution risk.
- Product strategy: Invest in R&D for high‑nickel process controls and single‑crystal technologies where performance gains translate to higher value capture.
Reading the noise — practical risk adjustments
Industry headlines will continue to create short windows of volatility: raw material price blips, policy announcements and regional subsidy changes. Translate these into portfolio actions: adjust hedges for nickel feedstock exposures, tier supplier pools by compliance readiness, and maintain scenario playbooks that include accelerated EV adoption, delayed recycling rollouts, and rapid chemistry substitution.
How to use this research in your 2026 planning cycle
- Board level: Use the scenario dashboard to validate growth assumptions embedded in strategy documents and to stress‑test capex timelines against downside chemistry scenarios.
- Commercial teams: Recalibrate procurement KPIs to include traceability, recycled content and qualification timelines; use supplier scorecards from the report to prioritize negotiation targets.
- Corporate development: Screen acquisition targets using the report’s valuation framework and CR indexes to identify scale gaps and strategic niches.
- R&D and operations: Align product roadmaps to the high‑value chemistries and quality attributes the report surfaces, and use the cost stack analysis to guide process improvements.
Concluding note — why PW Consulting’s study is decision‑ready
Our market study combines a transparent, auditable forecast model, supplier‑level commercial intelligence and regulatory overlays designed for transaction use. It converts the macro picture — a market expanding at ~9.5% CAGR from 2026 onward — into operational choices: who to partner with, where to site capacity, how to structure contracts and which product bets to back.
This briefing intentionally highlights strategic findings while withholding full granular splits (regional, application and specific segment financials) to preserve the report’s role as your operational playbook. For executive teams preparing 2026 budgets and multi‑year strategic plans, accessing the full dataset and interactive tools is the logical next step.
Next step
Access the full PW Consulting Li‑ion Battery Ternary Precursor Market report to unlock the detailed regional and application breakdowns, supplier scorecards, interactive scenario tools and transaction playbooks that support binding 2026 decisions.
For detailed analysis of this topic, please visit the official page: Li-ion Battery Ternary Precursor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LDI Systems Market to Grow at 7.8% CAGR, Reach USD 1,345M by 2032
By pmarketresearch, 2026-07-30
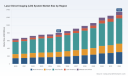
Laser Direct Imaging (LDI) Systems Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer on the Laser Direct Imaging (LDI) systems market intended to shape boardroom decisions in 2026. Our research, anchored on a 2025 base year and a historical review spanning 2020–2025, projects a sustained expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.8%. Measured in Million USD, the market has grown from a base measured in 2020 and, with continued momentum in advanced electronics and specialty applications, is projected to reach north of USD 1.3 billion by the end of the forecast horizon. This briefing highlights the strategic inflection points, competitive dynamics, actionable recommendations, and the practical tools contained in our full report—while deliberately withholding the granular segment-level tables that enterprise teams must access via our research portal.
Laser Direct Imaging (LDI) System Market
Why LDI matters to 2026 strategic plans
- Technology convergence is accelerating. LDI is migrating from a PCB-centric enabler toward a crossroad technology used in advanced packaging, display substrates, and niche high-reliability markets (aerospace, medical). This expands addressable use cases and drives demand for higher precision, throughput, and process automation.
- Capital allocation trade-offs are becoming nuanced. Buyers and equipment OEMs face choices between retrofitting legacy exposure lines with AI-assisted alignment and vision upgrades versus greenfield investment in next-generation multi-beam or LIDE-capable platforms.
- Regulatory and quality requirements are structuring buyer behavior. Certifications and compliance frameworks (FDA 21 CFR Part 11, MDR, AS9100, ISO 13485 and comparable automotive/aerospace standards) materially increase time-to-deploy and create differentiated pricing tiers for compliant systems.
Market dynamics with strategic implications
- Measured growth, predictable runway. Our market model (base year 2025) shows steady expansion through 2032 at ~7.8% CAGR. For decision-makers, that translates into a predictable demand envelope for capacity planning, with particular read-through for capital equipment suppliers and financing arms supporting OEMs and fabs.
- Automation, vision, and AI as table stakes. In recent field deployments, a majority of new LDI installations included vision systems and auto-calibration modules to improve alignment and reduce operator dependence. Similarly, a growing share of platforms launched during 2025 incorporated AI-assisted calibration workflows, producing measurable reductions in alignment deviation. For buyers, prioritizing control software and sensing subsystems will deliver outsized operational value versus equivalent mechanical upgrades.
- Specialty end-markets command premium economics. Aerospace and healthcare customers collectively represent a meaningful premium segment within the LDI market, reflecting higher compliance and traceability requirements. Expect longer procurement cycles, greater service attach rates, and higher lifetime value per machine in these verticals.
- Product differentiation is sharpening. Demand for LIDE technologies (particularly for displays and emerging glass-substrate applications) and for flexible single-beam versus multi-beam architectures is reshaping product roadmaps. Providers that align optical performance with software-driven process control will increasingly capture higher-margin engagements.
Competitive landscape — clarity on who matters
The supplier market is moderately concentrated, with the top-tier players controlling a majority share of global revenue. This concentration creates a competitive environment where technology leadership, installed base services, and certification-compliant capabilities determine market share expansion.
Laser Direct Imaging (LDI) System Market
- Orbotech Ltd. (Israel) — Strengths: multi- and single-beam LDI platforms engineered for high-precision PCB and semiconductor workflows, coupled with integrated defect-detection. Strategic posture: leverage deep inspection and process integration to upsell software and service contracts to Tier-1 electronics manufacturers.
- Screen Holdings Co., Ltd. (South Korea) — Strengths: high-throughput multi-beam systems with advanced alignment and process automation. Strategic posture: double down on volume-driven customers where throughput and alignment accuracy are prioritized; use automation as a moat against lower-cost alternatives.
- Manz AG (Germany) — Strengths: compact, modular LDI systems and semiconductor equipment with a flexibility focus. Strategic posture: following recent divestment decisions in non-core areas, Manz is concentrating R&D and commercial efforts on LDI and advanced packaging, positioning for selective partnerships with systems integrators.
- LPKF Laser & Electronics AG (Germany) — Strengths: single-beam flexibility, LIDE technology for displays and packaging. Recent moves: reported progress in LIDE technology and flagged growing demand for AI-driven use cases and glass substrate processing. Strategic posture: exploit momentum in adjacent display and packaging markets to broaden addressable revenue and promote higher-margin application-specific systems.
- Han’s Laser Technology (China), ORC Manufacturing (Japan), Delphi Laser (China) and regional specialists — Strengths: regional manufacturing scale, cost-competitive systems, and integrated service offerings tailored to local fabs. Strategic posture: serve commoditized segments and fast-follow in select high-growth verticals; attractive partners for channel expansion and aftermarket services.
- Limata GmbH and Miva Technologies GmbH (Germany) — Strengths: energy-efficient platforms and niche substrate expertise (aerospace, medical). Strategic posture: focus on compliance-heavy niches and energy efficiency as decision levers for customers with sustainability targets.
Recent industry developments to watch
- LPKF’s product updates in 2025 and prior market statements highlight an accelerating migration of LDI into glass and AI-assisted use cases—creating adjacent revenue opportunities beyond traditional PCBs.
- Manz’s strategic refocus and selective divestments illustrate how vendors are optimizing portfolios to concentrate on higher-margin, high-growth LDI and semiconductor offerings.
- Across suppliers, there’s an observable shift toward bundling software, calibration services, and extended warranties—turning hardware sales into platform-led recurring revenue models.
What our full report delivers (operationally focused)
This briefing is an executive extract. The full PW Consulting LDI systems market study — structured for commercial teams, product strategists, and private-equity investment committees — includes:
Laser Direct Imaging (LDI) System Market
- A transparent demand model with annual market size by year (2020–2032), scenario sensitivity and downside/upside triggers calibrated to macro-electronics cycles. (Base year: 2025; forecast period: 2026–2032.)
- Supplier scorecards: capability matrices, roadmaps, and aftermarket economics to inform supplier selection and make-versus-buy decisions.
- Go-to-market playbooks for OEMs and channel partners covering pricing, service packaging, and certification pathways for aerospace/medical customers.
- CapEx and ROI calculators tailored to retrofit vs. replacement choices, including throughput and yield uplift assumptions driven by AI-assisted calibration benefits.
- Regulatory and compliance matrix, highlighting required certifications by end-market and implications for time-to-market and installed-base conversions.
- M&A and partnership heat maps that identify tactical consolidation targets and partnership archetypes by capability, geography, and customer adjacency.
Note: to preserve the strategic advantage of our clients, the report’s detailed segment-level tables and supplier-specific revenue splits are available exclusively via the full report portal. This executive extract intentionally omits granular segmentation figures to ensure commercial leverage for subscribers and clients.
Actionable recommendations for 2026 planning cycles
- For OEMs: Allocate R&D budget toward AI-assisted calibration, vision systems, and modular architectures that shorten customization cycles. Prioritize software-driven service bundles to convert one-time sales into recurring revenue.
- For PCB and packaging manufacturers: Run parallel capex pilots that compare retrofit AI-vision kits with new LDI platforms over 12–18 month windows. Build procurement clauses that capture certification deliverables (traceability, audit logs) up-front to avoid costly retrofitting for regulated customers.
- For investors: Seek targets with differentiated software stacks, high service attach rates, and an installed base in regulated end-markets. Be cautious on pure hardware plays without software or service monetization pathways.
- For service providers and system integrators: Develop certification and qualification services for aerospace and medical customers; these services can justify premium pricing and faster payback for customers upgrading equipment.
- For supply chain managers: Secure long-lead optical components and semiconductor laser sources through multi-year contracts or strategic partnerships, as localized supply disruptions can lengthen lead times and increase deployment risk.
Risk scenarios and mitigations
- Regulatory tightening. Mitigation: pre-qualify platforms against relevant standards and maintain an audit-ready documentation process.
- Rapid tech substitution. Mitigation: preserve flexibility by modularizing platforms and maintaining a balanced R&D portfolio across optics, control software, and services.
- Regional competitive pressure from low-cost suppliers. Mitigation: differentiate on service, certification, and integrated inspection capabilities—areas where price competition is less effective.
Conclusion: The LDI systems market presents a predictable growth runway with clear strategic inflection points around automation, AI-driven calibration, and regulatory specialization. In 2026, the companies and investors that translate these structural trends into product roadmaps, service strategies, and disciplined procurement will capture disproportionate value as the market scales toward the forecast horizon.
To access the full dataset, vendor scorecards, segmentation tables, and scenario models that underpin this briefing, please consult the complete PW Consulting LDI Systems Market Report on our research portal. The detailed segment-level analytics and downloadable Excel models are available to subscribers and licensed clients.
For detailed analysis of this topic, please visit the official page: Laser Direct Imaging (LDI) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
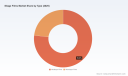
Silage Films Market — Strategic Imperatives for 2026 Decision‑Makers
As the global agricultural value chain navigates tighter environmental regulation, material-cost volatility and evolving on‑farm preservation practices, silage films have moved from a tactical procurement item to a strategic lever for feed quality, waste reduction and ESG compliance. PW Consulting’s latest Silage Films Market study (base year 2025) synthesizes five years of historical dynamics and a forward-looking forecast across 2026–2032 to deliver the actionable intelligence executives need to set winning 2026 priorities.
Silage Films Market
Executive snapshot: what this research enables
-
Clarity on market scale and trajectory: the silage films market has expanded steadily in the first half of the decade and is modelled to continue growing at a mid-single-digit compound annual growth rate through the forecast horizon. This projection frames realistic demand scenarios for procurement, production planning and investment gating decisions.
Silage Films Market -
Competitive positioning for buyers and suppliers: our study decodes the strategic moves of global incumbents and agile challengers — from product innovation to channel plays — enabling procurement teams to evaluate total cost of ownership rather than price per roll.
Silage Films Market -
Regulatory and standards impact: the analysis translates forthcoming standards and regionally accelerating plastic‑use policies into quantified implications for product specification, cost curves and substitution pathways.
-
Practical toolset for 2026 execution: templates, scenario models and a procurement playbook included in the report accelerate decision cycles and reduce implementation risk.
Market trajectory and what it means for corporate strategy
Between 2020 and 2025 the market recorded steady expansion as feed preservation practices intensified and multi‑layer film adoption increased. By the base year the market had grown materially compared with the start of the decade; our modelling projects continued growth through 2032 at a compounded annual growth rate of 4.82% for the forecast period 2026–2032, with total market value approaching the mid‑single‑digit million USD range by 2032. For industrial players this pace of growth signals predictable base demand, but the strategic value accrues to those that capture improved margins through product differentiation, waste-reduction features, and integrated service offers (e.g., collection and recycling partnerships).
Three commercial implications stand out:
-
Margin pressure will shift from pure price competition to performance economics. Buyers increasingly measure film value by silage loss reduction, labor savings and end‑of‑life handling costs. Suppliers that can demonstrate lower net cost per tonne of preserved forage will command premium positions.
-
Innovation in layer architecture and barrier technologies is the primary path to differentiation. Recent product introductions show suppliers trading thickness for barrier performance and recyclability features; these trade-offs will determine technical winners as standards and buyer expectations evolve.
-
Supply chain resilience matters. Raw material feedstock and film‑line capacity constraints create timing risk for large contracts. Contract design, inventory strategy and flexible manufacturing footprints will be decisive for both suppliers and large agricultural cooperatives.
Competitive landscape: incumbents, specialisms and strategic moves
The silage films market is neither monopolistic nor atomized — concentration metrics show a market where a handful of global players exert significant influence but meaningful share remains distributed among regional specialists and innovative challengers. This structure creates opportunities for selective consolidation, targeted partnerships and differentiated niche plays.
-
Rani Plast (Finland) — recognized for very wide, high‑performance multi‑layer films tailored to bunker and large bale applications. Their engineering focus and scale in specialized extrusion give them advantage in large‑format contracts.
-
Coveris (Austria) — a premium film producer with a history of innovation in stretch and oxygen‑barrier films; their branded solutions target operators seeking performance assurance and traceability.
-
Berry Global Inc. (United States) — a leading supplier with portfolio breadth, including multi‑layer film systems designed to reduce on‑farm losses through integrated Film&Film combinations and channel reach in major agricultural markets.
-
RKW Group (Germany) — specializes in polyolefin-based films and nets; their strength lies in industrial production consistency and established distribution in European markets.
-
Trioworld (Sweden) — positioned around sustainability claims and alternatives, offering products that emphasize reduced environmental footprint and higher oxygen permeability where appropriate.
-
Polifilm (Germany) — notable for co‑extruded silage films with manufacturing flexibility and product formats designed for grass and maize handling nuances.
-
Lallemand Animal Nutrition (Canada) — an important product innovator in oxygen‑barrier films; their OxyBlock range has reshaped discussions about performance trade‑offs between barrier technology and material usage.
Recent competitive activity underscores the priority suppliers place on barrier technology and multi‑layer architectures. A notable product launch in early 2026 introduced oxygen‑barrier variants that blend EVOH layers with multi‑layer extrusion designs; this demonstrates how performance-led launches can raise the specification floor for premium forage preservation.
Regulatory and standards shift: what to watch and how to respond
Regulation and standards are no longer background noise — they are key decision inputs. The introduction of new certification requirements for thermoplastic silage films has already raised the technical minimums suppliers must meet to compete in several major markets; compliance will influence product roadmaps and capital spend on line upgrades. Meanwhile, an accelerating policy momentum across several jurisdictions signals tighter limits on single‑use plastics and higher expectations for recyclability and take‑back programs.
For corporate decision‑makers, the immediate priorities are clear:
-
Integrate standards and regulatory scenarios into procurement contracts so that specifications can evolve without frequent price renegotiations.
-
Assess capital exposure to retool or qualify suppliers under updated certification regimes and build contingency sourcing options.
-
Develop circularity pilots that reduce end‑of‑life risk exposure and create differentiation—collection logistics and chemical recycling or compound‑recover options are increasingly commercially viable.
What the PW Consulting report packs (practical, executable sections)
This study is designed as an execution toolkit for senior leaders and functional teams. Highlights include:
-
Robust market sizing and demand-driver narrative that links agriculture macrotrends to film consumption dynamics (detailed annual baseline and forecast by global market, with scenario variance and sensitivity to feedstock price paths).
-
Competitive capability matrix and vendor dossiers that map product portfolios, manufacturing footprints, R&D focus and channel strategies for the major players — enabling faster supplier pre‑qualification.
-
Procurement playbook: RFP templates, scoring matrices weighted for performance economics, contract clauses for regulatory compliance and escalation, and inventory hedging strategies.
-
Product economics models: thickness vs. barrier trade‑offs, net cost per tonne preserved forage, and a capex vs. margin ladder for line upgrades to meet higher layer or barrier requirements.
-
Regulatory impact assessment and a policy-to-product roadmap that translates standards into technical requirements and cost implications.
-
M&A and partnership screen: acquisition targets and JV criteria for buyers seeking upstream control or technical capability in barrier technologies and recycling.
-
Implementation case studies and a 100‑day action plan for farm cooperatives, processors and film manufacturers.
How to use this intelligence in 2026 planning cycles
Executives should treat the report as both situational intelligence and an operating playbook. Recommended use cases include:
-
Capital allocation: use the report’s capex sensitivity and demand scenarios to prioritize extrusion-line upgrades, new barrier layer investments or recycling systems.
-
Procurement transformation: adopt the procurement templates and TCO models to transition from price‑only selection to performance‑based contracting.
-
Product strategy: align R&D roadmaps to the technical minimums implied by new standards and to the growing buyer preference for reduced‑loss, lower‑waste solutions.
-
M&A screening: focus on targets that add distinct technical IP (e.g., EVOH barrier integration), regional logistics advantages or circularity competence to accelerate differentiation.
Final note — why this is a “must‑read” before you sign any 2026 contracts
The headline market growth is not the story by itself; the competitive economics of silage films in 2026 will be determined by who can convert barrier performance and circularity into verifiable, farm‑level outcomes. Our study provides the framework and tools to do that conversion — but, in keeping with the “trailer” principle, this public summary intentionally omits the granular segmentation and granular regional breakdowns that buyers and investors need for contract negotiation and investment due diligence.
For the full dataset, supplier scorecards, granular scenario tables and the operational playbooks that support immediate 2026 actions, access the complete PW Consulting Silage Films Market report. The detailed annexes contain the fine‑grained splits, certification‑aligned specifications and supplier benchmarking that will materially shorten your path from insight to implemented advantage.
For detailed analysis of this topic, please visit the official page: Silage Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: THz Market to Reach USD 994.54 Million by 2032 at 15.8% CAGR
By pmarketresearch, 2026-07-30
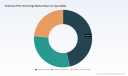
Terahertz (THz) Technology Market: A Strategic Roadmap for 2026 Decision‑Makers
This briefing frames PW Consulting’s latest Terahertz Technology Market research as an operational guide for executive teams planning investments, product roadmaps, and partnerships during 2026. Built on a 2025 base year and a granular forecast window spanning 2026–2032, the study quantifies a fast‑growing industry (CAGR 15.8%) that moved from an early commercial base a few years ago to a near‑billion dollar opportunity by the end of the forecast period. The market rose from roughly USD 205.7 million in 2020 to USD 358.5 million in 2025 and is projected to approach roughly USD 994.5 million by 2032 — framing a multi-fold expansion that materially changes strategic options for incumbents and new entrants alike.
Terahertz (THz) Technology Market
Why this report matters in 2026
- Timing: 2026 is the inflection point when lab‑grade THz capability matures into industrial and regulated applications — battery production inspection, advanced packaging inspection, and public security among them. Early movers who translate lab demonstrations into repeatable factory and clinical deployments will capture disproportionate value.
- Standards and regulatory momentum: New ETSI guidance documents (GR THz 003 and GR THz 004) and continuing IEEE activity are shifting THz from an exploratory physics domain to a standards‑driven engineering discipline. Procurement, certification, and spectrum planning decisions in 2026 must anticipate accelerating regulatory requirements.
- Capital market signals: Public market activity — including the first UK/European THz company listing on Korea’s KOSDAQ in early 2026 — validates exit routes and corporate development strategies, influencing valuation expectations for scale‑up financing and M&A.
- Competitive structure: The sector is moderately concentrated (top‑3 firms represent roughly 35% of measured market activity; top‑5 approximately 42%), leaving meaningful whitespace for differentiated technology and go‑to‑market plays.
What the report delivers (practical content)
- Transparent market sizing and a consistent forecasting methodology (2026–2032), with scenario variants and sensitivity to commercial adoption curves.
- Technology deep dives that explain trade‑offs across imaging, spectroscopy and communication approaches, including component ecosystem maps (sources, detectors, optics, electronics, and software stacks).
- Use‑case ROI toolkits and sample business cases tailored to manufacturing inspection, medical diagnostics, non‑destructive testing (NDT), and security screening.
- Vendor scorecards, procurement checklists and PoC templates designed to reduce trial‑to‑pilot cycle times and de‑risk supplier selection.
- Regulatory and standards tracker aligned to ETSI/IEEE outputs and regional compliance considerations, plus an IP and patent landscape summary to inform licensing and freedom‑to‑operate strategies.
- Corporate development playbooks — M&A screening criteria, partnership archetypes, and valuation benchmarks linked to technology maturity and revenue model.
Market dynamics and growth drivers
The market’s 15.8% CAGR is driven by three converging phenomena: maturing component technology, clarifying regulatory/std frameworks, and increasing commercial utility across high‑value verticals. Component costs and integration complexity continue to fall as silicon‑based detectors, compact THz cameras and fiber‑laser time‑domain solutions reach higher volumes. Standardization work — notably ETSI’s GR THz 003 and GR THz 004, and ongoing IEEE activity — reduces technical and procurement uncertainty, accelerating enterprise adoption.
Terahertz (THz) Technology Market
Commercially, the most visible near‑term traction is in industrial inspection (automotive coatings, battery electrode quality), semiconductor advanced packaging inspection, and targeted medical diagnostics — sectors where non‑ionizing THz imaging or spectroscopy offers unique contrast or throughput advantages. Parallel advances in scanner architectures (both active and passive), detector arrays, and integration with robotics and factory automation are turning lab demonstrations into scalable deployments.
Terahertz (THz) Technology Market
Competitive landscape — who matters and why
- TeraView Limited (Cambridge, UK) — A leader in applied THz imaging and spectroscopy focused on semiconductor packaging inspection, automotive paint/coating analysis, battery electrode production, and pharmaceutical quality control. Recent strategic moves include a KOSDAQ listing (Feb 2026) and partnerships to accelerate entrance into Korean EV battery lines and robotic inspection systems. These signal both capital access and intensified vertical go‑to‑market focus.
- TOPTICA Photonics AG (München, Germany) — Strong in terahertz time‑domain systems for spectroscopy, imaging and metrology. TOPTICA’s emphasis on laser‑source fidelity and metrology positioning makes it attractive for high‑precision lab and industrial customers looking for deterministic performance.
- Menlo Systems GmbH (Martinsried, Germany) — Offers THz time‑domain solutions built on mature fiber‑laser platforms; notable for over 300 systems deployed in field operations. Their installed base and precision orientation position them well for scientific and high‑accuracy industrial users.
- HÜBNER Photonics GmbH (Kassel, Germany) — Provides integrated THz imagers and spectrometers targeting public security and industrial inspection, with active participation in key optics and materials conferences — an indicator of pipeline momentum and research partnerships.
- TeraSense Group Inc. (Moscow, Russia) — Pioneers semiconductor‑based THz cameras, detectors and scanners. Their work on passive body scanners and compact detectors points to lower‑cost, high‑throughput deployments for security and NDT; geopolitical and supply‑chain considerations will inform regional go‑to‑market choices.
- Luna Innovations Incorporated (Roanoke, VA, USA) — Focused on industrial THz sensing (e.g., T‑Gauge solutions) with collaboration footprints in battery and materials inspection. Their industrial monitoring orientation is valuable for process control applications.
- TicWave Solutions GmbH (Germany) — Develops compact silicon‑based THz cameras and real‑time video systems; these product profiles are optimized for security screening and inline inspection integrations where throughput and form factor matter.
Recent developments to watch (early 2026)
- TeraView’s KOSDAQ listing (Feb 2026) — first UK/European THz company to list on that exchange, indicating investor appetite and a potential benchmark for future financings.
- Patent activity: Beijing Research Institute of Telemetry granted an EP patent (Apr 2026) for multimode real‑time THz imaging — a reminder that patent fences are forming around system architectures and real‑time modes.
- Partnerships and product pipelines: TeraView’s collaborations with Axbis and Doolim‑Yaskawa (May 2026) and TeraSense’s development of a passive THz body scanner (May 2026) illustrate the push to industrialize and scale vertically oriented solutions.
- Industry engagement: HÜBNER’s trade show participation and Menlo’s broad installed base underscore the sector’s transition from research showcases to revenue‑generating deployments.
Risk matrix and mitigation strategies
- Technical risk — source power, detector sensitivity and integration complexity: mitigate with modular architecture, hybrid sensor fusion, and staged PoC milestones tied to performance KPIs.
- Regulatory & standards risk — evolving ETSI/IEEE guidance can change product requirements: maintain active standards engagement and build compliance roadmaps into R&D timelines.
- IP & patent risks — growing patent activity may raise licensing needs: invest in targeted freedom‑to‑operate analyses and consider portfolio cross‑licensing as part of partnership negotiations.
- Supply chain & geopolitical risk — specialized components and regional concentration of vendors: diversify suppliers, localize assembly for key markets, and plan component lifecycles in procurement.
- Market adoption risk — proof to scale gap: use staged commercial pilots with measurable ROI thresholds and require supplier‑backed integration commitments.
Actionable priorities for 2026
- For R&D leaders: prioritize product architectures that balance cost, throughput and regulatory compliance; invest in detector arrays and software analytics that reduce per‑scan processing time.
- For product & operations: design modular subsystems to accelerate customization for verticals (battery, semiconductor, pharma) and embed factory automation interfaces early.
- For commercial teams: structure pilots as “value capture” tests — measurable KPIs (yield improvement, inspection speed, false‑alarm reduction) tied to procurement terms; use vendor scorecards from the report to standardize evaluations.
- For corporate development: screen targets by installed base, IP position, and vertical channel access rather than technology alone; public market exits and recent listings create definable valuation comparators.
How to use this report in your 90–180 day plan
- Run three parallel pilots (one each in manufacturing inspection, security screening and clinical diagnostics) using standardized PoC templates from the report; require suppliers to deliver measurable throughput and integration milestones.
- Execute an IP health check and regulatory gap analysis focused on ETSI/IEEE alignment and the recent EP patent landscape; use findings to prioritize licensing or R&D workstreams.
- Initiate supplier risk mitigation: create dual‑sourcing plans for critical detectors/sources and plan for regional assembly to lower geopolitical exposure.
- Set a corporate development cadence: shortlist acquisition or JV targets that close product‑to‑market gaps, and validate value creation via modelled revenue ramps and margin bridges provided in the report.
PW Consulting’s full Terahertz Technology Market report contains the segmented tables, regional and application breakdowns, vendor financial benchmarks, and scorecards necessary to execute the 90–180 day plan described above. This briefing highlights the strategic contours and operational imperatives; the report itself provides the granular datasets, scenario models, and procurement artifacts required to convert 2026’s market momentum into defensible, revenue‑generating programs. For teams evaluating THz investments, the single most valuable next step is to combine the report’s ROI toolkits with a short, funded pilot that explicitly tests commercialization assumptions under a standards‑compliant scope.
For detailed analysis of this topic, please visit the official page: Terahertz (THz) Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Optics Market to Reach USD 15,227.7M by 2032 at 6.86% CAGR
By pmarketresearch, 2026-07-30
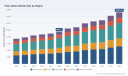
Fiber Optics Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive primer — why this study matters in 2026
The fiber optics industry has moved from incremental utility to strategic infrastructure. Our PW Consulting analysis positions the global market as a multi‑billion dollar growth opportunity with a compound annual growth rate (CAGR) of 6.86% through the 2026–2032 forecast window. After steady expansion during 2020–2025, the base‑year market (2025) is reported at USD 9,567.7 Million and is projected to climb meaningfully over the next several years. For executives planning CAPEX, sourcing, R&D, or M&A in 2026, the timing to translate directional trends into concrete decisions is now: the market is large, growing, and being reshaped by concentrated technology demand, supply‑side stressors, and policy action.
Fiber Optics Market
What this report delivers — practical, decision‑grade outputs
- Clear top‑line trajectory and scenario models: Time‑series demand and revenue models covering 2020–2032, with three stress‑tested scenarios that map different AI, broadband, and industrial adoption curves against price and capacity shocks.
- Executive dashboards and playbooks: Actionable dashboards for boardroom briefings and a set of playbooks (sourcing, localization, vertical integration, and strategic partnerships) tailored for OEMs, cable manufacturers, hyperscalers, and telecom operators.
- Vendor and technology scorecards: Standardized criteria to evaluate suppliers across performance (fiber type and loss characteristics), manufacturing footprint, contractual flexibility, and geopolitical risk exposure.
- Supply‑chain risk maps and mitigations: Identification of single‑point dependencies (materials, components, and equipment), lead time scenarios, and practical hedging strategies—spanning contractual levers, inventory policy, and dual‑sourcing templates.
- Capital planning templates: CAPEX/OPEX overlays tied to network architectures (centralized vs. distributed), total cost of ownership (TCO) calculators, and payback analyses for fiber upgrades, replacement cycles, and co‑packaged optics investments.
- Regulatory & funding trackers: A living summary of major public funding programs and regulatory changes that affect deployment economics and procurement rules across major markets.
Core dynamics that should drive your 2026 choices
Several interconnected forces are steering the industry’s commercial logic in 2026. These are not abstract trends—each alters supplier economics, contract design, and technology roadmaps.
Fiber Optics Market
- Demand concentration in AI and hyperscale networking: Rapid densification of data center interconnects and co‑packaged optics initiatives are creating high‑intensity pockets of demand that differ materially from traditional telco and FTTH needs. Buyers must design procurement strategies that reconcile very different lifecycle and performance requirements.
- Policy and public funding acceleration: Large‑scale broadband and infrastructure programs continue to catalyze national deployment initiatives and influence where manufacturers and integrators allocate capacity and capital.
- Raw‑material and supply sensitivities: The upstream supply chain—particularly specialty dopants and preform materials—has become a strategic choke point. Recent months have seen notable price volatility and capacity rebalancing; companies without hedging or validated secondary sources face margin and delivery risks.
- Manufacturing reshoring and capacity expansion: Responding to hyperscaler demand and sovereign supply concerns, significant new capacity is being added in target markets. This alters lead times and cost curves for regional buyers but also intensifies competition for skilled labor and specialized equipment.
- Technology modularization: Multicore fibers, micro‑cables, and connector innovations are shifting cost/performance tradeoffs. Standards and MSAs for multicore designs are forming rapidly—early participation in these industry consortia can shape interoperable ecosystems and create supplier advantage.
Competitive landscape — strategic takes on leading players
The market combines global incumbents with regional specialists. The competitive field is characterized by deep technological capabilities, global manufacturing footprints, and an acceleration of strategic partnerships. Our sector analysis in the report synthesizes public disclosures, product roadmaps, and partnership announcements to produce a comparative, decision‑oriented view.
Fiber Optics Market
- Corning Incorporated: The incumbent technology leader—recognized for scale in single‑mode and advanced multicore solutions—has repositioned manufacturing and supply to serve hyperscale AI customers and is rapidly commercializing higher‑density optics and connector ecosystems. Recent product launches and supply agreements underscore a strategy of integrated system provision for data centers.
- Sumitomo Electric: Focused on ultra‑low‑loss fibers and end‑to‑end interconnect solutions, Sumitomo’s technical leadership in long‑haul and low‑attenuation fibers positions it well for capacity‑intensive network backbones and premium data center links.
- Fujikura: Active in multicore fiber standardization, Fujikura is aligned with AI‑optimized campus architectures and is leveraging consortium activity to accelerate adoption of higher‑density cabling in hyperscale environments.
- Prysmian Group and Nexans: European incumbents with strong systems capability across energy and telecom markets; their strengths lie in project execution for large infrastructure and industrial applications where end‑to‑end delivery and warranty are decision factors.
- Fitel / OFS, Sterlite, YOFC, FiberHome, CommScope, Amphenol: A cohort of specialized manufacturers and connectivity suppliers offering targeted value—whether in specialty fibers, local manufacturing scale, or high‑performance connectors. These players are often preferred by regional operators and system integrators for speed and price competitiveness.
Recent moves that change the strategic calculus
Industry collaboration and vendor commitments in early 2026 have accelerated momentum around multicore fiber standards and high‑density interconnects. Several leading suppliers have announced concerted efforts to standardize multicore architectures and to launch integrated systems aimed at AI campus densities. Such initiatives reduce integration risk for early adopters, but they also shorten windows for differentiation—firms that miss the early standards phase may find themselves dependent on commodity pricing rather than shaping specifications.
Risk scenarios — what to stress test in boardroom planning
The report provides scenario templates; here are the top strategic stress tests executives should run in 2026:
- Demand surge vs. supply constraint: Model the impact of a rapid hyperscaler procurement cycle on your supplier base and internal build schedules. Identify which contracts can scale without renegotiation and where minimum order quantities create risk.
- Material embargo or licensing restrictions: Assess the time‑to‑switch for critical dopants and preform inputs, and the cost of maintaining buffer stocks or alternative process routes.
- Price shock pass‑through: Simulate different pricing regimes for core materials and identify product lines where margins compress first; design pricing clauses and indexation strategies accordingly.
- Standards divergence: Evaluate the commercial impact if competing multicore standards gain asymmetric market acceptance, and map options for alliance, porting, or parallel qualification.
How to convert insight into action in 90–180 days
Based on our advisory engagements, successful companies follow a pragmatic, three‑track approach:
- Immediate (0–90 days): Run supplier risk audits, finalize short‑term hedging for critical inputs, and prioritize qualification of at least one secondary supplier for each high‑risk material or component.
- Medium (90–180 days): Negotiate scalable supply agreements with clear ramp profiles, invest in joint development agreements where standards are forming, and align procurement T&Cs to allow flexibility in volume and delivery.
- Organizationally: Create a cross‑functional fiber strategy cell (procurement, engineering, legal, M&A) to translate scenario outputs into contract templates, R&D priorities, and capital allocation decisions.
Why PW Consulting’s report is different
We combine a bottom‑up, transaction‑grade dataset (serial‑level production and orderbook analysis) with top‑down scenario engineering. The deliverable is designed for decision makers who need both a defensible forecast and an executable playbook: not just “what the market will be,” but “what you should do about it.” The report includes granular supplier scorecards, an operational risk atlas, and downloadable financial models aligned to the 2026 planning calendar.
Next steps — how to capture the intelligence you need
This article is a high‑precision extract. For the full suite—interactive dashboards, supplier matrices, scenario spreadsheets, and procurement playbooks—visit our report landing page. The full report contains the granular segmentation, regional and application dynamics, and vendor detailed profiles that are necessary to operationalize the strategies outlined here.
In a market where technology standards, buyer concentration, and supply fragilities are converging, timely, data‑driven choices will determine who captures value as the industry scales. PW Consulting’s Fiber Optics Market report arms leaders with the models and tools to make those choices with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Fiber Optics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com