

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
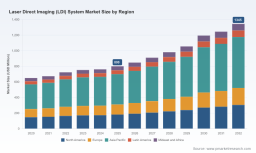
PW Consulting: LDI Systems Market to Grow at 7.8% CAGR, Reach USD 1,345M by 2032

Laser Direct Imaging (LDI) Systems Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer on the Laser Direct Imaging (LDI) systems market intended to shape boardroom decisions in 2026. Our research, anchored on a 2025 base year and a historical review spanning 2020–2025, projects a sustained expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.8%. Measured in Million USD, the market has grown from a base measured in 2020 and, with continued momentum in advanced electronics and specialty applications, is projected to reach north of USD 1.3 billion by the end of the forecast horizon. This briefing highlights the strategic inflection points, competitive dynamics, actionable recommendations, and the practical tools contained in our full report—while deliberately withholding the granular segment-level tables that enterprise teams must access via our research portal.
Laser Direct Imaging (LDI) System Market
Why LDI matters to 2026 strategic plans
- Technology convergence is accelerating. LDI is migrating from a PCB-centric enabler toward a crossroad technology used in advanced packaging, display substrates, and niche high-reliability markets (aerospace, medical). This expands addressable use cases and drives demand for higher precision, throughput, and process automation.
- Capital allocation trade-offs are becoming nuanced. Buyers and equipment OEMs face choices between retrofitting legacy exposure lines with AI-assisted alignment and vision upgrades versus greenfield investment in next-generation multi-beam or LIDE-capable platforms.
- Regulatory and quality requirements are structuring buyer behavior. Certifications and compliance frameworks (FDA 21 CFR Part 11, MDR, AS9100, ISO 13485 and comparable automotive/aerospace standards) materially increase time-to-deploy and create differentiated pricing tiers for compliant systems.
Market dynamics with strategic implications
- Measured growth, predictable runway. Our market model (base year 2025) shows steady expansion through 2032 at ~7.8% CAGR. For decision-makers, that translates into a predictable demand envelope for capacity planning, with particular read-through for capital equipment suppliers and financing arms supporting OEMs and fabs.
- Automation, vision, and AI as table stakes. In recent field deployments, a majority of new LDI installations included vision systems and auto-calibration modules to improve alignment and reduce operator dependence. Similarly, a growing share of platforms launched during 2025 incorporated AI-assisted calibration workflows, producing measurable reductions in alignment deviation. For buyers, prioritizing control software and sensing subsystems will deliver outsized operational value versus equivalent mechanical upgrades.
- Specialty end-markets command premium economics. Aerospace and healthcare customers collectively represent a meaningful premium segment within the LDI market, reflecting higher compliance and traceability requirements. Expect longer procurement cycles, greater service attach rates, and higher lifetime value per machine in these verticals.
- Product differentiation is sharpening. Demand for LIDE technologies (particularly for displays and emerging glass-substrate applications) and for flexible single-beam versus multi-beam architectures is reshaping product roadmaps. Providers that align optical performance with software-driven process control will increasingly capture higher-margin engagements.
Competitive landscape — clarity on who matters
The supplier market is moderately concentrated, with the top-tier players controlling a majority share of global revenue. This concentration creates a competitive environment where technology leadership, installed base services, and certification-compliant capabilities determine market share expansion.
Laser Direct Imaging (LDI) System Market
- Orbotech Ltd. (Israel) — Strengths: multi- and single-beam LDI platforms engineered for high-precision PCB and semiconductor workflows, coupled with integrated defect-detection. Strategic posture: leverage deep inspection and process integration to upsell software and service contracts to Tier-1 electronics manufacturers.
- Screen Holdings Co., Ltd. (South Korea) — Strengths: high-throughput multi-beam systems with advanced alignment and process automation. Strategic posture: double down on volume-driven customers where throughput and alignment accuracy are prioritized; use automation as a moat against lower-cost alternatives.
- Manz AG (Germany) — Strengths: compact, modular LDI systems and semiconductor equipment with a flexibility focus. Strategic posture: following recent divestment decisions in non-core areas, Manz is concentrating R&D and commercial efforts on LDI and advanced packaging, positioning for selective partnerships with systems integrators.
- LPKF Laser & Electronics AG (Germany) — Strengths: single-beam flexibility, LIDE technology for displays and packaging. Recent moves: reported progress in LIDE technology and flagged growing demand for AI-driven use cases and glass substrate processing. Strategic posture: exploit momentum in adjacent display and packaging markets to broaden addressable revenue and promote higher-margin application-specific systems.
- Han’s Laser Technology (China), ORC Manufacturing (Japan), Delphi Laser (China) and regional specialists — Strengths: regional manufacturing scale, cost-competitive systems, and integrated service offerings tailored to local fabs. Strategic posture: serve commoditized segments and fast-follow in select high-growth verticals; attractive partners for channel expansion and aftermarket services.
- Limata GmbH and Miva Technologies GmbH (Germany) — Strengths: energy-efficient platforms and niche substrate expertise (aerospace, medical). Strategic posture: focus on compliance-heavy niches and energy efficiency as decision levers for customers with sustainability targets.
Recent industry developments to watch
- LPKF’s product updates in 2025 and prior market statements highlight an accelerating migration of LDI into glass and AI-assisted use cases—creating adjacent revenue opportunities beyond traditional PCBs.
- Manz’s strategic refocus and selective divestments illustrate how vendors are optimizing portfolios to concentrate on higher-margin, high-growth LDI and semiconductor offerings.
- Across suppliers, there’s an observable shift toward bundling software, calibration services, and extended warranties—turning hardware sales into platform-led recurring revenue models.
What our full report delivers (operationally focused)
This briefing is an executive extract. The full PW Consulting LDI systems market study — structured for commercial teams, product strategists, and private-equity investment committees — includes:
Laser Direct Imaging (LDI) System Market
- A transparent demand model with annual market size by year (2020–2032), scenario sensitivity and downside/upside triggers calibrated to macro-electronics cycles. (Base year: 2025; forecast period: 2026–2032.)
- Supplier scorecards: capability matrices, roadmaps, and aftermarket economics to inform supplier selection and make-versus-buy decisions.
- Go-to-market playbooks for OEMs and channel partners covering pricing, service packaging, and certification pathways for aerospace/medical customers.
- CapEx and ROI calculators tailored to retrofit vs. replacement choices, including throughput and yield uplift assumptions driven by AI-assisted calibration benefits.
- Regulatory and compliance matrix, highlighting required certifications by end-market and implications for time-to-market and installed-base conversions.
- M&A and partnership heat maps that identify tactical consolidation targets and partnership archetypes by capability, geography, and customer adjacency.
Note: to preserve the strategic advantage of our clients, the report’s detailed segment-level tables and supplier-specific revenue splits are available exclusively via the full report portal. This executive extract intentionally omits granular segmentation figures to ensure commercial leverage for subscribers and clients.
Actionable recommendations for 2026 planning cycles
- For OEMs: Allocate R&D budget toward AI-assisted calibration, vision systems, and modular architectures that shorten customization cycles. Prioritize software-driven service bundles to convert one-time sales into recurring revenue.
- For PCB and packaging manufacturers: Run parallel capex pilots that compare retrofit AI-vision kits with new LDI platforms over 12–18 month windows. Build procurement clauses that capture certification deliverables (traceability, audit logs) up-front to avoid costly retrofitting for regulated customers.
- For investors: Seek targets with differentiated software stacks, high service attach rates, and an installed base in regulated end-markets. Be cautious on pure hardware plays without software or service monetization pathways.
- For service providers and system integrators: Develop certification and qualification services for aerospace and medical customers; these services can justify premium pricing and faster payback for customers upgrading equipment.
- For supply chain managers: Secure long-lead optical components and semiconductor laser sources through multi-year contracts or strategic partnerships, as localized supply disruptions can lengthen lead times and increase deployment risk.
Risk scenarios and mitigations
- Regulatory tightening. Mitigation: pre-qualify platforms against relevant standards and maintain an audit-ready documentation process.
- Rapid tech substitution. Mitigation: preserve flexibility by modularizing platforms and maintaining a balanced R&D portfolio across optics, control software, and services.
- Regional competitive pressure from low-cost suppliers. Mitigation: differentiate on service, certification, and integrated inspection capabilities—areas where price competition is less effective.
Conclusion: The LDI systems market presents a predictable growth runway with clear strategic inflection points around automation, AI-driven calibration, and regulatory specialization. In 2026, the companies and investors that translate these structural trends into product roadmaps, service strategies, and disciplined procurement will capture disproportionate value as the market scales toward the forecast horizon.
To access the full dataset, vendor scorecards, segmentation tables, and scenario models that underpin this briefing, please consult the complete PW Consulting LDI Systems Market Report on our research portal. The detailed segment-level analytics and downloadable Excel models are available to subscribers and licensed clients.
For detailed analysis of this topic, please visit the official page: Laser Direct Imaging (LDI) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com