

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: THz Market to Reach USD 994.54 Million by 2032 at 15.8% CAGR

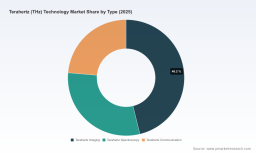
Terahertz (THz) Technology Market: A Strategic Roadmap for 2026 Decision‑Makers
This briefing frames PW Consulting’s latest Terahertz Technology Market research as an operational guide for executive teams planning investments, product roadmaps, and partnerships during 2026. Built on a 2025 base year and a granular forecast window spanning 2026–2032, the study quantifies a fast‑growing industry (CAGR 15.8%) that moved from an early commercial base a few years ago to a near‑billion dollar opportunity by the end of the forecast period. The market rose from roughly USD 205.7 million in 2020 to USD 358.5 million in 2025 and is projected to approach roughly USD 994.5 million by 2032 — framing a multi-fold expansion that materially changes strategic options for incumbents and new entrants alike.
Terahertz (THz) Technology Market
Why this report matters in 2026
- Timing: 2026 is the inflection point when lab‑grade THz capability matures into industrial and regulated applications — battery production inspection, advanced packaging inspection, and public security among them. Early movers who translate lab demonstrations into repeatable factory and clinical deployments will capture disproportionate value.
- Standards and regulatory momentum: New ETSI guidance documents (GR THz 003 and GR THz 004) and continuing IEEE activity are shifting THz from an exploratory physics domain to a standards‑driven engineering discipline. Procurement, certification, and spectrum planning decisions in 2026 must anticipate accelerating regulatory requirements.
- Capital market signals: Public market activity — including the first UK/European THz company listing on Korea’s KOSDAQ in early 2026 — validates exit routes and corporate development strategies, influencing valuation expectations for scale‑up financing and M&A.
- Competitive structure: The sector is moderately concentrated (top‑3 firms represent roughly 35% of measured market activity; top‑5 approximately 42%), leaving meaningful whitespace for differentiated technology and go‑to‑market plays.
What the report delivers (practical content)
- Transparent market sizing and a consistent forecasting methodology (2026–2032), with scenario variants and sensitivity to commercial adoption curves.
- Technology deep dives that explain trade‑offs across imaging, spectroscopy and communication approaches, including component ecosystem maps (sources, detectors, optics, electronics, and software stacks).
- Use‑case ROI toolkits and sample business cases tailored to manufacturing inspection, medical diagnostics, non‑destructive testing (NDT), and security screening.
- Vendor scorecards, procurement checklists and PoC templates designed to reduce trial‑to‑pilot cycle times and de‑risk supplier selection.
- Regulatory and standards tracker aligned to ETSI/IEEE outputs and regional compliance considerations, plus an IP and patent landscape summary to inform licensing and freedom‑to‑operate strategies.
- Corporate development playbooks — M&A screening criteria, partnership archetypes, and valuation benchmarks linked to technology maturity and revenue model.
Market dynamics and growth drivers
The market’s 15.8% CAGR is driven by three converging phenomena: maturing component technology, clarifying regulatory/std frameworks, and increasing commercial utility across high‑value verticals. Component costs and integration complexity continue to fall as silicon‑based detectors, compact THz cameras and fiber‑laser time‑domain solutions reach higher volumes. Standardization work — notably ETSI’s GR THz 003 and GR THz 004, and ongoing IEEE activity — reduces technical and procurement uncertainty, accelerating enterprise adoption.
Terahertz (THz) Technology Market
Commercially, the most visible near‑term traction is in industrial inspection (automotive coatings, battery electrode quality), semiconductor advanced packaging inspection, and targeted medical diagnostics — sectors where non‑ionizing THz imaging or spectroscopy offers unique contrast or throughput advantages. Parallel advances in scanner architectures (both active and passive), detector arrays, and integration with robotics and factory automation are turning lab demonstrations into scalable deployments.
Terahertz (THz) Technology Market
Competitive landscape — who matters and why
- TeraView Limited (Cambridge, UK) — A leader in applied THz imaging and spectroscopy focused on semiconductor packaging inspection, automotive paint/coating analysis, battery electrode production, and pharmaceutical quality control. Recent strategic moves include a KOSDAQ listing (Feb 2026) and partnerships to accelerate entrance into Korean EV battery lines and robotic inspection systems. These signal both capital access and intensified vertical go‑to‑market focus.
- TOPTICA Photonics AG (München, Germany) — Strong in terahertz time‑domain systems for spectroscopy, imaging and metrology. TOPTICA’s emphasis on laser‑source fidelity and metrology positioning makes it attractive for high‑precision lab and industrial customers looking for deterministic performance.
- Menlo Systems GmbH (Martinsried, Germany) — Offers THz time‑domain solutions built on mature fiber‑laser platforms; notable for over 300 systems deployed in field operations. Their installed base and precision orientation position them well for scientific and high‑accuracy industrial users.
- HÜBNER Photonics GmbH (Kassel, Germany) — Provides integrated THz imagers and spectrometers targeting public security and industrial inspection, with active participation in key optics and materials conferences — an indicator of pipeline momentum and research partnerships.
- TeraSense Group Inc. (Moscow, Russia) — Pioneers semiconductor‑based THz cameras, detectors and scanners. Their work on passive body scanners and compact detectors points to lower‑cost, high‑throughput deployments for security and NDT; geopolitical and supply‑chain considerations will inform regional go‑to‑market choices.
- Luna Innovations Incorporated (Roanoke, VA, USA) — Focused on industrial THz sensing (e.g., T‑Gauge solutions) with collaboration footprints in battery and materials inspection. Their industrial monitoring orientation is valuable for process control applications.
- TicWave Solutions GmbH (Germany) — Develops compact silicon‑based THz cameras and real‑time video systems; these product profiles are optimized for security screening and inline inspection integrations where throughput and form factor matter.
Recent developments to watch (early 2026)
- TeraView’s KOSDAQ listing (Feb 2026) — first UK/European THz company to list on that exchange, indicating investor appetite and a potential benchmark for future financings.
- Patent activity: Beijing Research Institute of Telemetry granted an EP patent (Apr 2026) for multimode real‑time THz imaging — a reminder that patent fences are forming around system architectures and real‑time modes.
- Partnerships and product pipelines: TeraView’s collaborations with Axbis and Doolim‑Yaskawa (May 2026) and TeraSense’s development of a passive THz body scanner (May 2026) illustrate the push to industrialize and scale vertically oriented solutions.
- Industry engagement: HÜBNER’s trade show participation and Menlo’s broad installed base underscore the sector’s transition from research showcases to revenue‑generating deployments.
Risk matrix and mitigation strategies
- Technical risk — source power, detector sensitivity and integration complexity: mitigate with modular architecture, hybrid sensor fusion, and staged PoC milestones tied to performance KPIs.
- Regulatory & standards risk — evolving ETSI/IEEE guidance can change product requirements: maintain active standards engagement and build compliance roadmaps into R&D timelines.
- IP & patent risks — growing patent activity may raise licensing needs: invest in targeted freedom‑to‑operate analyses and consider portfolio cross‑licensing as part of partnership negotiations.
- Supply chain & geopolitical risk — specialized components and regional concentration of vendors: diversify suppliers, localize assembly for key markets, and plan component lifecycles in procurement.
- Market adoption risk — proof to scale gap: use staged commercial pilots with measurable ROI thresholds and require supplier‑backed integration commitments.
Actionable priorities for 2026
- For R&D leaders: prioritize product architectures that balance cost, throughput and regulatory compliance; invest in detector arrays and software analytics that reduce per‑scan processing time.
- For product & operations: design modular subsystems to accelerate customization for verticals (battery, semiconductor, pharma) and embed factory automation interfaces early.
- For commercial teams: structure pilots as “value capture” tests — measurable KPIs (yield improvement, inspection speed, false‑alarm reduction) tied to procurement terms; use vendor scorecards from the report to standardize evaluations.
- For corporate development: screen targets by installed base, IP position, and vertical channel access rather than technology alone; public market exits and recent listings create definable valuation comparators.
How to use this report in your 90–180 day plan
- Run three parallel pilots (one each in manufacturing inspection, security screening and clinical diagnostics) using standardized PoC templates from the report; require suppliers to deliver measurable throughput and integration milestones.
- Execute an IP health check and regulatory gap analysis focused on ETSI/IEEE alignment and the recent EP patent landscape; use findings to prioritize licensing or R&D workstreams.
- Initiate supplier risk mitigation: create dual‑sourcing plans for critical detectors/sources and plan for regional assembly to lower geopolitical exposure.
- Set a corporate development cadence: shortlist acquisition or JV targets that close product‑to‑market gaps, and validate value creation via modelled revenue ramps and margin bridges provided in the report.
PW Consulting’s full Terahertz Technology Market report contains the segmented tables, regional and application breakdowns, vendor financial benchmarks, and scorecards necessary to execute the 90–180 day plan described above. This briefing highlights the strategic contours and operational imperatives; the report itself provides the granular datasets, scenario models, and procurement artifacts required to convert 2026’s market momentum into defensible, revenue‑generating programs. For teams evaluating THz investments, the single most valuable next step is to combine the report’s ROI toolkits with a short, funded pilot that explicitly tests commercialization assumptions under a standards‑compliant scope.
For detailed analysis of this topic, please visit the official page: Terahertz (THz) Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com