

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silage Films Market Poised for 4.82% CAGR (2026–2032)

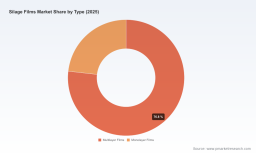
Silage Films Market — Strategic Imperatives for 2026 Decision‑Makers
As the global agricultural value chain navigates tighter environmental regulation, material-cost volatility and evolving on‑farm preservation practices, silage films have moved from a tactical procurement item to a strategic lever for feed quality, waste reduction and ESG compliance. PW Consulting’s latest Silage Films Market study (base year 2025) synthesizes five years of historical dynamics and a forward-looking forecast across 2026–2032 to deliver the actionable intelligence executives need to set winning 2026 priorities.
Silage Films Market
Executive snapshot: what this research enables
-
Clarity on market scale and trajectory: the silage films market has expanded steadily in the first half of the decade and is modelled to continue growing at a mid-single-digit compound annual growth rate through the forecast horizon. This projection frames realistic demand scenarios for procurement, production planning and investment gating decisions.
Silage Films Market -
Competitive positioning for buyers and suppliers: our study decodes the strategic moves of global incumbents and agile challengers — from product innovation to channel plays — enabling procurement teams to evaluate total cost of ownership rather than price per roll.
Silage Films Market -
Regulatory and standards impact: the analysis translates forthcoming standards and regionally accelerating plastic‑use policies into quantified implications for product specification, cost curves and substitution pathways.
-
Practical toolset for 2026 execution: templates, scenario models and a procurement playbook included in the report accelerate decision cycles and reduce implementation risk.
Market trajectory and what it means for corporate strategy
Between 2020 and 2025 the market recorded steady expansion as feed preservation practices intensified and multi‑layer film adoption increased. By the base year the market had grown materially compared with the start of the decade; our modelling projects continued growth through 2032 at a compounded annual growth rate of 4.82% for the forecast period 2026–2032, with total market value approaching the mid‑single‑digit million USD range by 2032. For industrial players this pace of growth signals predictable base demand, but the strategic value accrues to those that capture improved margins through product differentiation, waste-reduction features, and integrated service offers (e.g., collection and recycling partnerships).
Three commercial implications stand out:
-
Margin pressure will shift from pure price competition to performance economics. Buyers increasingly measure film value by silage loss reduction, labor savings and end‑of‑life handling costs. Suppliers that can demonstrate lower net cost per tonne of preserved forage will command premium positions.
-
Innovation in layer architecture and barrier technologies is the primary path to differentiation. Recent product introductions show suppliers trading thickness for barrier performance and recyclability features; these trade-offs will determine technical winners as standards and buyer expectations evolve.
-
Supply chain resilience matters. Raw material feedstock and film‑line capacity constraints create timing risk for large contracts. Contract design, inventory strategy and flexible manufacturing footprints will be decisive for both suppliers and large agricultural cooperatives.
Competitive landscape: incumbents, specialisms and strategic moves
The silage films market is neither monopolistic nor atomized — concentration metrics show a market where a handful of global players exert significant influence but meaningful share remains distributed among regional specialists and innovative challengers. This structure creates opportunities for selective consolidation, targeted partnerships and differentiated niche plays.
-
Rani Plast (Finland) — recognized for very wide, high‑performance multi‑layer films tailored to bunker and large bale applications. Their engineering focus and scale in specialized extrusion give them advantage in large‑format contracts.
-
Coveris (Austria) — a premium film producer with a history of innovation in stretch and oxygen‑barrier films; their branded solutions target operators seeking performance assurance and traceability.
-
Berry Global Inc. (United States) — a leading supplier with portfolio breadth, including multi‑layer film systems designed to reduce on‑farm losses through integrated Film&Film combinations and channel reach in major agricultural markets.
-
RKW Group (Germany) — specializes in polyolefin-based films and nets; their strength lies in industrial production consistency and established distribution in European markets.
-
Trioworld (Sweden) — positioned around sustainability claims and alternatives, offering products that emphasize reduced environmental footprint and higher oxygen permeability where appropriate.
-
Polifilm (Germany) — notable for co‑extruded silage films with manufacturing flexibility and product formats designed for grass and maize handling nuances.
-
Lallemand Animal Nutrition (Canada) — an important product innovator in oxygen‑barrier films; their OxyBlock range has reshaped discussions about performance trade‑offs between barrier technology and material usage.
Recent competitive activity underscores the priority suppliers place on barrier technology and multi‑layer architectures. A notable product launch in early 2026 introduced oxygen‑barrier variants that blend EVOH layers with multi‑layer extrusion designs; this demonstrates how performance-led launches can raise the specification floor for premium forage preservation.
Regulatory and standards shift: what to watch and how to respond
Regulation and standards are no longer background noise — they are key decision inputs. The introduction of new certification requirements for thermoplastic silage films has already raised the technical minimums suppliers must meet to compete in several major markets; compliance will influence product roadmaps and capital spend on line upgrades. Meanwhile, an accelerating policy momentum across several jurisdictions signals tighter limits on single‑use plastics and higher expectations for recyclability and take‑back programs.
For corporate decision‑makers, the immediate priorities are clear:
-
Integrate standards and regulatory scenarios into procurement contracts so that specifications can evolve without frequent price renegotiations.
-
Assess capital exposure to retool or qualify suppliers under updated certification regimes and build contingency sourcing options.
-
Develop circularity pilots that reduce end‑of‑life risk exposure and create differentiation—collection logistics and chemical recycling or compound‑recover options are increasingly commercially viable.
What the PW Consulting report packs (practical, executable sections)
This study is designed as an execution toolkit for senior leaders and functional teams. Highlights include:
-
Robust market sizing and demand-driver narrative that links agriculture macrotrends to film consumption dynamics (detailed annual baseline and forecast by global market, with scenario variance and sensitivity to feedstock price paths).
-
Competitive capability matrix and vendor dossiers that map product portfolios, manufacturing footprints, R&D focus and channel strategies for the major players — enabling faster supplier pre‑qualification.
-
Procurement playbook: RFP templates, scoring matrices weighted for performance economics, contract clauses for regulatory compliance and escalation, and inventory hedging strategies.
-
Product economics models: thickness vs. barrier trade‑offs, net cost per tonne preserved forage, and a capex vs. margin ladder for line upgrades to meet higher layer or barrier requirements.
-
Regulatory impact assessment and a policy-to-product roadmap that translates standards into technical requirements and cost implications.
-
M&A and partnership screen: acquisition targets and JV criteria for buyers seeking upstream control or technical capability in barrier technologies and recycling.
-
Implementation case studies and a 100‑day action plan for farm cooperatives, processors and film manufacturers.
How to use this intelligence in 2026 planning cycles
Executives should treat the report as both situational intelligence and an operating playbook. Recommended use cases include:
-
Capital allocation: use the report’s capex sensitivity and demand scenarios to prioritize extrusion-line upgrades, new barrier layer investments or recycling systems.
-
Procurement transformation: adopt the procurement templates and TCO models to transition from price‑only selection to performance‑based contracting.
-
Product strategy: align R&D roadmaps to the technical minimums implied by new standards and to the growing buyer preference for reduced‑loss, lower‑waste solutions.
-
M&A screening: focus on targets that add distinct technical IP (e.g., EVOH barrier integration), regional logistics advantages or circularity competence to accelerate differentiation.
Final note — why this is a “must‑read” before you sign any 2026 contracts
The headline market growth is not the story by itself; the competitive economics of silage films in 2026 will be determined by who can convert barrier performance and circularity into verifiable, farm‑level outcomes. Our study provides the framework and tools to do that conversion — but, in keeping with the “trailer” principle, this public summary intentionally omits the granular segmentation and granular regional breakdowns that buyers and investors need for contract negotiation and investment due diligence.
For the full dataset, supplier scorecards, granular scenario tables and the operational playbooks that support immediate 2026 actions, access the complete PW Consulting Silage Films Market report. The detailed annexes contain the fine‑grained splits, certification‑aligned specifications and supplier benchmarking that will materially shorten your path from insight to implemented advantage.
For detailed analysis of this topic, please visit the official page: Silage Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com