

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dye-Sensitized Solar Cell Market: 12.44% CAGR to USD 378.76 Million by 2032 - PW Consulting

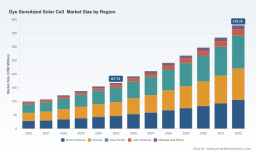
Dye‑Sensitized Solar Cell Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Chief Industry Analyst and lead author of our latest Dye‑Sensitized Solar Cell (DSSC) Market study, I present a focused, actionable briefing to orient executive decisions in 2026. This market is at the confluence of material science innovation, building electrification, and the proliferation of connected devices — a rare intersection where small‑form factor photovoltaic modules can create outsized strategic advantage. Our research (base year 2025) synthesizes historical performance (2020–2025) with a rigorous forecast (2026–2032) to deliver a decision‑grade view of where investment, product development, and partnerships will create value.
Dye Sensitized Solar Cell Market
Why this research matters in 2026
-
Capital allocation: Distinguish between scalable product bets (e.g., BIPV, flexible modules) and niche pilots that require prolonged subsidy support.
Dye Sensitized Solar Cell Market -
Go‑to‑market timing: Use our near‑term market trajectory to optimize launch windows and pilot rollouts when procurement cycles in construction and IoT accelerate.
Dye Sensitized Solar Cell Market -
Supply chain prioritization: Identify which materials and sub‑components to secure now to avoid bottle‑necks during scale‑up.
-
M&A and partnership screening: Evaluate targets and partners with an evidence‑based view of market concentration, capability gaps, and technology differentiators.
-
Regulatory & standards readiness: Map product certifications and recycling obligations against anticipated policy shifts to reduce go‑to‑market friction.
Snapshot: market trajectory and what it implies
Our top‑line market sizing shows a clear growth story. The DSSC market expanded from a modest commercial base in 2020 and reached a material scale by the 2025 base year. Under our central forecast, the market continues to expand rapidly, reflecting strong adoption across indoor ambient harvesting, building‑integrated applications, and lightweight portable uses. The forecast period (2026–2032) is modelled with a compound annual growth rate of 12.44%, driving the market materially higher by the end of the horizon.
For executives, two implications follow immediately: first, the window for establishing meaningful share with differentiated products is narrow but real; second, companies that delay technology de‑risking and supply alignment risk becoming price takers as manufacturing and distribution scale.
What the PW Consulting report delivers — practical, transaction‑ready outputs
The report is designed for executives who need to act. It combines quantitative market architecture with hands‑on playbooks and decision frameworks:
-
Market sizing and methodology: Transparent assumptions, sensitivity scenarios, and clear delineation between end‑use demand, module shipments, and revenue streams.
-
Scenario modelling: Stress‑tested growth paths under conservative, central, and aggressive adoption cases to support capex and portfolio decisions.
-
Technology roadmaps: Comparative analysis of solid‑state vs liquid electrolyte approaches, dye chemistries (organic vs metal‑based), and encapsulation strategies tied to performance and lifetime trade‑offs.
-
Cost‑curve and manufacturing playbook: Unit cost breakdowns, scale thresholds, and recommended process investments to reach target margins at volume.
-
Commercial pilots and BIPV business cases: Ready‑to‑use templates for construct‑industry partners, LCOE estimates, and sample procurement specifications.
-
Supply‑chain stress tests & sourcing playbook: Prioritised sourcing actions for dyes, electrolytes, TiO2 and encapsulation materials plus contract templates for offtake and tolling.
-
Competitive benchmarking and M&A candidate shortlists: Profiles and capability gaps for incumbent and emerging players, with acquisition rationales and integration risks.
-
Regulatory mapping & recycling pathways: Jurisdictional impacts on product design, end‑of‑life logistics, and potential circularity commercial models.
Note: The report contains the full, detailed segmentation tables and region/application breakdowns necessary for tactical planning. This briefing intentionally omits those granular tables to preserve the primary value of the full dataset available in the published report.
Competitive landscape — who matters and why
The DSSC ecosystem today is comprised of specialized module manufacturers, chemistry innovators, and system integrators. Market concentration is moderate: the top three firms account for a meaningful share of commercial deployments, and the top five increase that share further — an important backdrop for partnership and pricing strategies.
-
Ricoh Company, Ltd. (Tokyo) : Ricoh’s focus on solid‑state DSSC modules optimized for indoor and ambient light positions it as a prime partner for IoT OEMs and smart‑space integrators. Their work on low‑lux performance and compact modules makes Ricoh a benchmark for indoor energy autonomy.
-
Solaronix SA (Aubonne) : Solaronix’s strength lies in high‑performance modules and chemistry (including ionic liquid electrolytes). Their recent strategic moves around organic dye synthesis (see developments) signal an intent to control more of the value chain and accelerate metal‑free dye options for large scale manufacturing.
-
G24 Power Ltd. (New South Wales) : G24’s GCell brand exemplifies commercial success in flexible, lightweight and semi‑transparent modules—attributes critical for BIPV and novel form factors.
Recent industry developments highlight the accelerating pace of commercialization: advanced encapsulation technologies, targeted acquisitions to secure dye pipelines, and construction industry partnerships to integrate DSSC into building envelopes. Each event reshapes the competitive calculus: durability and integration capability are quickly becoming as important as nominal cell efficiency.
Supply‑chain and raw material dynamics
The production economics of DSSC are governed by a small set of materials and component choices. Dye chemistry, electrolytes, and the semiconductor scaffold (commonly TiO2) are persistent cost drivers. Two material themes deserve executive attention in 2026:
-
Organic dyes versus ruthenium complexes: Organic formulations present a clear route to cost reduction and supply diversification, but require investment in synthesis scale‑up and stability enhancement.
-
Encapsulation and longevity: Advances such as laser‑assisted hermetic encapsulation materially improve lifetime and reduce balance‑of‑system costs; companies that internalize or secure these technologies will lower total ownership costs for their customers.
Procurement strategies should therefore prioritize long‑lead chemistry supplies, multi‑source electrolytes, and partnership agreements with encapsulation specialists to avoid costly rework after pilot deployments.
Policy, standards and integration opportunities
Public programs and standards are increasingly favorable to DSSC adoption in built environments. European initiatives that sponsored smart glass integration and subsequent policy analyses highlight two durable tailwinds: (1) regulatory encouragement for energy‑generating façades and (2) early support for recycling and material recovery frameworks. These policy levers lower adoption friction in construction and public procurement and are likely to create first‑mover advantages for suppliers aligned with recyclability and certification pathways.
Decision playbook for 2026 — prioritized actions
-
Immediate (0–6 months) : Commission a focused proof‑of‑concept with a BIPV or IoT partner using a solid‑state module; secure conditional supply agreements for critical dyes and electrolytes; audit IP exposure and freedom‑to‑operate for target chemistries.
-
Near term (6–18 months) : Execute a pilot that validates lifecycle metrics (degradation, encapsulation performance) and builds reference projects; initiate partnerships with construction firms or building product distributors; evaluate targeted acquisitions or licensing deals for dye synthesis capability.
-
Medium term (18–36 months) : Scale manufacturing to reach cost thresholds defined in the report’s cost curve, deploy standardized module SKUs, and close multi‑year offtake contracts with system integrators.
Closing: how to use this briefing
This briefing synthesizes the strategic conclusions of PW Consulting’s full DSSC Market study and outlines the actions most likely to create value in 2026. For teams making capital, product, or M&A decisions, the full report provides the granular segmentation tables, regional and application breakouts, supplier scorecards, and financial models necessary for transaction execution. Reach out to PW Consulting to access the complete dataset, tailored scenario modelling, and advisory support to convert this market growth into firm value.
For detailed analysis of this topic, please visit the official page: Dye Sensitized Solar Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com