

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Li-ion Ternary Precursor Market to Grow at 9.5% CAGR through 2032 | PW Consulting

Li‑ion Battery Ternary Precursor Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As battery supply chains rewire around electrification, energy storage and regulatory imperatives, the global market for ternary precursors (NMC/NCA hydroxide precursors) has moved from niche commodity to strategic raw material. PW Consulting’s new market research (base year 2025; historical window 2020–2025; forecast 2026–2032) models this transition with a 9.5% compound annual growth rate across the forecast period and a clearly accelerating revenue profile beginning 2026. For corporate leaders who must set sourcing, capacity and partnership decisions in 2026, this briefing distills the implications our full study surfaces — while deliberately omitting the granular regional and application splits that are available only in the full report.
Li-ion Battery Ternary Precursor Market
Why this matters for 2026 strategy
- Timing of capacity decisions: 2026 is the inflection year where demand visibility, capex lead times and supply‑chain reconfiguration converge. Manufacturers who finalize investment plans in 2026 will be executing into a market materially larger than the 2025 baseline.
- Procurement and raw material risk: Price volatility (including recent movements in precursor and nickel feedstock pricing) is compressing margins for some producers and creating windows for secured‑volume strategies.
- Regulatory compliance and circularity: Rising traceability and recycling requirements are shifting supplier evaluation criteria from price alone to provenance, CO2 footprint and recycling integration.
- Competitive intensity and concentration: The market exhibits moderate concentration (CR3 and CR5 metrics indicate room for scale players to influence flows, while also leaving niches for specialized entrants).
Market trajectory — what the top‑line numbers tell you
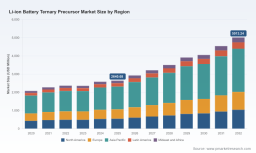
PW Consulting’s topline modelling shows a sustained expansion from the 2025 base toward a substantially larger market by the end of the 2026–2032 forecast window, driven by EV penetration, stationary storage deployments and higher nickel content recipes in cathode chemistries. A single percentage CAGR masks structural shifts beneath: a rising share of high‑nickel chemistries, differentiated requirements between power and consumer applications, and a growing role for recycled feedstocks. Taken together, the headline 9.5% CAGR is best interpreted as demand growth plus compositional change — not uniform price expansion.
Li-ion Battery Ternary Precursor Market
Immediate signals to act on in 2026
- Secure feedstock chains now: Upstream nickel and precursor pricing dynamics have shown short cycles of disruption. For example, recent market reports note a measured uptick in precursor NCM811 pricing (reported at about 12.03 RMB/kg with modest month‑on‑month movement) while nickel sulfate costs eased slightly (reported near 9.48 RMB/kg). These movements create windows to renegotiate contracts or lock in fixed volumes.
- Prioritize traceable, recyclable supply: Regulatory developments such as the EU Battery Regulation are increasing the compliance burden for suppliers and OEMs. Buyers that can demonstrate traceability and recycling integration will minimize regulatory risk and extract premium access to certain markets.
- Differentiate by product portfolio and technical capability: High‑nickel precursors and single‑crystal offerings are increasingly rewarded in power applications. Evaluate suppliers not just on capacity but on capability to supply high‑Ni grades with consistent quality.
- Plan for strategic stockpiling but avoid stranded inventory: Policy stimuli (notably past subsidies and incentive programs) have previously prompted stockpiling behaviour. In 2026, companies should balance buffer inventory for continuity with flexible contracts to avoid exposure to rapid chemistry shifts.
What our full report delivers (practical, transaction‑ready insights)
PW Consulting’s Li‑ion Battery Ternary Precursor Market study is built for executives who need actionable intelligence rather than descriptive narrative. The full deliverable includes:
Li-ion Battery Ternary Precursor Market
- Market sizing and model logic (2020–2032) with sensitivity scenarios tied to EV adoption, grid storage rollouts and high‑Ni chemistry penetration.
- Demand drivers and elasticity analysis — segmented by application archetypes and product type — with the modelling assumptions fully auditable.
- Supply‑side mapping: plant locations, capacity build‑outs, feedstock linkages and technology differentiators (sintered vs. hydroxide, single‑crystal process steps, recycled precursor streams).
- Cost stacks and margin curve benchmarking under multiple feedstock price scenarios to inform pricing, hedging and procurement strategies.
- Regulatory and trade overlays — including traceability requirements, recycling quotas and subsidy regimes — with compliance roadmaps per major jurisdiction.
- Deal support: M&A screening, JV partner scorecards and an acquisition valuation framework calibrated to precursor market dynamics.
- An interactive dashboard that lets users re‑run the forecast under custom inputs (chemistry mix, regional demand ramps, feedstock inflation), enabling rapid scenario testing for board presentations.
Competitive landscape — what to watch among active players
The precursor supplier set includes incumbent scale producers, specialized technology firms and recycling‑focused entrants. Competitive posture matters: a supplier’s ability to offer integrated recycling, feedstock security or differentiated high‑nickel grades is increasingly decisive.
- GEM Co., Ltd (Shenzhen, China) — A vertically integrated player combining precursor production with recycling and nickel resource projects. Strategic partnerships and capital markets moves (including recent H‑share listing activity and collaboration with major battery manufacturers) position GEM to compete on both scale and circularity.
- CNGR Advanced Material Co., Ltd (Tongren, China) — Broad product lineup covering common ternary formulations and higher‑nickel variants. CNGR’s refreshed catalog and product development emphasize responsiveness to EV power battery requirements.
- Zhejiang Huayou Cobalt — Known for high‑performance power battery precursors and an emphasis on high‑nickel materials; strong upstream positions in cobalt and cobalt processing support integrated value propositions.
- Umicore (Brussels, Belgium) — European incumbent with strengths in closed‑loop recycling and sustainability credentials; well‑placed to serve OEMs prioritizing compliance and lifecycle performance.
- Ascend Elements (United States) — An emerging differentiator through recycled hydroxide precursors and cathode material production; recent product launches underline commercial maturity in recycled NMC grades for EV, defense and grid markets.
- Regional specialists (Tanaka Chemical, Ronbay, Greatpower, Kelong, Fangyuan) — A mix of high‑purity suppliers and high‑nickel innovators serving national champions and regional OEM clusters. These firms often compete on technical quality, speed to qualification and cost efficiency for local customers.
Recent developments underscore strategic trends: partnership deals to build recycling networks, product catalog expansions into high‑nickel grades, and new recycled precursor product launches. These moves illustrate a two‑track competition — scale and integration versus technical differentiation.
Strategic playbook for 2026
- Supply security first: Negotiate multi‑year offtakes with performance clauses tied to chemistry mix. For OEMs, prioritize suppliers offering both feedstock transparency and recycling pathways.
- Capex discipline: For producers, prioritize brownfield expansions and modular capacity that can be reconfigured for different grades; defer large greenfield spend until offtake commitments are secured.
- Regulatory arbitrage: Map regulatory timelines across commercial markets and align production or recycling investments to jurisdictions where compliance premiums are largest.
- M&A and partnering: Target assets that add either feedstock security (mines, hydromet capabilities) or recycling and refining that shorten the loop from scrap to precursor. Use earnouts to bridge valuation gaps given chemistry evolution risk.
- Product strategy: Invest in R&D for high‑nickel process controls and single‑crystal technologies where performance gains translate to higher value capture.
Reading the noise — practical risk adjustments
Industry headlines will continue to create short windows of volatility: raw material price blips, policy announcements and regional subsidy changes. Translate these into portfolio actions: adjust hedges for nickel feedstock exposures, tier supplier pools by compliance readiness, and maintain scenario playbooks that include accelerated EV adoption, delayed recycling rollouts, and rapid chemistry substitution.
How to use this research in your 2026 planning cycle
- Board level: Use the scenario dashboard to validate growth assumptions embedded in strategy documents and to stress‑test capex timelines against downside chemistry scenarios.
- Commercial teams: Recalibrate procurement KPIs to include traceability, recycled content and qualification timelines; use supplier scorecards from the report to prioritize negotiation targets.
- Corporate development: Screen acquisition targets using the report’s valuation framework and CR indexes to identify scale gaps and strategic niches.
- R&D and operations: Align product roadmaps to the high‑value chemistries and quality attributes the report surfaces, and use the cost stack analysis to guide process improvements.
Concluding note — why PW Consulting’s study is decision‑ready
Our market study combines a transparent, auditable forecast model, supplier‑level commercial intelligence and regulatory overlays designed for transaction use. It converts the macro picture — a market expanding at ~9.5% CAGR from 2026 onward — into operational choices: who to partner with, where to site capacity, how to structure contracts and which product bets to back.
This briefing intentionally highlights strategic findings while withholding full granular splits (regional, application and specific segment financials) to preserve the report’s role as your operational playbook. For executive teams preparing 2026 budgets and multi‑year strategic plans, accessing the full dataset and interactive tools is the logical next step.
Next step
Access the full PW Consulting Li‑ion Battery Ternary Precursor Market report to unlock the detailed regional and application breakdowns, supplier scorecards, interactive scenario tools and transaction playbooks that support binding 2026 decisions.
For detailed analysis of this topic, please visit the official page: Li-ion Battery Ternary Precursor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com