

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: 4,4‑Biphenol Market to Reach USD 258.5M by 2032 at 7.23% CAGR
By pmarketresearch, 2026-07-30
4,4'-Biphenol Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
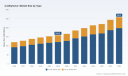
As 2026 begins, the global 4,4'-Biphenol market stands at an inflection point. Our PW Consulting base-year assessment (2025) and multi-year model show a market that has expanded from approximately USD 120.5 Million in 2020 to USD 158.6 Million in 2025, and that is forecast to continue growing at a compound annual growth rate (CAGR) of 7.23% through 2032, reaching roughly USD 258.5 Million by the end of the projection window. These headline metrics capture both steady end-market adoption and the structural shifts in polymer demand, regulatory visibility, and supplier consolidation that will determine winners and losers in the coming three to five years.
4,4-Biphenol Market
Why this preview matters for 2026 strategy
-
Timing investments: A mid-single-digit to low-double-digit CAGR across 2026–2032 signals predictable volume growth but with pockets of higher volatility tied to advanced polymers (e.g., liquid crystal polymers, high-performance polysulfones). Buyers, producers and investors must align capital deployment to capture specific application upcycles rather than betting on uniform expansion.
4,4-Biphenol Market -
Margin management: As demand matures, pricing will be driven more by purity grade differentials, batch reliability, and service levels than by feedstock swings alone. Companies with validated high-purity manufacturing and robust quality systems will preserve premium positioning; newcomers should assess margin dilution risk from commoditization before scaling.
4,4-Biphenol Market -
Regulatory and supply certainty: Emerging regulatory scrutiny and evolving trade classifications make proactive compliance and tariff-aware sourcing a strategic imperative. The market’s growth trajectory provides opportunity, but unmanaged regulatory exposure can erode returns and time-to-market.
What our full study delivers — practical, transaction-ready intelligence
PW Consulting’s 4,4'-Biphenol market study is deliberately operational: it is built for commercial teams, M&A advisors, and strategic planners who must make decisive commitments in 2026. Highlights include:
-
A transparent demand model spanning 2020–2032 with unit demand drivers by polymer family, manufacturer-level capacity overlays, and a price-quantity matrix calibrated to historical trade flows.
-
Scenario-based forecasts that stress-test outcomes under differing regulatory treatments, raw-material shocks, and accelerated electronic-vehicle/medical device adoption.
-
An investment diagnostic for capacity expansion or debottlenecking: NPV sensitivity tables, payback intervals at alternative purity-premia, and capital-efficiency benchmarks drawn from recent project disclosures.
-
Commercial playbooks for suppliers and buyers — including contracting templates that address purity, traceability, and transport classification risks — and an action checklist for due-diligence in supplier audits and JV negotiations.
-
A red-team risk register covering environmental, health, and trade implications: regulatory watch-items, likely enforcement scenarios, and practical mitigation steps for 12–36 month horizons.
Note: this preview intentionally omits granular segmentation tables and specific regional/application dollar splits to preserve the report’s subscriber value. The full report contains the detailed split information and supplier-level data that commercial teams require for closed-loop decision-making.
Market structure and competition — what matters in 2026
The 4,4'-Biphenol market is moderately concentrated. Our concentration metrics indicate that the top three suppliers account for a significant majority of market volume, and the top five expand that share further. This concentration creates a market where strategic moves by a few players can rapidly reshape access, price dynamics, and contractual norms.
Key incumbent profiles we analyze in depth include:
-
Chimei Plastic (Taiwan) — An established producer of high-purity 4,4'-Biphenol positioned as a plastic and rubber additive and polymer precursor. Their strengths are scale and established commercial relationships in adjacent polymer value chains. (Product link available in the full report.)
-
Honshu Chemical Industry Co., Ltd. (Japan) — Focused on monomers for liquid crystal polymers and high-performance polysulfone families, Honshu is notable for its technology alignment to electronics, telecoms and medical device OEMs.
-
SII Group (Japan) — Supplies 4,4'-Biphenol to several engineering-plastics value chains including LCPs and polyarylether ketones. Their product strategy emphasizes functional monomers and collaborative R&D with downstream compounders.
-
Ascent Petrochem Holdings (China) — An industrial-scale manufacturer with ISO 9001 compliance and availability of 99%+ purity grades. They represent the capacity-led segment that competes on price and availability for large polymer makers.
-
Anhui Liwei Chemical (China) — A certified factory with batch traceability and strict quality protocols, serving polymer producers that require documented material provenance and auditability.
Strategic takeaway: incumbents combine scale, geographic reach and product-grade depth. New entrants should not expect to win on price alone; targeted partnerships with end-users, niche purity differentiation, or licensing of synthesis routes will be necessary to secure enterable niches.
Regulatory dynamics and near-term policy risk
Policy developments through 2024–2026 show a mix of increased visibility without sweeping new bans — an environment of “watch and adjust.” The report highlights several regulatory factors that merit active monitoring:
-
U.S. TSCA listings include 4,4'-Biphenol among substances subject to persistent monitoring discussions, particularly under PBT considerations. While no targeted U.S. federal restrictions took effect through early 2026, prospective assessments could alter compliance costs for certain suppliers.
-
Trade treatment is supportive in some jurisdictions: relevant tariff schedules for certain chemical classifications show duty-free treatment at the time of publication, which lowers an important cost barrier for cross-border commercial strategies.
-
Food-contact and medical-device pathways: 4,4'-Biphenol appears in Food Contact Substance notifications as a monomer in specific copolymers, and several high-performance polymer applications maintain visibility with regulatory bodies. These approvals open premium, regulated end-markets but require depth in compliance and traceability documentation.
-
Transport and safety data sheets (SDS) continue to list standard GHS classifications and R&D-use-notes in some jurisdictions. Companies scaling to larger batches must ensure supply-chain safety data coherence to avoid shipment delays and customs friction.
Implication for 2026: regulatory tracking should be embedded in commercial planning. Even absent immediate bans, incremental reporting, testing, or labeling requirements can increase product cost-in-use and contract complexity.
Commercial strategies that our clients are executing
-
Securing offtake agreements with purity-linked price ladders. Firms are negotiating contracts that mirror polymer conversion economics rather than simple spot pricing.
-
Vertical collaboration: manufacturers are co-investing with compounders and OEMs to validate downstream performance and accelerate qualification cycles for LCP and medical-grade polymers.
-
Manufacturing resilience: selective capacity expansions are paired with process intensification to preserve margins while meeting quality specifications, avoiding overexposure to commodity pricing pressures.
-
Regulatory arbitrage and sourcing optimization: procurement teams are diversifying supplier lists across tariff regimes and maintaining documented compliance dossiers to streamline cross-border movements.
How to use this preview in boardroom decisions
For CFOs evaluating capital allocation, the clear growth path at a 7.23% CAGR justifies staged investments with go/no-go gates tied to purity-premium realization and secured offtake. For Chief Commercial Officers, the consolidation metrics indicate that access to a top-tier supplier or a strategic alliance can be a force-multiplier. For R&D and product teams, the uptick in regulated end-uses implies that upstream quality controls and traceability will be de facto market entry barriers for higher-value polymer applications.
Next steps — where PW Consulting adds value
-
Request the full report to access proprietary segmentation, supplier-level volume and pricing matrices, and the scenario tool that quantifies NPV outcomes under alternative regulatory and demand pathways.
-
Commission a tailored rapid due-diligence: we can map a target supplier’s operational, regulatory and commercial fit to your specific polymer conversion needs within a two-week engagement.
-
Engage our market-entry playbook workstream to craft contracting structures, quality-spec annexes and logistic routes that materially shorten qualification timelines for regulated applications.
Conclusion: The 4,4'-Biphenol market presents a disciplined growth story with concentrated supplier power and rising regulatory attention. For 2026, strategic clarity comes from matching the timing and structure of investments to the nuanced dynamics of purity grading, application qualification cycles, and regulatory compliance. PW Consulting’s full study equips decision-makers with the granular inputs and executable recommendations necessary to convert market expansion into durable advantage.
For detailed analysis of this topic, please visit the official page: 4,4-Biphenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Refrigerants Market to Reach USD 2,570M by 2032 (6.1% CAGR)
By pmarketresearch, 2026-07-30
Natural Refrigerants Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact introduction to our latest market study on Natural Refrigerants. This briefing is crafted for executive teams, corporate strategists, and investment committees preparing decisions in 2026. It highlights the actionable implications of our research while deliberately reserving the granular segment-level figures for the full report — a design choice intended to protect high-value insights and to guide readers to the complete dataset and modeling on our website.
Natural Refrigerants Market
Market snapshot: Where the market stands and where it’s headed
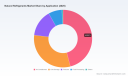
Natural refrigerants are no longer a niche substitution; they are a core technology vector in refrigeration and air-conditioning systems, driven by regulatory pressure, component innovation, and shifting total-cost-of-ownership dynamics. PW Consulting’s base-year assessment (2025) values the global natural refrigerants market at approximately USD 1,700 Million (revenue unit: Million USD). Under our central forecast, the sector is expected to expand at a compound annual growth rate (CAGR) of 6.1% through the 2026–2032 forecast window, reaching roughly USD 2,570 Million by 2032.
Natural Refrigerants Market
That growth trajectory is uneven — influenced by regulatory shifts, feedstock price volatility, and a cadence of product introductions and component availability — but it is robust enough to shift capital allocation decisions across manufacturing, distribution, and service segments in 2026.
Natural Refrigerants Market
Why this report matters for 2026 strategy
- Regulatory inflection points demand action: New and updated regulations have already reshaped permissible refrigerant choices in core end markets. Companies that treat 2026 as a planning inflection — aligning product portfolios, distribution contracts, and retrofit strategies to predictable regulatory paths — will avoid costly rework and gain first-mover advantages.
- Supply-chain fragility is now strategic risk: Raw-material cost spikes and logistic disruptions can erode margins quickly. The report translates commodity and feedstock dynamics into probabilistic risk scenarios and mitigation playbooks that are directly deployable in procurement and sourcing decisions.
- Technological differentiation is actionable: Advances in compressors, component integration, and system-level controls enable manufacturers to outperform on efficiency and lifecycle cost in 2026 procurement contests. We map those technologies to commercial readiness and value capture potential.
- Market sizing to prioritize CAPEX: With a clear macro projection and confidence intervals, finance teams can calibrate investment thresholds for manufacturing expansions, JV formation, or M&A — without relying solely on anecdotal supplier pitches.
What the PW Consulting report delivers (practical, decision-ready content)
- Executive dashboards: A top-line market model (base year 2025, forecast 2026–2032) with scenario toggles for regulation, feedstock cost, and adoption rate. Use this to stress-test revenue and margin assumptions in board deliberations.
- Go-to-market and channel playbooks: Segmented strategies for OEMs, distributors, and aftermarket service providers that prioritize near-term wins and durable revenue streams.
- Regulatory scenario maps: Four plausible regulatory pathways and the operational and product readjustments each requires — mapped to implementation timelines that matter for 2026 procurement cycles.
- Supply-chain and raw-material risk matrices: Detailed supplier mapping, single-point-of-failure diagnostics, and hedging options tied to ammonia and hydrocarbon supply dynamics.
- Technology adoption roadmaps: Component- and system-level adoption curves for CO2, ammonia, and hydrocarbons, including retrofit compatibility and serviceability considerations.
- Investment screening toolkit: A practical framework (IRR and payback lenses) for evaluating brownfield upgrades versus greenfield projects, calibrated to the market’s projected 6.1% CAGR and our revenue model.
Each of these modules is accompanied by reproducible models, data appendices, supplier scorecards, and implementation checklists — intentionally packed with enough specificity to act on, while the full segmented datasets and proprietary inputs remain available in the complete report.
Competitive landscape: players to watch and strategic implications
The market structure shows moderate concentration: top-tier players capture a meaningful share without creating an impenetrable oligopoly (our CR3/CR5 analysis shows a similar concentration metric, indicating room for regional specialists and innovative entrants to scale). Competitive dynamics in 2026 will be defined by three behaviors: vertical integration, component-system bundling, and aftermarket service capture.
- Linde Group (Ireland): A leading supplier with deep industrial CO2 capabilities and broad service footprints. Strategic implication: expect continued emphasis on system-level partnerships with OEMs and large end-users; an attractive counterparty for large-scale refrigeration projects and CO2 supply contracts.
- Airgas Inc. (United States): Major distributor with national logistics advantages. Strategic implication: distribution network and emergency supply service levels will be key differentiators in North American procurement.
- Sinochem, Dongyue, Juhua, and other integrated Chinese producers: These players combine manufacturing scale with integrated feedstock access. Strategic implication: competitive pricing pressure in commoditized segments and rapid ramp-up capacity for certain refrigerant types.
- Puyang Zhongwei, Shandong Yuean, and similar specialty producers: Focused producers who can flex to niche industrial needs. Strategic implication: attractive for regional partnerships and co-development, especially where regulatory and safety codes vary.
- Tazzetti, A-Gas, Secop, Hoshizaki, PRO Refrigeration, Sanhua, and Secop Group partners: Equipment and component suppliers that push refrigeration architectures through compressor innovation, integrated component kits, and product line expansions. Strategic implication: OEMs should prioritize supplier roadmaps that align with their chosen refrigerant strategy to avoid costly redesign cycles.
Recent market moves underscore this dynamic. In 2025 several notable product and portfolio expansions were announced, including PRO Refrigeration’s CO2 chiller for North American food processing (July 2025), Hoshizaki’s substantial lineup expansion (November 2025), and component-package releases by Sanhua mapped to a 2025–2030 roadmap. These actions signal accelerating commercialization and a widening set of viable system options for buyers in 2026.
Regulation, feedstock and price volatility — the three-headed headwind
Regulation remains the principal accelerant for adoption. Since January 1, 2025, U.S. EPA HFC phasedown rules have tightened permissible refrigerant choices in residential, light-commercial and retail food equipment; the EU’s updated F-Gas rules (Regulation 2024/573) have further complicated compliance matrices for certain commercial applications. At the same time, targeted enforcement windows and temporary extensions — for example, the EPA’s no-action assurance extension for refrigerated transport through September 1, 2026 — introduce tactical timing opportunities for firms managing fleet refreshes and retrofit programs.
Operationally, feedstock cost swings are a near-term margin risk. Ammonia prices surged to 2025 highs due to supply constraints and volatile natural gas feedstock, and market intelligence shows continued price elevation into 2026 (U.S. Gulf Coast anhydrous ammonia prices averaged around the levels reported in April 2026). For procurement teams this means implementing dynamic sourcing, longer-term offtake clauses where possible, and scenario-based pass-through mechanisms in contracts.
Strategic moves for 2026 — a checklist
- Product portfolio triage: Segregate SKUs into “must-upgrade,” “monitor,” and “decommission” buckets based on regulatory exposure and retrofit feasibility.
- Supply resilience investments: Negotiate medium-term supply contracts with tiered pricing triggers, diversify feedstock sources, and explore nearshoring components for critical compressor and valve parts.
- Partnership acceleration: Lock strategic supplier partnerships that bundle components with commissioning and aftermarket service guarantees — these deals are being priced as a premium in 2026 tenders.
- Commercial pilots: Deploy controlled rollouts in regulatory-friendlier jurisdictions to validate system designs and gather real-world TCO data ahead of wider market rollouts.
- Service and retrofit monetization: Build aftermarket offerings (retrofit kits, performance guarantees, training) to monetize the installed base in a period of regulatory transition.
How to use this briefing and next steps
This briefing is a strategic “trailer” — it highlights what matters and why, and it points toward where to find the operative levers. For teams preparing 2026 capital plans, procurement strategies, or M&A screens, the full PW Consulting Natural Refrigerants Market report provides the calibrated segment-level data, supplier scorecards, and downloadable models that convert insight into executable plans.
Accessing the full study will enable you to:
- Apply our scenario models to your specific revenue and margin assumptions;
- Identify priority regions, applications, and refrigerant types for targeted investment (segmental data and heatmaps are available in the report);
- Download supplier evaluation templates and negotiation playbooks tailored to the market conditions described above.
PW Consulting stands ready to support board workshops, bespoke scenario modeling, and supplier due diligence in 2026. For decision-makers who need to convert regulatory pressure and commodity volatility into strategically timed investments, our report and advisory services are designed to accelerate confident action while minimizing execution risk.
For detailed analysis of this topic, please visit the official page: Natural Refrigerants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Partition Wall Market to Reach USD 1,779.3M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
Glass Partition Wall Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive preview of our Glass Partition Wall Market study — a tactical briefing designed to equip corporate leaders, investors, and procurement strategists with the high‑level intelligence they need to make decisive moves in 2026. This narrative synthesizes the study’s macro trajectory, competitive dynamics, supply‑chain signals and regulatory inflection points, while intentionally withholding granular segment tables and regional splits to prompt full report access for operational deployment.
Glass Partition Wall Market
Market trajectory at a glance — what matters to 2026 decisions
- The study uses 2025 as the base year and incorporates a five‑year historical run (2020–2025) plus a seven‑year forecast window (2026–2032).
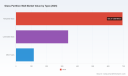
- At the macro level, the global glass partition wall market is growing. Our output shows the market valued at approximately USD 1,150 million in 2025, with the forecast pointing to roughly USD 1,241 million in 2026 and an expected expansion to about USD 1,779 million by 2032.
- The forecast period reflects a compound annual growth rate (CAGR) of 6.5% — a rate that signals steady demand expansion driven by renovation cycles, flexible workspace adoption, and increased specification of high‑performance glazing in commercial and institutional projects.
- Concentration metrics indicate a market where leading groups hold material influence but substantial white‑space remains for challengers: the three‑firm concentration ratio (CR3) stands in the mid‑50s percent range, while the top five players account for under 70% of the market — a structure that favors strategic consolidation, targeted differentiation, and regional plays.
Why this matters for your 2026 strategy
For executives making capital allocation, product roadmap, or M&A choices in 2026, the report’s macro picture yields four practical implications:
Glass Partition Wall Market
- Resource allocation should balance growth and resilience. A mid‑single digit CAGR implies predictable expansion; allocate growth capital to scalable modular product lines and digital specification tools, while preserving agility against input volatility.
- Go‑to‑market segmentation will be a differentiator. With demand spread across commercial, institutional and industrial end markets, success will hinge on tailored offerings (acoustic performance, fire rating, demountability) rather than broad commoditization.
- Supply‑chain optimization is time‑sensitive. Raw material signals (notably soda ash dynamics) have recently softened prices — a window to renegotiate contracts and lock in favorable terms — but suppliers remain exposed to cyclical swings, making dual‑sourcing and local production attractive hedges.
- Regulatory preparedness is non‑negotiable. Evolving test standards and fire/ acoustic codes are influencing specification cycles; early compliance and certification convert into bid‑win advantages on large institutional projects.
Competitive landscape — what to watch in 2026
The market’s concentration profile creates a two‑tier competitive dynamic: established players with integrated design‑to‑install capabilities, and nimble specialists who compete on lead time, customization and cost. The companies profiled in our study exemplify the strategic archetypes:
Glass Partition Wall Market
- Integrated design‑manufacture‑install players that emphasize end‑to‑end service and fast lead times (e.g., established U.S. specialists). These firms win large commercial contracts by coupling engineered systems with installation logistics.
- Regional manufacturers that compete on factory pricing and customization for local projects, often leveraging direct‑to‑site supply chains in high‑growth corridors.
- Premium, sustainability‑oriented producers that emphasize accredited production sites, lifecycle credentials and design awards — attractive to high‑end architects and major corporate occupiers.
- Modular and fit‑out innovators who deliver demountable, reconfigurable walls with short construction timelines, appealing to the flexible workspace trend.
Recent industry moves underline these dynamics. Product introductions and trade show activity in late 2025 and early 2026 show vendors prioritizing slim profiles, demountability and designer aesthetics, while major fit‑out suppliers emphasize lifetime warranties and acoustic performance. These developments underscore the market’s current emphasis on design flexibility and total cost of ownership rather than simple price competition.
Supply‑chain and input risks — actionable signals
- Raw material trend: soda ash — a principal glass feedstock — experienced price declines in 2025 due to oversupply and softer demand in adjacent sectors, while domestic production grew modestly. For manufacturers and buyers, this implies a near‑term cushion in glass melt costs, but not a permanent margin windfall. Procurement teams should exploit the easing for forward buys and renegotiation, while keeping contingency plans for potential supply disruptions.
- Logistics and lead‑times: lead‑time compression has become a commercial advantage. Firms that shorten lead times through regional warehousing, modular components or local glazing capacity gain share in fast‑track refurbishments and tenant‑improvement projects.
- Capital intensity: manufacturers that invest in automated handling, tempering and laminating lines can lower per‑unit cost and reduce breakage exposure; however, payback periods require demand visibility — something the report’s scenario models help to validate.
Regulatory and standards environment — compliance as advantage
Standards and fire/sound testing regimes are converging toward stricter classifications. Key developments include enhanced guidance for mounting and reaction‑to‑fire testing (recent international standards updates) and the continued centrality of airborne sound transmission testing per established ASTM protocols. For suppliers and specifiers alike, documented compliance with these standards is increasingly a gating item for large institutional and public sector tenders. Our report maps out which product attributes and test certifications materially affect bid outcomes across project types.
Practical content of the full report — what you’ll get
Designed as a board‑level playbook and working‑level toolkit, the full study contains:
- Quantitative market model (historical 2020–2025 and forecasts 2026–2032) with downloadable datasets for scenario testing against your internal assumptions.
- Segmented demand analytics across product types, applications and regions — presented with supplier benchmarking and margin analysis. (Note: detailed segment tables and regional splits are intentionally reserved for the full report to maintain our "trailer" posture here.)
- Supplier profiles and a competitive scorecard that rates capabilities in manufacturing footprint, lead time, sustainability credentials and compliance testing.
- Deal‑level and M&A playbooks: valuation drivers, integration checklist, and three acquisition archetypes calibrated to market concentration dynamics.
- Procurement playbook: hedging strategies for raw materials, inventory optimization templates, and contract terms that convert lower input cost into durable margin gains.
- Scenario planning tools and sensitivity analyses that stress test growth under differing macro and input price regimes.
Recommendations for executive action in 2026
- Prioritize certified performance. Expedite testing and certification for acoustic and fire standards if you bid on institutional or high‑end commercial projects — certifications are quickly becoming a table stake.
- Shorten the order‑to‑install cycle. Invest in modular offerings and local assembly hubs to capture faster‑moving tenant improvement business and to defend against low‑cost competitors.
- Use the current input price environment tactically. Lock favorable contracts where possible, but retain flexible sourcing to respond to cyclical rebounds in key feedstocks.
- Evaluate M&A selectively. Given the market’s CR3/CR5 profile, bolt‑on acquisitions that add regional distribution or specialized testing capabilities can produce outsized returns versus broad consolidation plays.
- Embed sustainability and lifecycle arguments into pricing. Clients increasingly value whole‑life performance; demonstrating lifecycle benefits can justify premium pricing and reduce procurement churn.
Final note — the strategic utility of the full study
This preview demonstrates the type of actionable thinking and forecasting that PW Consulting delivers: a market growth pathway, competitive map, supplier‑risk framework and decision tools calibrated for 2026. To translate these strategic insights into operational plans — from capex choices to bid strategies and acquisition screening — you will need the report’s segmented tables, regional demand matrices and supplier scorecards. Those detailed datasets and benchmarks are intentionally withheld here to preserve the report’s value proposition and to guide practitioners to the full intelligence pack.
If you are preparing budgets, revising product roadmaps, or evaluating M&A in 2026, the full Glass Partition Wall Market report provides the granular evidence base and executable playbooks you will use to move from strategy to results. Contact PW Consulting to access the complete study and the underlying datasets that will allow you to run tailored scenarios against your portfolio.
For detailed analysis of this topic, please visit the official page: Glass Partition Wall Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PolyDADMAC Market Set to Reach USD 428.9 Million by 2032
By pmarketresearch, 2026-07-30
PolyDADMAC Market: Strategic Imperatives for 2026 — PW Consulting Market Preview
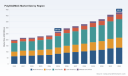
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our PolyDADMAC Market study — a practical guide designed to shape high‑stakes decisions through 2026 and beyond. Our baseline analysis uses 2025 as the reference year and traces history from 2020–2025, with a forward forecast covering 2026–2032. At the macro level, the global PolyDADMAC market expanded from roughly USD 200 million in 2020 to about USD 267.45 million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 6.98% through 2032, when the market is forecast to reach approximately USD 428.9 million. This trajectory frames the operational and strategic choices facing producers, buyers, and investors in 2026.
PolyDADMAC Market
Why this matters in 2026
-
Regulatory tightening and compliance are moving from risk to determinant. Recent municipal procurement requirements and standards (notably NSF/ANSI 60 and AWWA B451‑10 enforcement) are raising the bar for allowable monomer content and validated use rates for PolyDADMAC used in drinking water. These constraints are already shaping supplier qualification and technical due diligence processes for public and private buyers.
PolyDADMAC Market -
Raw material volatility — especially allyl chloride shortages and petrochemical feedstock disruptions seen along Gulf Coast supply chains — has shifted upstream risk into a strategic procurement issue. Buyers and producers must treat feedstock access as a competitive lever, not a background uncertainty.
PolyDADMAC Market -
Procurement events and long‑term contracts are evolving. Recent tenders show municipalities are specifying NSF certification and AWWA standard compliance as gating criteria, forcing incumbent suppliers to prove both lab and supply reliability in tender windows.
-
Market growth remains healthy but uneven; the overall expansion validates investment and M&A interest while reminding stakeholders to prioritize operational resilience and regulatory compliance ahead of pure capacity plays.
What the full PolyDADMAC Market study delivers (practical, action‑oriented)
-
Robust market sizing and forecast model (2020–2032) with scenario toggles for feedstock price shocks, regulatory tightening, and accelerated municipal procurement cycles.
-
Demand‑driver deep dives that map water treatment trends, pulp & paper cycles, textile and personal care demand vectors, and oil & gas use cases — each tied to leading indicators and procurement timing.
-
Supply‑chain stress tests and raw‑material exposure analysis, including allyl chloride sourcing scenarios and contingency plans for Gulf Coast production interruptions.
-
Competitive benchmarking and supplier playbooks that evaluate certification portfolios, commercial footprints, production technology (including DADMAC‑to‑PolyDADMAC integration), and export capability.
-
Commercial tools: procurement RFx templates, supplier qualification checklists keyed to NSF/AWWA requirements, price‑scenario dashboards, and a capex decision framework for greenfield or debottleneck investments.
-
Strategic options and M&A screening criteria that prioritize regulatory compliance, feedstock security, and margin resilience over headline capacity metrics.
-
Note: the Preview intentionally withholds granular regional and application split tables to protect the commercial value of the IP; these detailed segmentations are included in the full report available through the report portal.
Competitive landscape — who matters and why
The market profile shows a mix of regionally strong manufacturers and specialized suppliers. Certification status and integrated process capability are emerging as key differentiators.
-
Integrated Asian producers with certification focus: Several China‑based manufacturers operate integrated DADMAC‑to‑PolyDADMAC processes and hold NSF/REACH listings. Their combined strengths are scale, cost competitiveness on exported volumes, and multiple molecular‑weight grades suitable for water and industrial applications. High‑capacity facilities and export orientation place them as go‑to options for buyers seeking volume and technical grades.
-
U.S. and regional suppliers: North American suppliers and specialty producers emphasize local compliance (NSF/ANSI listings) and proximity to municipal tenders. Their strengths include faster response cycles for local contracts, established compliance paperwork, and relationships with water authorities where AWWA compliance is table stakes.
-
Specialist regional players: In markets such as Southern Africa and Latin America, local brands combine regional supply security with certification levels tailored to municipal and industrial customers. These players are often preferred in public tenders where logistics, service, and local regulatory familiarity matter.
-
Market concentration: Our study measures the market as moderately fragmented — with the top three and top five players representing a minority share of overall demand. This structure supports continued competition on certification, service, and niche technical differentiation rather than pure price dominance.
-
Procurement signal in practice: A mid‑2025 municipal tender illustrates the current procurement dynamic: buyers are seeking certified primary and secondary suppliers with the capacity to meet AWWA and NSF standards across multi‑year windows, emphasizing both compliance and continuity of supply.
Regulation, raw materials and channel signals — the operational trifecta
-
Regulatory gating: NSF/ANSI 60 requirements (including very low allowable monomer thresholds and prescribed maximum use rates for drinking water applications) are now an operational constraint. Suppliers lacking validated test matrices and certification pathways are effectively excluded from municipal opportunities.
-
Feedstock exposure: Allyl chloride availability is the single most actionable upstream risk. Price spikes or supply interruptions have outsized impacts on short‑cycle producers; integrated upstream conversions or secure tolling/offtake arrangements materially reduce outage risk.
-
Channel and tender behavior: Municipal tenders increasingly combine technical compliance with service continuity clauses (dual sourcing, penalty regimes), which raises the bar for supplier operational rigor and insurance arrangements.
Strategic implications and recommended actions for 2026 decision‑makers
-
For buyers (municipal and industrial): Move from one‑off spot purchases to tiered supplier portfolios. Establish primary/secondary sourcing with explicit certification and contingency SLAs, and embed feedstock escalation mechanisms into contract terms to preserve supply and limit price volatility exposure.
-
For manufacturers: Prioritize certification completeness and auditable supply‑chain traceability. Investment in validated test protocols and visible NSF/AWWA compliance unlocks municipal pipelines and reduces procurement friction.
-
For investors and M&A teams: Target assets that combine certification status, feedstock security (either via proximity to allyl chloride sources or integrated upstream capability), and demonstrated delivery to regulated buyers — these attributes significantly compress execution risk.
-
For procurement and operations leaders: Run a five‑year capex and inventory simulation tied to our forecast scenarios. Small capacity additions timed to demand inflection points (rather than headline capacity grabs) produce better returns when paired with long‑term offtake agreements.
-
For R&D and product teams: Differentiate by low‑residual monomer grades, broaden validated molecular‑weight portfolios, and invest in low‑cost, low‑emissions manufacturing steps that appeal to sustainability‑literate procurement bodies.
-
Scenario planning: Prepare three tactical playbooks — (A) upstream supply shock; (B) regulatory tightening (lower allowable monomer thresholds); (C) accelerated municipal adoption — each with supplier selection, pricing, and inventory steps. Our full report includes quantified P&L and inventory impacts under these scenarios.
How PW Consulting supports transaction and operational decisions
-
Customizable market models and scenario dashboards that let teams stress‑test revenue, margin, and capex under feedstock and regulatory permutations.
-
Supplier risk heatmaps and a certification‑first vendor scoring tool to accelerate RFx shortlists and reduce procurement cycle time.
-
M&A diligence playbooks that focus on regulatory compliance, feedstock contracts, and tangible certification assets rather than headline capacity alone.
-
Operational readiness and go‑to‑market templates for suppliers pursuing municipal channels, including sample contract language, audit checklists, and tender response strategies.
In summary: the PolyDADMAC market presents a compelling mix of steady growth, concentrated technical barriers to entry, and acute upstream risk. 2026 will be a year when buyers and producers that prioritize certification, feedstock security, and tactical source diversification materially outperform peers who treat PolyDADMAC as a commodity line item. Our full PolyDADMAC Market report contains the granular segmentation, supplier scorecards, scenario outputs, and playbooks needed to operationalize these insights. For organizations planning procurement cycles, capex, or M&A activity this year, that detailed intelligence will be essential.
To access the complete data tables, regional and application breakouts, and supplier revenue benchmarking, please consult the full report on the PW Consulting PolyDADMAC Market page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: PolyDADMAC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: A2P SMS & cPaaS Market to Hit USD 87.5B by 2032 (6.5% CAGR)
By pmarketresearch, 2026-07-30
A2P SMS & cPaaS Market 2026: A Strategic Preview for Enterprise Decision‑Makers
Executive summary
As enterprises reassess customer engagement architectures in 2026, A2P SMS and Communications‑Platform‑as‑a‑Service (cPaaS) remain central to digital operations. PW Consulting’s upcoming market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames the space as a mature but evolving ecosystem: after growing through the prior half‑decade, the market sits on a steady long‑run trajectory with a 6.5% CAGR across the forecast window. Our analysis translates that macro momentum into concrete choices for procurement, product strategy, risk management, and M&A posture—without exposing the granular splits that materially inform pricing and negotiation tactics (those are included in the full report available through PW Consulting).
A2P SMS & cPaaS Market
Market trajectory in plain terms
From 2020 through the 2025 base year the A2P SMS & cPaaS market expanded notably, reflecting both re‑platforming by enterprises and steady demand for authentication, transactional messaging, and evolving omnichannel stacks. By the 2025 base year the market had grown substantially from its earlier five‑year position; under our central forecast the market continues to expand through 2032, reaching an elevated scale that reflects the compounding influence of new messaging modalities, enterprise communications modernization, and broader digital identity use cases.
A2P SMS & cPaaS Market
Two headline datapoints to anchor planning: the study uses 2025 as the base year for benchmarking and models a 6.5% compound annual growth rate across 2026–2032. Those assumptions drive our scenario models and stress tests—inputs that procurement, finance, and product teams can use to size budgets and prioritize initiatives through the end of the decade.
A2P SMS & cPaaS Market
Why this matters to enterprise leaders in 2026
-
Procurement and supplier strategy: With vendor concentration moderate (the leading three and five suppliers capture a material but not dominant share of market activity), buyers must balance the cost and speed advantages of large platforms against the specialization and regional reach of smaller providers. Sourcing decisions made in 2026 will lock in multi‑year integration costs and experience design.
-
Product and channel mix decisions: SMS remains the workhorse for transactional and authentication flows; cPaaS investments enable richer, programmable channels. Enterprises must therefore decide where to keep control (in‑house gateways, private connectors) versus where to outsource to managed CPaaS partners—decisions that affect latency, deliverability, and regulatory risk.
-
Cost and energy exposure: Rising data‑center and energy costs are an operational headwind that can change unit economics for high‑volume messaging and real‑time media services. Our report correlates electricity and capacity price trends with marginal cost pressure on cloud and CPaaS providers—critical for financial modeling and supplier negotiation.
-
Regulatory and compliance posture: The regulatory characterization of messaging services—shaped by precedent decisions—continues to affect out‑of‑band obligations, recordkeeping, and interconnection practices. Enterprises must bake compliance into SLA and indemnity clauses with vendors, especially for authentication and identity flows.
-
Resilience and fraud mitigation: Carrier‑level filtering, spam mitigation, and fraud detection are front‑line risks. Selecting partners with demonstrable deliverability performance and anti‑fraud tooling is as important as price per message when the reputation of sender IDs and throughput caps can vary by market.
What the PW Consulting report delivers (practical components)
-
Decision‑ready vendor scorecards: Comparative assessments across capability, coverage, compliance, roadmap maturity, integration complexity, and commercial model. These scorecards are built to plug into RFP and vendor selection processes.
-
Negotiation playbooks and contract checklists: Clause‑level guidance for service levels, audit rights, data residency, porting and number management, indemnities for deliverability, and price escalator mechanisms.
-
Scenario financial models: TCO templates and scenario outputs that use the study’s 6.5% CAGR baseline and optional upside/downside cases so CFOs and FP&A teams can stress test budgets and evaluate build vs buy.
-
Implementation and migration blueprints: Step‑by‑step guidance for moving authentication, transactional, and engagement traffic to new platforms—includes runbook items for carrier onboarding, number management, A/B deliverability testing, and regulatory sign‑offs.
-
Go‑to‑market and monetization playbooks: For product teams seeking to leverage CPaaS capabilities—templates for packaging messaging bundles, usage tiers, and billing constructs that preserve margin while unlocking growth.
-
Risk and resilience maps: Operator and regional risk heatmaps, concentrated dependency assessments, and contingency plans for supply disruption and energy shocks.
Competitive landscape: who matters and why
The sector is populated by a mix of global platform leaders, operator‑scale carriers with messaging arms, and specialized challengers. Each category creates distinct risks and opportunities for enterprise buyers.
-
Global platform leaders (e.g., Twilio): These vendors excel at developer ecosystems, rich APIs, and global reach. The value they bring is speed to market, breadth of integrations, and strong product roadmaps—offset by relatively higher cost and potential vendor lock‑in for complex use cases.
-
Omnichannel and operator‑aligned providers (e.g., Infobip, Sinch, Tata Communications, Route Mobile): These firms combine deep regional operator relationships with omnichannel stacks, making them effective where local carrier certification and regulatory nuance are decisive. They are attractive for enterprises needing regional deliverability and managed onboarding at scale.
-
Communications and UCaaS incumbents (e.g., Vonage, RingCentral): These vendors differentiate by integrating messaging with broader unified communications portfolios—useful for organizations seeking a single vendor for contact center, voice, and messaging.
-
Network‑centric and API specialists (e.g., Bandwidth, Plivo, Mitto, OpenMarket, CM.com): Often stronger on network ownership, number management, and cost engineering, these players can be advantageous for high‑volume transactional traffic or for enterprises that require more control over routing and SS7/ SMPP relationships.
-
Specialized challengers and regional players (e.g., Kaleyra, Route Mobile, Commio, Bird, TXTImpact, Teliqon, Twixor): These companies frequently innovate at the product layer (for example, rich messaging formats, low‑latency gateways, verticalized solutions) or focus on niche geographies and use cases.
Competitive dynamics are active: strategic partnerships, regional consolidation, and product extensions (notably around rich messaging standards and programmable RCS) are accelerating. A practical example: in March 2026 a market participant announced a new instant RCS business messaging product with accompanying industry recognition—an indicator that richer messaging formats are entering commercial deployments and shaping vendor roadmaps.
Operational headwinds and regulatory notes
-
Energy and infrastructure cost volatility: Wholesale electricity costs and capacity market movements have materially increased operating expense for data centers and cloud facilities in recent years. That shift has implications for providers whose cost base is energy‑intensive; enterprises should include energy exposure in long‑term supplier TCOs.
-
Carrier filtering and policy risk: Carriers globally continue to harden anti‑spam and A2P validation rules. These actions can abruptly change throughput or require additional certification steps; the full report provides risk mitigations and contractual language to address such events.
-
Regulatory precedent: Constitutional regulatory treatments that clarify messaging services’ status in key jurisdictions affect how services are provisioned, taxed, and audited. Historical regulatory orders have established important contours for what constitutes an information service versus an interconnected service—an important distinction for compliance teams.
A concise 2026 playbook for executives
-
Map your critical flows: Start by categorizing traffic (authentication, transactional, marketing, engagement) and apply different supplier and risk profiles to each—don’t treat all messaging the same.
-
Run a two‑tier supplier strategy: Combine at least one global platform for speed and cross‑border coverage with regional or network‑centric partners for high‑assurance delivery and cost control.
-
Insist on transparency: Require vendors to disclose routing, termination practices, and energy/resilience metrics; bake audit rights into contracts.
-
Price and capacity stress tests: Use the PW Consulting scenario models to test the impact of energy spikes, new compliance requirements, and rapid volume growth on unit economics.
-
Design for extensibility: Architect message flows so that richer channels (RCS, in‑app notifications, voice passcodes) can be introduced incrementally without large rip‑and‑replace projects.
-
Prepare for consolidation and opportunistic M&A: Vendors will continue to consolidate and specialize; maintain a shortlist of strategic targets and M&A criteria aligned with your endpoints (capability, customer base, or regional coverage).
Closing—what to expect next
PW Consulting’s full market study is designed as a decision support toolkit: it couples the headline growth trajectory and scenario analysis with vendor scorecards, contract playbooks, and operational runbooks that procurement, product, and risk teams can apply immediately. This preview exposes the trends and tradeoffs you must manage in 2026, while reserving the granular regional and application splits, as well as the vendor‑level scoring matrices, for the full report and subscription access.
For teams preparing 2026 budgets, negotiating new multi‑year CPaaS contracts, or building resilient messaging stacks, the study supplies both the macro market frame and the practical artifacts needed to act. Access to the full dataset and tactical appendices is available through PW Consulting’s report portal—request the comprehensive deliverables to translate this preview into executable plans.
For detailed analysis of this topic, please visit the official page: A2P SMS & cPaaS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
TEC Modules Market to Reach $1,688.97M by 2032 at 8.7% CAGR — Asia Pacific Leads ($488.66M)
By pmarketresearch, 2026-07-30
Thermoelectric Cooler (TEC) Modules Market — Strategic Primer for 2026 Decision‑Makers
As PW Consulting’s senior strategy team, we prepared this executive primer to translate our Thermoelectric Cooler (TEC) Modules Market study into immediate, operational value for firms taking strategic decisions in 2026. The TEC market is on a multi‑year expansion path: from a 2025 base year sized at roughly USD 940 million (Million, base year 2025), the sector is projected to exceed USD 1.03 billion in 2026 and continue to expand at a compound annual growth rate (CAGR) of about 8.7% through our 2026–2032 forecast window, reaching the high‑single‑digit to low‑double‑digit hundreds of millions by 2032. This trajectory elevates TEC modules from a niche specialty component to an investible, scalable element of thermal management programs across telecom, photonics, medical, automotive and industrial segments.
Thermoelectric Cooler (TEC) Modules Market
Why this research matters in 2026
-
Strategic inflection: Energy‑efficiency regulation, the drive for refrigerant‑free solid‑state cooling, and accelerating design‑in requirements from photonics and telecom OEMs have converged, creating a window for TEC vendors and integrators to move beyond one‑off engineering orders toward platformized, higher‑volume solutions.
Thermoelectric Cooler (TEC) Modules Market -
Commercial timing: The market’s projected expansion in 2026 is large enough to justify investments in capacity, certification and new product lines — but still early enough that first movers who execute on standards, supply security and design partnerships can capture disproportionate share gains.
Thermoelectric Cooler (TEC) Modules Market -
Supply chain leverage: Bismuth telluride remains the dominant semiconductor material for active TECs; capacity expansions and concentrated upstream supply make contracts, quality control and supplier diversification central to near‑term competitiveness.
What the PW Consulting report delivers — practical, decision‑ready content
-
Market sizing and forecasting model (2020–2025 historical; 2026–2032 forecast) with scenario capability to test demand under different adoption and policy pathways.
-
Segment-level diagnostics (by type, application and geography) presented as growth narratives and purchase‑driver maps — we intentionally withhold raw subsegment tables here to preserve the value of the full report, but the study includes granular shipment and revenue models by segment.
-
Competitive playbooks: product benchmarking, capability matrices, route‑to‑market maps and supplier scorecards for the industry’s active players.
-
Technology and standards tracker: performance roadmaps (ΔT, cooling power, efficiency), Telcordia and telecom qualification pathways, and certification cost/time estimates.
-
Supply‑chain and input‑cost models: bismuth telluride sourcing scenarios, labor and capital intensity benchmarks, and a stress‑test module for pricing and margin planning.
-
Commercial playbook: go‑to‑market options, OEM engagement strategies, prototyping and time‑to‑design‑win accelerators, plus an M&A/opportunity short‑list and diligence checklist.
Competitive landscape — who matters and why
The TEC vendor set in 2026 combines specialists with broad thermal portfolios, mass‑producers that enable cost scale, and boutique engineering houses focused on high‑reliability applications. The market is moderately concentrated: top suppliers hold meaningful share but there remains room for new entrants and regional champions. Below is a curated snapshot of firms we track closely (profile summaries are drawn from public disclosures):
-
Sheetak — Austin, Texas, USA ( https://sheetak.com/): Active manufacturer of CENTUM® single‑ and multi‑stage TEC modules, µCENTUM™ micro TECs, and custom Peltier coolers for photonics, optoelectronics, aerospace, and high‑performance applications. Notable 2026 moves: new miniature µCENTUM™ SKUs, a modular CryoSnap™ development kit, and expanded North American partnerships and trade show presence to accelerate design‑wins.
-
TEC Microsystems GmbH — Berlin, Germany ( https://www.tec-microsystems.com/): Manufacturer of aluminum‑plate and ceramic TEC series optimized for telecom, detectors and heavy‑load applications; market positioning emphasizes reliability and standards compliance for telecom qualification.
-
Ferrotec Corporation — Tokyo, Japan ( https://www.ferrotec.com/): Provider of high‑power Peltier TEC families targeting industrial and electronics cooling with broad high‑power portfolios and global manufacturing footprint.
-
Laird Thermal Systems — Delaware, USA ( https://lairdthermal.com/): Supplies OptoTEC micro TEC modules and high‑power thermoelectric coolers for telecom and industrial systems; strong channel and integration capabilities.
-
TE Technology, Inc. — Sherman Township, Pennsylvania, USA ( https://www.thermoelectric.com/): High‑quality manufacturer of TEC modules, cold plates and liquid coolers for electronics, medical and industrial markets; strengths in custom engineering.
-
Crystal Ltd. — Hong Kong ( https://www.crystalltherm.com/): Mass producer of bismuth telluride TEC modules and assemblies serving industrial and specialized cooling applications; cost leadership through scale.
-
KELK Ltd. — Tokyo, Japan ( https://www.kelk.co.jp/): Manufacturer under Komatsu Group with specializations in optoelectronics and precision cooling.
-
RMT Ltd. — Russia ( https://www.rmt-group.com/): Supplier of multi‑purpose TECs for high heat‑absorption applications, including deep‑cooled CMOS and IR sensors.
-
Thermonamic Electronics (Jiangxi) Corp. Ltd. — Jiangxi, China ( https://www.thermonamic.com/): Producer focused on high‑performance assemblies and regional volume supply.
-
KRYOTHERM — Germany ( https://kryotherm.com/): Manufacturer of high‑power and standard TEC modules for demanding thermal management tasks.
Recent competitive dynamics have been anchored by product launches and enabling offerings: Sheetak’s 2026 catalog introductions and prototyping kits are representative of a broader push to shorten design cycles and lock in OEM design positions early.
Key dynamics, inputs and risks
-
Raw material dependency — Bismuth telluride is the dominant active material. Manufacturers are expanding production capacity, but supply concentration and quality variance create near‑term procurement risk and bargaining asymmetry.
-
Standards and qualification — Telcordia GR‑468 and telecom reliability pathways matter for photonics and communications applications; certification timelines materially affect time‑to‑revenue for new products.
-
Labor and manufacturing intensity — High‑reliability TECs are labor and skill intensive. Labor cost pressures and specialized assembly needs mean automation and process control investments have favorable payback for firms targeting telecom and medical segments.
-
Market adoption drivers — Energy efficiency mandates and the push for refrigerant‑free cooling keep demand momentum steady; however, pockets of volatility exist by end‑market (e.g., automotive adoption cadence vs medical program cycles).
-
Infrastructure buildout — Expansion of capacity for bismuth‑telluride TECs and regional manufacturing investments are enabling nearer‑shoring options but require capital discipline to avoid overcapacity in adverse demand scenarios.
2026 decision playbook — concrete moves for executives
-
Prioritize design‑wins over one‑off sales. Shorten prototype cycles by investing in kits, application‑specific reference designs, and co‑engineering programs with target OEMs. Time to first shipment will meaningfully influence share gains in 2026–2027.
-
Lock material supply now. Secure multi‑year agreements for bismuth telluride or explore vertical partnerships to reduce volatility. Hedging raw material costs should be part of pricing models.
-
Certify early for high‑value verticals. Telcordia and equivalent standards certification should be a gating criteria for product roadmaps aimed at telecom and photonics customers.
-
Segment product portfolio: offer platformized single‑stage and multi‑stage product lines with clear performance tiers, while keeping a bespoke engineering arm for high‑margin, high‑reliability programs.
-
Invest in manufacturing resilience: targeted automation, quality control, and regional buffer capacity reduce lead times and improve margin stability.
-
Map M&A and partnership targets: pursue bolt‑on suppliers that add raw material security, assembly capabilities, or established OEM relationships rather than broad, expensive diversification.
-
Operationalize commercial intelligence: deploy a competitor watchlist, customer decision triggers, and an early‑warning dashboard for leading indicators such as telecom procurement cycles, photonics testbench orders and medical device qualification starts.
How PW Consulting’s report converts insight into executable advantage
Our full study delivers the analytical building blocks executives need to operationalize the above playbook: downloadable financial models, segment demand drivers, supplier scorecards, product GAP analyses, cost and margin simulators, and an M&A short‑list with diligence checklists. We also include scenario matrices that let teams stress‑test capacity investments and certification timelines against slower or faster adoption curves.
In keeping with this primer’s role as a directional preview, we have intentionally withheld the granular subsegment revenue tables and regional/application breakdowns from this summary. Those details — including shipment counts, ASP trajectories by product family, and segment‑level margins — are included in the subscription report and interactive model, which are essential for bid justification, capex planning and target selection.
Next steps for 2026
-
Download the full PW Consulting TEC Modules Market report to access the detailed segment models, supplier scorecards and scenario tools necessary to operationalize the strategy above.
-
Schedule a workshop with our thermal‑management practice to translate the market scenarios into a 90‑day action roadmap (procurement commitments, certification plan, and product roadmap milestones).
Thermoelectric cooling is entering a growth phase where engineering excellence, supply‑chain foresight and standards compliance will determine winners. Our research equips leaders to move from observation to decisive action in 2026 — but the window to position for scale is narrow. For the full data set, company scorecards and executable models, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Thermoelectric Cooler (TEC) Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HTCC Ceramic Substrates Market to hit USD 339.0M by 2032 at 7.65% CAGR
By pmarketresearch, 2026-07-30
HTCC Ceramic Substrates Market — Strategic Briefing for 2026 Decision-Makers
Executive overview
As semiconductor packaging complexity and high-reliability electronics converge, High-Temperature Co-fired Ceramic (HTCC) substrates are emerging as a strategic material choice across telecommunications, automotive electrification, industrial controls, and harsh-environment sensing. PW Consulting’s HTCC Ceramic Substrates Market study (base year 2025; historical 2020–2025; forecast 2026–2032) quantifies this transition and translates it into actionable guidance for 2026 corporate planning.
HTCC Ceramic Substrates Market
At the aggregate level, the market’s trajectory is clear: the industry expanded steadily from a modest base in 2020 to approximately USD 202.8 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.65% through 2032, reaching roughly USD 339.0 Million by the end of the forecast window. This combination of durable near-term demand and healthy medium-term momentum creates a window for investment, capacity rationalization, vertical integration, and targeted partnerships — but also raises important sourcing and pricing considerations that every C-suite should factor into 2026 strategy.
HTCC Ceramic Substrates Market
Why this report matters for 2026 decisions
-
Timing for capacity and product investments: With a mid-single-digit-to-high-single-digit CAGR and clear end-market pull, the next 12–18 months are pivotal for firms choosing between brownfield capacity expansion, greenfield projects, or capability-focused M&A. Our analysis maps demand inflection points across the forecast period so executives can align capital deployment with the most attractive time windows.
HTCC Ceramic Substrates Market -
Risk-aware sourcing strategies: Raw-material volatility and regional supply idiosyncrasies materially influence margin outcomes. The report identifies supply-chain levers and hedging options that can protect gross margin while preserving flexibility for product customization.
-
Competitive positioning and consolidation plays: The market exhibits meaningful concentration among established specialty players. Understanding competitive strengths and gaps — from hermetic sealing and multilayer integration to specialty formulations and high-reliability military/aerospace qualifications — is necessary to craft acquisition targets, JV partners, or differentiation strategies.
Market dynamics — what is driving change
Three interlocking forces are shaping the HTCC substrate landscape in 2026:
-
End-market complexity and reliability demands. Higher-frequency telecom architectures, power-dense EV power electronics, and downhole/aerospace sensing all favor HTCC’s thermal and mechanical stability. Buyers are moving from off-the-shelf commodity substrates toward engineered solutions that embed thermal vias, multilayer routing, and hermetic package options.
-
Raw-material and cost pressure. Key upstream materials remain a source of uncertainty. For example, bauxite consumption rose in 2025 and metallurgical alumina import pricing sits materially higher than prior years; concurrently, primary metal manufacturing cost indices saw a sharp increase in 2024. These inputs feed through to ceramic formulations and processing costs and require active procurement management and, in some cases, design-for-cost initiatives.
-
Geopolitical and regional capacity dynamics. Idle alumina refinery capacity in certain markets has not been reactivated, creating pockets of regional supply tightness. Manufacturers that can manage cross-border logistics and adapt their material choices without compromising reliability gain a tactical advantage.
Segmentation and demand themes (high level)
The report dissects demand along the classic axes — material type, end-application, and geography — and links each to procurement and technology actions that matter for 2026. Rather than publishing raw subsegment values in this summary, we highlight the conceptual implications:
-
By material type: HTCC formulations commanding the highest-value, high-reliability applications require investment in process control, multilayer lamination, and advanced metallization. LTCC and other ceramics remain relevant for cost-sensitive or lower-temperature applications, creating a natural tiering of addressable market opportunities.
-
By application: Telecommunications (including next-generation radio infrastructure), power electronics for electric vehicles, consumer electronics at the high-frequency edge, and industrial/secure sensing are each stimulating different technical requirements. Commercial decisions — e.g., pursuing automotive-grade qualification vs. focusing on telecom RF — lead to distinct CAPEX and certification roadmaps.
-
By geography: Regional demand pockets and supply-chain realities (from raw material availability to labor and energy costs) affect where to site capacity and how to design inventory buffers. The full report provides scenario-based geographies for plant placement and distribution network design.
Competitive landscape — who matters and why
The HTCC market is specialized: a handful of capable players control a meaningful share of revenue and technological know-how, creating both partnership opportunities and competitive pressure. Market concentration metrics reinforce that strategic moves by top-tier suppliers ripple across the supply chain.
-
NEOTech (Southern California, USA; https://www.neotech.com): A leading North American HTCC manufacturer with strengths in alumina and aluminum nitride formulations, hermetic sealing, and multilayer capability. NEOTech is a go-to for customers needing high-reliability packaging combined with rapid design iteration.
-
AdTech Ceramics (Chattanooga, TN, USA; https://www.adtechceramics.com): Known for proprietary HTCC blends and expertise in hermetic straight-through vias and dense interconnects. AdTech’s niche focus on military, aerospace, medical, and extreme-temperature applications positions it as a premium partner for qualification-heavy programs.
-
Maruwa Co., Ltd. (Japan; https://www.maruwa-g.com): A producer of alumina multilayer HTCC substrates and packages for sensor packaging, MEMS, optical communications, and LED applications. Maruwa’s engineering depth in multilayer sintering and fine-line metallization is a differentiator for compact, high-performance assemblies.
-
Jimei Materials (Shenzhen, China; https://www.jimei-materials.com): Focused on HTCC substrates for aerospace electronics, MEMS packaging, RF cavities, and downhole sensors. Jimei’s portfolio emphasizes applications in harsh environments and illustrates how regional suppliers can combine scale with specialized technical offerings.
Collectively, the top three to five vendors control a significant share of industry revenues, and their strategic decisions on capacity, qualification timelines, and customer partnerships will materially shape supplier economics in 2026 and beyond.
Report contents — practical elements for implementation
PW Consulting’s full HTCC Ceramic Substrates Market report combines data rigor with practical tools that are directly usable in 2026 planning cycles:
-
360° market sizing and growth scenarios (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity runs that stress-test demand under different macroeconomic and supply-chain shocks.
-
Actionable supplier scorecards: technology capabilities, qualification timelines, capacity footprints, and margin-pressure triggers to help procurement prioritize partners or M&A targets.
-
Cost-to-serve models that translate raw-material index movement into margin scenarios at the product-family level, enabling engineering-to-cost tradeoffs.
-
Segmentation playbooks that map go-to-market choices (e.g., pursuing automotive AEC-Q certification vs. telecom RF performance optimization) to expected time-to-revenue and incremental CAPEX needs.
-
Regulatory and materials risk annex: monitoring schedules for metallurgical input prices, regional refinery capacity shifts, and proposed trade or environmental measures that could alter sourcing strategies.
Strategic implications and recommended actions for 2026
-
Prioritize modular capacity and flexible process platforms. Given input-price uncertainty and variable demand by application, invest in modular lines that can switch between HTCC formulations or shift output between high-margin specialty work and higher-volume runs.
-
Advance vertical integration selectively. For companies with scale, securing upstream alumina supply or investing in strategic stockpiles can be value-accretive. The business case should be stress-tested against the cost-of-capital and the sensitivity of your product mix to alumina price movements.
-
Differentiate through qualification and systems-level partnerships. Winning long-cycle, high-value contracts in aerospace, downhole sensing, or automotive power electronics depends on demonstration of qualification capabilities and reliability. Build co-development agreements with OEMs to lock in long lead times and create switching costs.
-
Develop nimble procurement and hedging policies. Integrate raw-material index monitoring into monthly operations reviews and implement rolling hedges or long-term contracts where pricing signals warrant it.
Conclusion — how to use this briefing
For 2026 strategic planning, the HTCC substrate market presents a mix of predictable growth and tactical uncertainty. The overall market is on a steady upward trajectory, creating attractive windows for investment; concurrently, raw-material and regional supply dynamics demand proactive risk management. PW Consulting’s full report converts these macro realities into decision-ready tools — from supplier scorecards to cost-to-serve analytics — enabling leaders to choose the best mix of build, buy, or partner strategies.
To access the detailed segmentation, supplier benchmarking tables, and scenario spreadsheets that underlie these findings, consult the full PW Consulting HTCC Ceramic Substrates Market report on our website. The executive summary above is intended to orient strategy discussions and surface the most consequential issues; the complete study contains the granular analytics needed to finalize 2026 capital and commercial plans.
For detailed analysis of this topic, please visit the official page: HTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acetaminophen Market Set for 4.7% CAGR (2026–2032) — Demand Shifts Ahead
By pmarketresearch, 2026-07-30
Acetaminophen Market 2026: Strategic Intelligence Briefing
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking narrative designed to orient executive teams, corporate strategy committees, and private equity sponsors preparing decisions in 2026. This briefing synthesizes our latest Acetaminophen Market research — a data-driven, scenario-ready resource built on a 2020–2025 historical base and a 2026–2032 forecast horizon. It highlights the practical strategic levers that will determine winners and laggards in a market characterized by steady expansion, regulatory attention, and supply-chain concentration.
Acetaminophen Market
Market Snapshot — what the headline numbers mean for strategy
By our base-year accounting (2025), the global acetaminophen market stands at approximately USD 10,500 Million, after a recovery and expansion period through 2020–2025. Our forecast shows a compound annual growth rate (CAGR) of roughly 4.7% across 2026–2032, with the market progressing toward a projected value in excess of USD 14 billion by 2032. This trajectory reflects a combination of durable OTC demand, continued use in prescription combination products, and growth in emerging geographies and formulation formats.
Acetaminophen Market
These headline numbers mask an important strategic truth: modest aggregate growth does not translate into uniform opportunity. Market expansion is being driven by a mix of demographic tailwinds, shifting clinical guidance, and differentiated product-level dynamics that create localized pockets of high-return activity. Effective 2026 strategies will therefore be those that convert macro stability into micro advantage — via targeted portfolio choices, resilient sourcing, and defensible go-to-market models.
Acetaminophen Market
Why this research matters for 2026 decision-making
- Actionable market sizing with scenario overlays: Our model provides a baseline and multiple stress-tested paths (regulatory tightening, supply shock, and substitution scenarios). That lets commercial teams quantify upside and downside to 2032 before committing capital.
- Regulatory early-warning and compliance roadmaps: The pace of labeling and usage guidance changes has accelerated. Our report maps regulatory actions to product- and geography-level commercial impacts to prioritize mitigation and opportunity responses.
- Supply-chain risk quantified: With material supply concentration in a small number of producing geographies for active pharmaceutical ingredient (API), our supplier risk heatmap correlates exposure with cost, lead-time, and substitution difficulty — a necessary input into any 2026 sourcing decision.
- Competitive positioning and M&A playbook: We analyze incumbent portfolios and manufacturing footprints to identify attractive consolidation targets, capacity plays, and brand-specified arbitrage opportunities.
Key dynamics shaping 2026 strategic choices
- Regulatory pressure is rising. Regulatory authorities have continued to update label language and product guidance in recent years; in particular, new label initiatives and risk communications introduced by regulators have raised both compliance costs and reputational risk for manufacturers and marketers. These changes affect labeling, permissible dose strengths in certain prescription combinations, and post-market surveillance obligations.
- Safety communications are re-shaping clinical positioning. Recent agency-led processes seeking label revisions to reflect potential neurodevelopmental associations and severe skin reaction warnings have increased the intensity of clinician and consumer conversations. Strategic responses should blend evidence-based communications, risk-mitigation product design, and patient-education programs to preserve trust and market share.
- Supply concentration creates leverage and vulnerability. A large proportion of global API and upstream intermediates are sourced from a limited set of geographic suppliers. This creates both sourcing leverage for well-positioned incumbents and fragility for firms without dual sourcing or secure long-term agreements. Supply continuity planning and localized inventory strategies will be central to cost-of-goods management in 2026.
- Reimbursement and clinical guidance afford niche advantages. Acetaminophen retains unique positioning in certain therapeutic uses — for example, regulatory acceptance for specific populations — creating durable pockets where formulary and clinical preference decisions can be leveraged for premium positioning.
- Market concentration is meaningful but not prohibitive. The market shows a mid-level degree of concentration: the top three and top five players account for material but not dominant shares, leaving room for agile entrants and specialized suppliers to capture share via cost, innovation, or channel partnerships.
Strategic priorities for executives in 2026
- Portfolio rationalization with an eye to regulatory resilience. Reassess SKU breadth against new labeling and dose-limit regimes. Rationalize lower-margin SKUs where regulatory risk or monitoring costs are disproportionate to revenue contribution, and reallocate resources to formulations and channels with defensible clinical or brand positions.
- Supply-chain reconfiguration. Implement multi-sourcing for critical intermediates, secure standing inventory commitments for key markets, and consider near-shoring selective production to reduce geopolitical and logistics risk. Evaluate strategic toll manufacturing and contract-manufacturing partnerships as part of a blended resilience model.
- Clinical and safety communications capability. Invest in evidence generation and clinician engagement to maintain prescriber confidence, especially where safety narratives are evolving. Turn pharmacovigilance and real-world evidence into a competitive asset rather than merely a compliance obligation.
- Value-based commercial models. For channels where OTC commoditization pressures margins, pursue value-add plays: bundled maternal/childcare products, digital dosing aids, or subscription-delivery services tied to adherence and safety tracking.
- M&A and capacity plays. Use the current market structure and cash-flow profile to identify targets: API manufacturers with excess capacity, regional branded franchises with strong OTC loyalty, and specialty formulation houses that can accelerate entry into liquid or pediatric formats.
Competitive landscape — where incumbents are vulnerable and where they are strong
We evaluated the competitive set across brand owners, generic manufacturers, and API suppliers. Large consumer-health incumbents retain advantages in brand equity and channel reach; generic manufacturers and API producers compete on cost and supply reliability. Our analysis of the principal market participants surfaces three strategic archetypes:
- Global brand owners with portfolio breadth and channel strength. These firms monetize brand premiums in key markets through marketing scale and distribution muscle. Their strategic challenge in 2026 will be balancing reputational management with pricing discipline as label scrutiny intensifies.
- Generic and contract manufacturers competing on cost and flexibility. These players capitalize on production scale and supply contracts; their principal risk is margin compression when raw-material availability becomes tight and when regulatory compliance costs increase.
- API-focused suppliers and vertically integrated manufacturers. Firms that control upstream production can capture margin and buffer downstream partners in a supply-constrained environment, making them attractive strategic partners or acquisition targets.
For decision-makers: prioritize relationships with suppliers that demonstrate proven quality systems and dual-country manufacturing footprints; similarly, aim to differentiate consumer-facing offerings via evidence-backed safety communications and targeted brand messaging.
What the full PW Consulting report delivers (practical, decision-ready content)
- Detailed, audited market model (2020–2032) with selectable scenarios and sensitivity levers for price, volume, and regulatory shocks. The model is delivered in an editable format to integrate corporate assumptions.
- Segment-level revenue and growth dynamics across geography, dosage form, and application — plus an interactive dashboard that maps opportunities by margin profile and regulatory exposure. (Note: segmentation granularity is intentionally gated in this preview.)
- Supplier heatmap and procurement playbook: risk scores for top API and intermediate suppliers, lead-time matrices, and contracting recommendations to de-risk 12–36 month supply horizons.
- Regulatory tracker and impact assessment: rolling matrix of recent regulatory actions, probable next steps, and quantified impact on labeling, packaging, and post-market activity costs.
- M&A screening list with financial and operational filters: prioritized targets for capacity acquisition, brand extension, and cost synergy capture, including modeled payout timelines under conservative and aggressive integration scenarios.
- Commercial playbooks for incumbents and challengers: channel-specific tactics, pricing frameworks, launch checklists for new formulations, and brand-defense strategies when safety narratives escalate publicly.
Scenario highlights — why contingency planning matters in 2026
Our scenarios stress-test three plausible futures: a baseline path aligned with the central 4.7% CAGR, a conservative path where tighter labeling and constrained supply cap growth temporarily, and an upside path driven by successful product innovation and supply diversification. The differences among these paths are not academic: they translate into materially different capital allocation and inventory strategies. Firms that adopt a probabilistic planning mindset reduce downside exposure and retain optionality to capture upside.
How to use this briefing with your 2026 planning cycle
- Board and Executive Workshops: Use our scenario outputs to frame capital allocation choices and board-level risk tolerances prior to finalizing 2026 budgets.
- M&A diligence: Apply our supplier heatmap and target filters to shorten due diligence timelines and to price contingent liabilities associated with regulatory exposure.
- Procurement strategy: Integrate our supply-risk scoring into procurement KPIs and supplier scorecards to secure near-term continuity while negotiating longer-term preferred arrangements.
- Brand and medical affairs: Deploy our recommendations on clinician engagement and safety-communication to pre-empt reputational erosion in sensitive markets.
Closing guidance — convert insight into defensible advantage
In aggregate, the acetaminophen market in 2026 is neither a boomtown nor a minefield — it is a mature market undergoing concentrated change. The path to above-market returns lies in anticipating regulatory shifts, codifying supply resilience, and pivoting commercial models from volume-only plays to value-driven propositions. Our full report equips executive teams with the models, scenario analysis, and executable playbooks needed to make defensible decisions in 2026 and beyond.
To obtain the comprehensive dataset, segmentation detail, and the full suite of strategic tools referenced in this briefing, access the complete PW Consulting Acetaminophen Market report and model. The full deliverable provides the granular inputs necessary to translate these insights into board-ready action plans.
For detailed analysis of this topic, please visit the official page: Acetaminophen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com