

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Natural Refrigerants Market to Reach USD 2,570M by 2032 (6.1% CAGR)

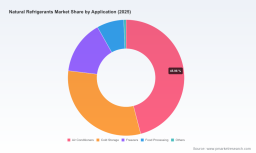
Natural Refrigerants Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact introduction to our latest market study on Natural Refrigerants. This briefing is crafted for executive teams, corporate strategists, and investment committees preparing decisions in 2026. It highlights the actionable implications of our research while deliberately reserving the granular segment-level figures for the full report — a design choice intended to protect high-value insights and to guide readers to the complete dataset and modeling on our website.
Natural Refrigerants Market
Market snapshot: Where the market stands and where it’s headed
Natural refrigerants are no longer a niche substitution; they are a core technology vector in refrigeration and air-conditioning systems, driven by regulatory pressure, component innovation, and shifting total-cost-of-ownership dynamics. PW Consulting’s base-year assessment (2025) values the global natural refrigerants market at approximately USD 1,700 Million (revenue unit: Million USD). Under our central forecast, the sector is expected to expand at a compound annual growth rate (CAGR) of 6.1% through the 2026–2032 forecast window, reaching roughly USD 2,570 Million by 2032.
Natural Refrigerants Market
That growth trajectory is uneven — influenced by regulatory shifts, feedstock price volatility, and a cadence of product introductions and component availability — but it is robust enough to shift capital allocation decisions across manufacturing, distribution, and service segments in 2026.
Natural Refrigerants Market
Why this report matters for 2026 strategy
- Regulatory inflection points demand action: New and updated regulations have already reshaped permissible refrigerant choices in core end markets. Companies that treat 2026 as a planning inflection — aligning product portfolios, distribution contracts, and retrofit strategies to predictable regulatory paths — will avoid costly rework and gain first-mover advantages.
- Supply-chain fragility is now strategic risk: Raw-material cost spikes and logistic disruptions can erode margins quickly. The report translates commodity and feedstock dynamics into probabilistic risk scenarios and mitigation playbooks that are directly deployable in procurement and sourcing decisions.
- Technological differentiation is actionable: Advances in compressors, component integration, and system-level controls enable manufacturers to outperform on efficiency and lifecycle cost in 2026 procurement contests. We map those technologies to commercial readiness and value capture potential.
- Market sizing to prioritize CAPEX: With a clear macro projection and confidence intervals, finance teams can calibrate investment thresholds for manufacturing expansions, JV formation, or M&A — without relying solely on anecdotal supplier pitches.
What the PW Consulting report delivers (practical, decision-ready content)
- Executive dashboards: A top-line market model (base year 2025, forecast 2026–2032) with scenario toggles for regulation, feedstock cost, and adoption rate. Use this to stress-test revenue and margin assumptions in board deliberations.
- Go-to-market and channel playbooks: Segmented strategies for OEMs, distributors, and aftermarket service providers that prioritize near-term wins and durable revenue streams.
- Regulatory scenario maps: Four plausible regulatory pathways and the operational and product readjustments each requires — mapped to implementation timelines that matter for 2026 procurement cycles.
- Supply-chain and raw-material risk matrices: Detailed supplier mapping, single-point-of-failure diagnostics, and hedging options tied to ammonia and hydrocarbon supply dynamics.
- Technology adoption roadmaps: Component- and system-level adoption curves for CO2, ammonia, and hydrocarbons, including retrofit compatibility and serviceability considerations.
- Investment screening toolkit: A practical framework (IRR and payback lenses) for evaluating brownfield upgrades versus greenfield projects, calibrated to the market’s projected 6.1% CAGR and our revenue model.
Each of these modules is accompanied by reproducible models, data appendices, supplier scorecards, and implementation checklists — intentionally packed with enough specificity to act on, while the full segmented datasets and proprietary inputs remain available in the complete report.
Competitive landscape: players to watch and strategic implications
The market structure shows moderate concentration: top-tier players capture a meaningful share without creating an impenetrable oligopoly (our CR3/CR5 analysis shows a similar concentration metric, indicating room for regional specialists and innovative entrants to scale). Competitive dynamics in 2026 will be defined by three behaviors: vertical integration, component-system bundling, and aftermarket service capture.
- Linde Group (Ireland): A leading supplier with deep industrial CO2 capabilities and broad service footprints. Strategic implication: expect continued emphasis on system-level partnerships with OEMs and large end-users; an attractive counterparty for large-scale refrigeration projects and CO2 supply contracts.
- Airgas Inc. (United States): Major distributor with national logistics advantages. Strategic implication: distribution network and emergency supply service levels will be key differentiators in North American procurement.
- Sinochem, Dongyue, Juhua, and other integrated Chinese producers: These players combine manufacturing scale with integrated feedstock access. Strategic implication: competitive pricing pressure in commoditized segments and rapid ramp-up capacity for certain refrigerant types.
- Puyang Zhongwei, Shandong Yuean, and similar specialty producers: Focused producers who can flex to niche industrial needs. Strategic implication: attractive for regional partnerships and co-development, especially where regulatory and safety codes vary.
- Tazzetti, A-Gas, Secop, Hoshizaki, PRO Refrigeration, Sanhua, and Secop Group partners: Equipment and component suppliers that push refrigeration architectures through compressor innovation, integrated component kits, and product line expansions. Strategic implication: OEMs should prioritize supplier roadmaps that align with their chosen refrigerant strategy to avoid costly redesign cycles.
Recent market moves underscore this dynamic. In 2025 several notable product and portfolio expansions were announced, including PRO Refrigeration’s CO2 chiller for North American food processing (July 2025), Hoshizaki’s substantial lineup expansion (November 2025), and component-package releases by Sanhua mapped to a 2025–2030 roadmap. These actions signal accelerating commercialization and a widening set of viable system options for buyers in 2026.
Regulation, feedstock and price volatility — the three-headed headwind
Regulation remains the principal accelerant for adoption. Since January 1, 2025, U.S. EPA HFC phasedown rules have tightened permissible refrigerant choices in residential, light-commercial and retail food equipment; the EU’s updated F-Gas rules (Regulation 2024/573) have further complicated compliance matrices for certain commercial applications. At the same time, targeted enforcement windows and temporary extensions — for example, the EPA’s no-action assurance extension for refrigerated transport through September 1, 2026 — introduce tactical timing opportunities for firms managing fleet refreshes and retrofit programs.
Operationally, feedstock cost swings are a near-term margin risk. Ammonia prices surged to 2025 highs due to supply constraints and volatile natural gas feedstock, and market intelligence shows continued price elevation into 2026 (U.S. Gulf Coast anhydrous ammonia prices averaged around the levels reported in April 2026). For procurement teams this means implementing dynamic sourcing, longer-term offtake clauses where possible, and scenario-based pass-through mechanisms in contracts.
Strategic moves for 2026 — a checklist
- Product portfolio triage: Segregate SKUs into “must-upgrade,” “monitor,” and “decommission” buckets based on regulatory exposure and retrofit feasibility.
- Supply resilience investments: Negotiate medium-term supply contracts with tiered pricing triggers, diversify feedstock sources, and explore nearshoring components for critical compressor and valve parts.
- Partnership acceleration: Lock strategic supplier partnerships that bundle components with commissioning and aftermarket service guarantees — these deals are being priced as a premium in 2026 tenders.
- Commercial pilots: Deploy controlled rollouts in regulatory-friendlier jurisdictions to validate system designs and gather real-world TCO data ahead of wider market rollouts.
- Service and retrofit monetization: Build aftermarket offerings (retrofit kits, performance guarantees, training) to monetize the installed base in a period of regulatory transition.
How to use this briefing and next steps
This briefing is a strategic “trailer” — it highlights what matters and why, and it points toward where to find the operative levers. For teams preparing 2026 capital plans, procurement strategies, or M&A screens, the full PW Consulting Natural Refrigerants Market report provides the calibrated segment-level data, supplier scorecards, and downloadable models that convert insight into executable plans.
Accessing the full study will enable you to:
- Apply our scenario models to your specific revenue and margin assumptions;
- Identify priority regions, applications, and refrigerant types for targeted investment (segmental data and heatmaps are available in the report);
- Download supplier evaluation templates and negotiation playbooks tailored to the market conditions described above.
PW Consulting stands ready to support board workshops, bespoke scenario modeling, and supplier due diligence in 2026. For decision-makers who need to convert regulatory pressure and commodity volatility into strategically timed investments, our report and advisory services are designed to accelerate confident action while minimizing execution risk.
For detailed analysis of this topic, please visit the official page: Natural Refrigerants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com