

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acetaminophen Market Set for 4.7% CAGR (2026–2032) — Demand Shifts Ahead

Acetaminophen Market 2026: Strategic Intelligence Briefing
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking narrative designed to orient executive teams, corporate strategy committees, and private equity sponsors preparing decisions in 2026. This briefing synthesizes our latest Acetaminophen Market research — a data-driven, scenario-ready resource built on a 2020–2025 historical base and a 2026–2032 forecast horizon. It highlights the practical strategic levers that will determine winners and laggards in a market characterized by steady expansion, regulatory attention, and supply-chain concentration.
Acetaminophen Market
Market Snapshot — what the headline numbers mean for strategy
By our base-year accounting (2025), the global acetaminophen market stands at approximately USD 10,500 Million, after a recovery and expansion period through 2020–2025. Our forecast shows a compound annual growth rate (CAGR) of roughly 4.7% across 2026–2032, with the market progressing toward a projected value in excess of USD 14 billion by 2032. This trajectory reflects a combination of durable OTC demand, continued use in prescription combination products, and growth in emerging geographies and formulation formats.
Acetaminophen Market
These headline numbers mask an important strategic truth: modest aggregate growth does not translate into uniform opportunity. Market expansion is being driven by a mix of demographic tailwinds, shifting clinical guidance, and differentiated product-level dynamics that create localized pockets of high-return activity. Effective 2026 strategies will therefore be those that convert macro stability into micro advantage — via targeted portfolio choices, resilient sourcing, and defensible go-to-market models.
Acetaminophen Market
Why this research matters for 2026 decision-making
- Actionable market sizing with scenario overlays: Our model provides a baseline and multiple stress-tested paths (regulatory tightening, supply shock, and substitution scenarios). That lets commercial teams quantify upside and downside to 2032 before committing capital.
- Regulatory early-warning and compliance roadmaps: The pace of labeling and usage guidance changes has accelerated. Our report maps regulatory actions to product- and geography-level commercial impacts to prioritize mitigation and opportunity responses.
- Supply-chain risk quantified: With material supply concentration in a small number of producing geographies for active pharmaceutical ingredient (API), our supplier risk heatmap correlates exposure with cost, lead-time, and substitution difficulty — a necessary input into any 2026 sourcing decision.
- Competitive positioning and M&A playbook: We analyze incumbent portfolios and manufacturing footprints to identify attractive consolidation targets, capacity plays, and brand-specified arbitrage opportunities.
Key dynamics shaping 2026 strategic choices
- Regulatory pressure is rising. Regulatory authorities have continued to update label language and product guidance in recent years; in particular, new label initiatives and risk communications introduced by regulators have raised both compliance costs and reputational risk for manufacturers and marketers. These changes affect labeling, permissible dose strengths in certain prescription combinations, and post-market surveillance obligations.
- Safety communications are re-shaping clinical positioning. Recent agency-led processes seeking label revisions to reflect potential neurodevelopmental associations and severe skin reaction warnings have increased the intensity of clinician and consumer conversations. Strategic responses should blend evidence-based communications, risk-mitigation product design, and patient-education programs to preserve trust and market share.
- Supply concentration creates leverage and vulnerability. A large proportion of global API and upstream intermediates are sourced from a limited set of geographic suppliers. This creates both sourcing leverage for well-positioned incumbents and fragility for firms without dual sourcing or secure long-term agreements. Supply continuity planning and localized inventory strategies will be central to cost-of-goods management in 2026.
- Reimbursement and clinical guidance afford niche advantages. Acetaminophen retains unique positioning in certain therapeutic uses — for example, regulatory acceptance for specific populations — creating durable pockets where formulary and clinical preference decisions can be leveraged for premium positioning.
- Market concentration is meaningful but not prohibitive. The market shows a mid-level degree of concentration: the top three and top five players account for material but not dominant shares, leaving room for agile entrants and specialized suppliers to capture share via cost, innovation, or channel partnerships.
Strategic priorities for executives in 2026
- Portfolio rationalization with an eye to regulatory resilience. Reassess SKU breadth against new labeling and dose-limit regimes. Rationalize lower-margin SKUs where regulatory risk or monitoring costs are disproportionate to revenue contribution, and reallocate resources to formulations and channels with defensible clinical or brand positions.
- Supply-chain reconfiguration. Implement multi-sourcing for critical intermediates, secure standing inventory commitments for key markets, and consider near-shoring selective production to reduce geopolitical and logistics risk. Evaluate strategic toll manufacturing and contract-manufacturing partnerships as part of a blended resilience model.
- Clinical and safety communications capability. Invest in evidence generation and clinician engagement to maintain prescriber confidence, especially where safety narratives are evolving. Turn pharmacovigilance and real-world evidence into a competitive asset rather than merely a compliance obligation.
- Value-based commercial models. For channels where OTC commoditization pressures margins, pursue value-add plays: bundled maternal/childcare products, digital dosing aids, or subscription-delivery services tied to adherence and safety tracking.
- M&A and capacity plays. Use the current market structure and cash-flow profile to identify targets: API manufacturers with excess capacity, regional branded franchises with strong OTC loyalty, and specialty formulation houses that can accelerate entry into liquid or pediatric formats.
Competitive landscape — where incumbents are vulnerable and where they are strong
We evaluated the competitive set across brand owners, generic manufacturers, and API suppliers. Large consumer-health incumbents retain advantages in brand equity and channel reach; generic manufacturers and API producers compete on cost and supply reliability. Our analysis of the principal market participants surfaces three strategic archetypes:
- Global brand owners with portfolio breadth and channel strength. These firms monetize brand premiums in key markets through marketing scale and distribution muscle. Their strategic challenge in 2026 will be balancing reputational management with pricing discipline as label scrutiny intensifies.
- Generic and contract manufacturers competing on cost and flexibility. These players capitalize on production scale and supply contracts; their principal risk is margin compression when raw-material availability becomes tight and when regulatory compliance costs increase.
- API-focused suppliers and vertically integrated manufacturers. Firms that control upstream production can capture margin and buffer downstream partners in a supply-constrained environment, making them attractive strategic partners or acquisition targets.
For decision-makers: prioritize relationships with suppliers that demonstrate proven quality systems and dual-country manufacturing footprints; similarly, aim to differentiate consumer-facing offerings via evidence-backed safety communications and targeted brand messaging.
What the full PW Consulting report delivers (practical, decision-ready content)
- Detailed, audited market model (2020–2032) with selectable scenarios and sensitivity levers for price, volume, and regulatory shocks. The model is delivered in an editable format to integrate corporate assumptions.
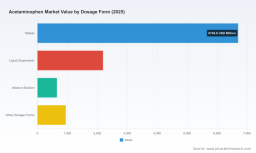
- Segment-level revenue and growth dynamics across geography, dosage form, and application — plus an interactive dashboard that maps opportunities by margin profile and regulatory exposure. (Note: segmentation granularity is intentionally gated in this preview.)
- Supplier heatmap and procurement playbook: risk scores for top API and intermediate suppliers, lead-time matrices, and contracting recommendations to de-risk 12–36 month supply horizons.
- Regulatory tracker and impact assessment: rolling matrix of recent regulatory actions, probable next steps, and quantified impact on labeling, packaging, and post-market activity costs.
- M&A screening list with financial and operational filters: prioritized targets for capacity acquisition, brand extension, and cost synergy capture, including modeled payout timelines under conservative and aggressive integration scenarios.
- Commercial playbooks for incumbents and challengers: channel-specific tactics, pricing frameworks, launch checklists for new formulations, and brand-defense strategies when safety narratives escalate publicly.
Scenario highlights — why contingency planning matters in 2026
Our scenarios stress-test three plausible futures: a baseline path aligned with the central 4.7% CAGR, a conservative path where tighter labeling and constrained supply cap growth temporarily, and an upside path driven by successful product innovation and supply diversification. The differences among these paths are not academic: they translate into materially different capital allocation and inventory strategies. Firms that adopt a probabilistic planning mindset reduce downside exposure and retain optionality to capture upside.
How to use this briefing with your 2026 planning cycle
- Board and Executive Workshops: Use our scenario outputs to frame capital allocation choices and board-level risk tolerances prior to finalizing 2026 budgets.
- M&A diligence: Apply our supplier heatmap and target filters to shorten due diligence timelines and to price contingent liabilities associated with regulatory exposure.
- Procurement strategy: Integrate our supply-risk scoring into procurement KPIs and supplier scorecards to secure near-term continuity while negotiating longer-term preferred arrangements.
- Brand and medical affairs: Deploy our recommendations on clinician engagement and safety-communication to pre-empt reputational erosion in sensitive markets.
Closing guidance — convert insight into defensible advantage
In aggregate, the acetaminophen market in 2026 is neither a boomtown nor a minefield — it is a mature market undergoing concentrated change. The path to above-market returns lies in anticipating regulatory shifts, codifying supply resilience, and pivoting commercial models from volume-only plays to value-driven propositions. Our full report equips executive teams with the models, scenario analysis, and executable playbooks needed to make defensible decisions in 2026 and beyond.
To obtain the comprehensive dataset, segmentation detail, and the full suite of strategic tools referenced in this briefing, access the complete PW Consulting Acetaminophen Market report and model. The full deliverable provides the granular inputs necessary to translate these insights into board-ready action plans.
For detailed analysis of this topic, please visit the official page: Acetaminophen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com