

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 4,4‑Biphenol Market to Reach USD 258.5M by 2032 at 7.23% CAGR

4,4'-Biphenol Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
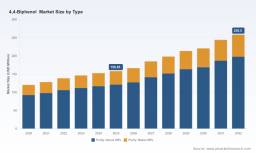
As 2026 begins, the global 4,4'-Biphenol market stands at an inflection point. Our PW Consulting base-year assessment (2025) and multi-year model show a market that has expanded from approximately USD 120.5 Million in 2020 to USD 158.6 Million in 2025, and that is forecast to continue growing at a compound annual growth rate (CAGR) of 7.23% through 2032, reaching roughly USD 258.5 Million by the end of the projection window. These headline metrics capture both steady end-market adoption and the structural shifts in polymer demand, regulatory visibility, and supplier consolidation that will determine winners and losers in the coming three to five years.
4,4-Biphenol Market
Why this preview matters for 2026 strategy
-
Timing investments: A mid-single-digit to low-double-digit CAGR across 2026–2032 signals predictable volume growth but with pockets of higher volatility tied to advanced polymers (e.g., liquid crystal polymers, high-performance polysulfones). Buyers, producers and investors must align capital deployment to capture specific application upcycles rather than betting on uniform expansion.
4,4-Biphenol Market -
Margin management: As demand matures, pricing will be driven more by purity grade differentials, batch reliability, and service levels than by feedstock swings alone. Companies with validated high-purity manufacturing and robust quality systems will preserve premium positioning; newcomers should assess margin dilution risk from commoditization before scaling.
4,4-Biphenol Market -
Regulatory and supply certainty: Emerging regulatory scrutiny and evolving trade classifications make proactive compliance and tariff-aware sourcing a strategic imperative. The market’s growth trajectory provides opportunity, but unmanaged regulatory exposure can erode returns and time-to-market.
What our full study delivers — practical, transaction-ready intelligence
PW Consulting’s 4,4'-Biphenol market study is deliberately operational: it is built for commercial teams, M&A advisors, and strategic planners who must make decisive commitments in 2026. Highlights include:
-
A transparent demand model spanning 2020–2032 with unit demand drivers by polymer family, manufacturer-level capacity overlays, and a price-quantity matrix calibrated to historical trade flows.
-
Scenario-based forecasts that stress-test outcomes under differing regulatory treatments, raw-material shocks, and accelerated electronic-vehicle/medical device adoption.
-
An investment diagnostic for capacity expansion or debottlenecking: NPV sensitivity tables, payback intervals at alternative purity-premia, and capital-efficiency benchmarks drawn from recent project disclosures.
-
Commercial playbooks for suppliers and buyers — including contracting templates that address purity, traceability, and transport classification risks — and an action checklist for due-diligence in supplier audits and JV negotiations.
-
A red-team risk register covering environmental, health, and trade implications: regulatory watch-items, likely enforcement scenarios, and practical mitigation steps for 12–36 month horizons.
Note: this preview intentionally omits granular segmentation tables and specific regional/application dollar splits to preserve the report’s subscriber value. The full report contains the detailed split information and supplier-level data that commercial teams require for closed-loop decision-making.
Market structure and competition — what matters in 2026
The 4,4'-Biphenol market is moderately concentrated. Our concentration metrics indicate that the top three suppliers account for a significant majority of market volume, and the top five expand that share further. This concentration creates a market where strategic moves by a few players can rapidly reshape access, price dynamics, and contractual norms.
Key incumbent profiles we analyze in depth include:
-
Chimei Plastic (Taiwan) — An established producer of high-purity 4,4'-Biphenol positioned as a plastic and rubber additive and polymer precursor. Their strengths are scale and established commercial relationships in adjacent polymer value chains. (Product link available in the full report.)
-
Honshu Chemical Industry Co., Ltd. (Japan) — Focused on monomers for liquid crystal polymers and high-performance polysulfone families, Honshu is notable for its technology alignment to electronics, telecoms and medical device OEMs.
-
SII Group (Japan) — Supplies 4,4'-Biphenol to several engineering-plastics value chains including LCPs and polyarylether ketones. Their product strategy emphasizes functional monomers and collaborative R&D with downstream compounders.
-
Ascent Petrochem Holdings (China) — An industrial-scale manufacturer with ISO 9001 compliance and availability of 99%+ purity grades. They represent the capacity-led segment that competes on price and availability for large polymer makers.
-
Anhui Liwei Chemical (China) — A certified factory with batch traceability and strict quality protocols, serving polymer producers that require documented material provenance and auditability.
Strategic takeaway: incumbents combine scale, geographic reach and product-grade depth. New entrants should not expect to win on price alone; targeted partnerships with end-users, niche purity differentiation, or licensing of synthesis routes will be necessary to secure enterable niches.
Regulatory dynamics and near-term policy risk
Policy developments through 2024–2026 show a mix of increased visibility without sweeping new bans — an environment of “watch and adjust.” The report highlights several regulatory factors that merit active monitoring:
-
U.S. TSCA listings include 4,4'-Biphenol among substances subject to persistent monitoring discussions, particularly under PBT considerations. While no targeted U.S. federal restrictions took effect through early 2026, prospective assessments could alter compliance costs for certain suppliers.
-
Trade treatment is supportive in some jurisdictions: relevant tariff schedules for certain chemical classifications show duty-free treatment at the time of publication, which lowers an important cost barrier for cross-border commercial strategies.
-
Food-contact and medical-device pathways: 4,4'-Biphenol appears in Food Contact Substance notifications as a monomer in specific copolymers, and several high-performance polymer applications maintain visibility with regulatory bodies. These approvals open premium, regulated end-markets but require depth in compliance and traceability documentation.
-
Transport and safety data sheets (SDS) continue to list standard GHS classifications and R&D-use-notes in some jurisdictions. Companies scaling to larger batches must ensure supply-chain safety data coherence to avoid shipment delays and customs friction.
Implication for 2026: regulatory tracking should be embedded in commercial planning. Even absent immediate bans, incremental reporting, testing, or labeling requirements can increase product cost-in-use and contract complexity.
Commercial strategies that our clients are executing
-
Securing offtake agreements with purity-linked price ladders. Firms are negotiating contracts that mirror polymer conversion economics rather than simple spot pricing.
-
Vertical collaboration: manufacturers are co-investing with compounders and OEMs to validate downstream performance and accelerate qualification cycles for LCP and medical-grade polymers.
-
Manufacturing resilience: selective capacity expansions are paired with process intensification to preserve margins while meeting quality specifications, avoiding overexposure to commodity pricing pressures.
-
Regulatory arbitrage and sourcing optimization: procurement teams are diversifying supplier lists across tariff regimes and maintaining documented compliance dossiers to streamline cross-border movements.
How to use this preview in boardroom decisions
For CFOs evaluating capital allocation, the clear growth path at a 7.23% CAGR justifies staged investments with go/no-go gates tied to purity-premium realization and secured offtake. For Chief Commercial Officers, the consolidation metrics indicate that access to a top-tier supplier or a strategic alliance can be a force-multiplier. For R&D and product teams, the uptick in regulated end-uses implies that upstream quality controls and traceability will be de facto market entry barriers for higher-value polymer applications.
Next steps — where PW Consulting adds value
-
Request the full report to access proprietary segmentation, supplier-level volume and pricing matrices, and the scenario tool that quantifies NPV outcomes under alternative regulatory and demand pathways.
-
Commission a tailored rapid due-diligence: we can map a target supplier’s operational, regulatory and commercial fit to your specific polymer conversion needs within a two-week engagement.
-
Engage our market-entry playbook workstream to craft contracting structures, quality-spec annexes and logistic routes that materially shorten qualification timelines for regulated applications.
Conclusion: The 4,4'-Biphenol market presents a disciplined growth story with concentrated supplier power and rising regulatory attention. For 2026, strategic clarity comes from matching the timing and structure of investments to the nuanced dynamics of purity grading, application qualification cycles, and regulatory compliance. PW Consulting’s full study equips decision-makers with the granular inputs and executable recommendations necessary to convert market expansion into durable advantage.
For detailed analysis of this topic, please visit the official page: 4,4-Biphenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com