

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
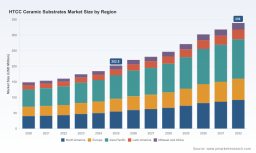
PW Consulting: HTCC Ceramic Substrates Market to hit USD 339.0M by 2032 at 7.65% CAGR

HTCC Ceramic Substrates Market — Strategic Briefing for 2026 Decision-Makers
Executive overview
As semiconductor packaging complexity and high-reliability electronics converge, High-Temperature Co-fired Ceramic (HTCC) substrates are emerging as a strategic material choice across telecommunications, automotive electrification, industrial controls, and harsh-environment sensing. PW Consulting’s HTCC Ceramic Substrates Market study (base year 2025; historical 2020–2025; forecast 2026–2032) quantifies this transition and translates it into actionable guidance for 2026 corporate planning.
HTCC Ceramic Substrates Market
At the aggregate level, the market’s trajectory is clear: the industry expanded steadily from a modest base in 2020 to approximately USD 202.8 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.65% through 2032, reaching roughly USD 339.0 Million by the end of the forecast window. This combination of durable near-term demand and healthy medium-term momentum creates a window for investment, capacity rationalization, vertical integration, and targeted partnerships — but also raises important sourcing and pricing considerations that every C-suite should factor into 2026 strategy.
HTCC Ceramic Substrates Market
Why this report matters for 2026 decisions
-
Timing for capacity and product investments: With a mid-single-digit-to-high-single-digit CAGR and clear end-market pull, the next 12–18 months are pivotal for firms choosing between brownfield capacity expansion, greenfield projects, or capability-focused M&A. Our analysis maps demand inflection points across the forecast period so executives can align capital deployment with the most attractive time windows.
HTCC Ceramic Substrates Market -
Risk-aware sourcing strategies: Raw-material volatility and regional supply idiosyncrasies materially influence margin outcomes. The report identifies supply-chain levers and hedging options that can protect gross margin while preserving flexibility for product customization.
-
Competitive positioning and consolidation plays: The market exhibits meaningful concentration among established specialty players. Understanding competitive strengths and gaps — from hermetic sealing and multilayer integration to specialty formulations and high-reliability military/aerospace qualifications — is necessary to craft acquisition targets, JV partners, or differentiation strategies.
Market dynamics — what is driving change
Three interlocking forces are shaping the HTCC substrate landscape in 2026:
-
End-market complexity and reliability demands. Higher-frequency telecom architectures, power-dense EV power electronics, and downhole/aerospace sensing all favor HTCC’s thermal and mechanical stability. Buyers are moving from off-the-shelf commodity substrates toward engineered solutions that embed thermal vias, multilayer routing, and hermetic package options.
-
Raw-material and cost pressure. Key upstream materials remain a source of uncertainty. For example, bauxite consumption rose in 2025 and metallurgical alumina import pricing sits materially higher than prior years; concurrently, primary metal manufacturing cost indices saw a sharp increase in 2024. These inputs feed through to ceramic formulations and processing costs and require active procurement management and, in some cases, design-for-cost initiatives.
-
Geopolitical and regional capacity dynamics. Idle alumina refinery capacity in certain markets has not been reactivated, creating pockets of regional supply tightness. Manufacturers that can manage cross-border logistics and adapt their material choices without compromising reliability gain a tactical advantage.
Segmentation and demand themes (high level)
The report dissects demand along the classic axes — material type, end-application, and geography — and links each to procurement and technology actions that matter for 2026. Rather than publishing raw subsegment values in this summary, we highlight the conceptual implications:
-
By material type: HTCC formulations commanding the highest-value, high-reliability applications require investment in process control, multilayer lamination, and advanced metallization. LTCC and other ceramics remain relevant for cost-sensitive or lower-temperature applications, creating a natural tiering of addressable market opportunities.
-
By application: Telecommunications (including next-generation radio infrastructure), power electronics for electric vehicles, consumer electronics at the high-frequency edge, and industrial/secure sensing are each stimulating different technical requirements. Commercial decisions — e.g., pursuing automotive-grade qualification vs. focusing on telecom RF — lead to distinct CAPEX and certification roadmaps.
-
By geography: Regional demand pockets and supply-chain realities (from raw material availability to labor and energy costs) affect where to site capacity and how to design inventory buffers. The full report provides scenario-based geographies for plant placement and distribution network design.
Competitive landscape — who matters and why
The HTCC market is specialized: a handful of capable players control a meaningful share of revenue and technological know-how, creating both partnership opportunities and competitive pressure. Market concentration metrics reinforce that strategic moves by top-tier suppliers ripple across the supply chain.
-
NEOTech (Southern California, USA; https://www.neotech.com): A leading North American HTCC manufacturer with strengths in alumina and aluminum nitride formulations, hermetic sealing, and multilayer capability. NEOTech is a go-to for customers needing high-reliability packaging combined with rapid design iteration.
-
AdTech Ceramics (Chattanooga, TN, USA; https://www.adtechceramics.com): Known for proprietary HTCC blends and expertise in hermetic straight-through vias and dense interconnects. AdTech’s niche focus on military, aerospace, medical, and extreme-temperature applications positions it as a premium partner for qualification-heavy programs.
-
Maruwa Co., Ltd. (Japan; https://www.maruwa-g.com): A producer of alumina multilayer HTCC substrates and packages for sensor packaging, MEMS, optical communications, and LED applications. Maruwa’s engineering depth in multilayer sintering and fine-line metallization is a differentiator for compact, high-performance assemblies.
-
Jimei Materials (Shenzhen, China; https://www.jimei-materials.com): Focused on HTCC substrates for aerospace electronics, MEMS packaging, RF cavities, and downhole sensors. Jimei’s portfolio emphasizes applications in harsh environments and illustrates how regional suppliers can combine scale with specialized technical offerings.
Collectively, the top three to five vendors control a significant share of industry revenues, and their strategic decisions on capacity, qualification timelines, and customer partnerships will materially shape supplier economics in 2026 and beyond.
Report contents — practical elements for implementation
PW Consulting’s full HTCC Ceramic Substrates Market report combines data rigor with practical tools that are directly usable in 2026 planning cycles:
-
360° market sizing and growth scenarios (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity runs that stress-test demand under different macroeconomic and supply-chain shocks.
-
Actionable supplier scorecards: technology capabilities, qualification timelines, capacity footprints, and margin-pressure triggers to help procurement prioritize partners or M&A targets.
-
Cost-to-serve models that translate raw-material index movement into margin scenarios at the product-family level, enabling engineering-to-cost tradeoffs.
-
Segmentation playbooks that map go-to-market choices (e.g., pursuing automotive AEC-Q certification vs. telecom RF performance optimization) to expected time-to-revenue and incremental CAPEX needs.
-
Regulatory and materials risk annex: monitoring schedules for metallurgical input prices, regional refinery capacity shifts, and proposed trade or environmental measures that could alter sourcing strategies.
Strategic implications and recommended actions for 2026
-
Prioritize modular capacity and flexible process platforms. Given input-price uncertainty and variable demand by application, invest in modular lines that can switch between HTCC formulations or shift output between high-margin specialty work and higher-volume runs.
-
Advance vertical integration selectively. For companies with scale, securing upstream alumina supply or investing in strategic stockpiles can be value-accretive. The business case should be stress-tested against the cost-of-capital and the sensitivity of your product mix to alumina price movements.
-
Differentiate through qualification and systems-level partnerships. Winning long-cycle, high-value contracts in aerospace, downhole sensing, or automotive power electronics depends on demonstration of qualification capabilities and reliability. Build co-development agreements with OEMs to lock in long lead times and create switching costs.
-
Develop nimble procurement and hedging policies. Integrate raw-material index monitoring into monthly operations reviews and implement rolling hedges or long-term contracts where pricing signals warrant it.
Conclusion — how to use this briefing
For 2026 strategic planning, the HTCC substrate market presents a mix of predictable growth and tactical uncertainty. The overall market is on a steady upward trajectory, creating attractive windows for investment; concurrently, raw-material and regional supply dynamics demand proactive risk management. PW Consulting’s full report converts these macro realities into decision-ready tools — from supplier scorecards to cost-to-serve analytics — enabling leaders to choose the best mix of build, buy, or partner strategies.
To access the detailed segmentation, supplier benchmarking tables, and scenario spreadsheets that underlie these findings, consult the full PW Consulting HTCC Ceramic Substrates Market report on our website. The executive summary above is intended to orient strategy discussions and surface the most consequential issues; the complete study contains the granular analytics needed to finalize 2026 capital and commercial plans.
For detailed analysis of this topic, please visit the official page: HTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com