

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
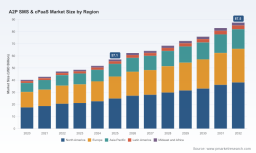
PW Consulting: A2P SMS & cPaaS Market to Hit USD 87.5B by 2032 (6.5% CAGR)

A2P SMS & cPaaS Market 2026: A Strategic Preview for Enterprise Decision‑Makers
Executive summary
As enterprises reassess customer engagement architectures in 2026, A2P SMS and Communications‑Platform‑as‑a‑Service (cPaaS) remain central to digital operations. PW Consulting’s upcoming market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames the space as a mature but evolving ecosystem: after growing through the prior half‑decade, the market sits on a steady long‑run trajectory with a 6.5% CAGR across the forecast window. Our analysis translates that macro momentum into concrete choices for procurement, product strategy, risk management, and M&A posture—without exposing the granular splits that materially inform pricing and negotiation tactics (those are included in the full report available through PW Consulting).
A2P SMS & cPaaS Market
Market trajectory in plain terms
From 2020 through the 2025 base year the A2P SMS & cPaaS market expanded notably, reflecting both re‑platforming by enterprises and steady demand for authentication, transactional messaging, and evolving omnichannel stacks. By the 2025 base year the market had grown substantially from its earlier five‑year position; under our central forecast the market continues to expand through 2032, reaching an elevated scale that reflects the compounding influence of new messaging modalities, enterprise communications modernization, and broader digital identity use cases.
A2P SMS & cPaaS Market
Two headline datapoints to anchor planning: the study uses 2025 as the base year for benchmarking and models a 6.5% compound annual growth rate across 2026–2032. Those assumptions drive our scenario models and stress tests—inputs that procurement, finance, and product teams can use to size budgets and prioritize initiatives through the end of the decade.
A2P SMS & cPaaS Market
Why this matters to enterprise leaders in 2026
-
Procurement and supplier strategy: With vendor concentration moderate (the leading three and five suppliers capture a material but not dominant share of market activity), buyers must balance the cost and speed advantages of large platforms against the specialization and regional reach of smaller providers. Sourcing decisions made in 2026 will lock in multi‑year integration costs and experience design.
-
Product and channel mix decisions: SMS remains the workhorse for transactional and authentication flows; cPaaS investments enable richer, programmable channels. Enterprises must therefore decide where to keep control (in‑house gateways, private connectors) versus where to outsource to managed CPaaS partners—decisions that affect latency, deliverability, and regulatory risk.
-
Cost and energy exposure: Rising data‑center and energy costs are an operational headwind that can change unit economics for high‑volume messaging and real‑time media services. Our report correlates electricity and capacity price trends with marginal cost pressure on cloud and CPaaS providers—critical for financial modeling and supplier negotiation.
-
Regulatory and compliance posture: The regulatory characterization of messaging services—shaped by precedent decisions—continues to affect out‑of‑band obligations, recordkeeping, and interconnection practices. Enterprises must bake compliance into SLA and indemnity clauses with vendors, especially for authentication and identity flows.
-
Resilience and fraud mitigation: Carrier‑level filtering, spam mitigation, and fraud detection are front‑line risks. Selecting partners with demonstrable deliverability performance and anti‑fraud tooling is as important as price per message when the reputation of sender IDs and throughput caps can vary by market.
What the PW Consulting report delivers (practical components)
-
Decision‑ready vendor scorecards: Comparative assessments across capability, coverage, compliance, roadmap maturity, integration complexity, and commercial model. These scorecards are built to plug into RFP and vendor selection processes.
-
Negotiation playbooks and contract checklists: Clause‑level guidance for service levels, audit rights, data residency, porting and number management, indemnities for deliverability, and price escalator mechanisms.
-
Scenario financial models: TCO templates and scenario outputs that use the study’s 6.5% CAGR baseline and optional upside/downside cases so CFOs and FP&A teams can stress test budgets and evaluate build vs buy.
-
Implementation and migration blueprints: Step‑by‑step guidance for moving authentication, transactional, and engagement traffic to new platforms—includes runbook items for carrier onboarding, number management, A/B deliverability testing, and regulatory sign‑offs.
-
Go‑to‑market and monetization playbooks: For product teams seeking to leverage CPaaS capabilities—templates for packaging messaging bundles, usage tiers, and billing constructs that preserve margin while unlocking growth.
-
Risk and resilience maps: Operator and regional risk heatmaps, concentrated dependency assessments, and contingency plans for supply disruption and energy shocks.
Competitive landscape: who matters and why
The sector is populated by a mix of global platform leaders, operator‑scale carriers with messaging arms, and specialized challengers. Each category creates distinct risks and opportunities for enterprise buyers.
-
Global platform leaders (e.g., Twilio): These vendors excel at developer ecosystems, rich APIs, and global reach. The value they bring is speed to market, breadth of integrations, and strong product roadmaps—offset by relatively higher cost and potential vendor lock‑in for complex use cases.
-
Omnichannel and operator‑aligned providers (e.g., Infobip, Sinch, Tata Communications, Route Mobile): These firms combine deep regional operator relationships with omnichannel stacks, making them effective where local carrier certification and regulatory nuance are decisive. They are attractive for enterprises needing regional deliverability and managed onboarding at scale.
-
Communications and UCaaS incumbents (e.g., Vonage, RingCentral): These vendors differentiate by integrating messaging with broader unified communications portfolios—useful for organizations seeking a single vendor for contact center, voice, and messaging.
-
Network‑centric and API specialists (e.g., Bandwidth, Plivo, Mitto, OpenMarket, CM.com): Often stronger on network ownership, number management, and cost engineering, these players can be advantageous for high‑volume transactional traffic or for enterprises that require more control over routing and SS7/ SMPP relationships.
-
Specialized challengers and regional players (e.g., Kaleyra, Route Mobile, Commio, Bird, TXTImpact, Teliqon, Twixor): These companies frequently innovate at the product layer (for example, rich messaging formats, low‑latency gateways, verticalized solutions) or focus on niche geographies and use cases.
Competitive dynamics are active: strategic partnerships, regional consolidation, and product extensions (notably around rich messaging standards and programmable RCS) are accelerating. A practical example: in March 2026 a market participant announced a new instant RCS business messaging product with accompanying industry recognition—an indicator that richer messaging formats are entering commercial deployments and shaping vendor roadmaps.
Operational headwinds and regulatory notes
-
Energy and infrastructure cost volatility: Wholesale electricity costs and capacity market movements have materially increased operating expense for data centers and cloud facilities in recent years. That shift has implications for providers whose cost base is energy‑intensive; enterprises should include energy exposure in long‑term supplier TCOs.
-
Carrier filtering and policy risk: Carriers globally continue to harden anti‑spam and A2P validation rules. These actions can abruptly change throughput or require additional certification steps; the full report provides risk mitigations and contractual language to address such events.
-
Regulatory precedent: Constitutional regulatory treatments that clarify messaging services’ status in key jurisdictions affect how services are provisioned, taxed, and audited. Historical regulatory orders have established important contours for what constitutes an information service versus an interconnected service—an important distinction for compliance teams.
A concise 2026 playbook for executives
-
Map your critical flows: Start by categorizing traffic (authentication, transactional, marketing, engagement) and apply different supplier and risk profiles to each—don’t treat all messaging the same.
-
Run a two‑tier supplier strategy: Combine at least one global platform for speed and cross‑border coverage with regional or network‑centric partners for high‑assurance delivery and cost control.
-
Insist on transparency: Require vendors to disclose routing, termination practices, and energy/resilience metrics; bake audit rights into contracts.
-
Price and capacity stress tests: Use the PW Consulting scenario models to test the impact of energy spikes, new compliance requirements, and rapid volume growth on unit economics.
-
Design for extensibility: Architect message flows so that richer channels (RCS, in‑app notifications, voice passcodes) can be introduced incrementally without large rip‑and‑replace projects.
-
Prepare for consolidation and opportunistic M&A: Vendors will continue to consolidate and specialize; maintain a shortlist of strategic targets and M&A criteria aligned with your endpoints (capability, customer base, or regional coverage).
Closing—what to expect next
PW Consulting’s full market study is designed as a decision support toolkit: it couples the headline growth trajectory and scenario analysis with vendor scorecards, contract playbooks, and operational runbooks that procurement, product, and risk teams can apply immediately. This preview exposes the trends and tradeoffs you must manage in 2026, while reserving the granular regional and application splits, as well as the vendor‑level scoring matrices, for the full report and subscription access.
For teams preparing 2026 budgets, negotiating new multi‑year CPaaS contracts, or building resilient messaging stacks, the study supplies both the macro market frame and the practical artifacts needed to act. Access to the full dataset and tactical appendices is available through PW Consulting’s report portal—request the comprehensive deliverables to translate this preview into executable plans.
For detailed analysis of this topic, please visit the official page: A2P SMS & cPaaS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com