

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
TEC Modules Market to Reach $1,688.97M by 2032 at 8.7% CAGR — Asia Pacific Leads ($488.66M)

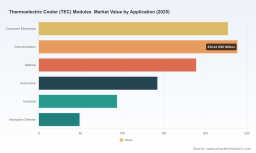
Thermoelectric Cooler (TEC) Modules Market — Strategic Primer for 2026 Decision‑Makers
As PW Consulting’s senior strategy team, we prepared this executive primer to translate our Thermoelectric Cooler (TEC) Modules Market study into immediate, operational value for firms taking strategic decisions in 2026. The TEC market is on a multi‑year expansion path: from a 2025 base year sized at roughly USD 940 million (Million, base year 2025), the sector is projected to exceed USD 1.03 billion in 2026 and continue to expand at a compound annual growth rate (CAGR) of about 8.7% through our 2026–2032 forecast window, reaching the high‑single‑digit to low‑double‑digit hundreds of millions by 2032. This trajectory elevates TEC modules from a niche specialty component to an investible, scalable element of thermal management programs across telecom, photonics, medical, automotive and industrial segments.
Thermoelectric Cooler (TEC) Modules Market
Why this research matters in 2026
-
Strategic inflection: Energy‑efficiency regulation, the drive for refrigerant‑free solid‑state cooling, and accelerating design‑in requirements from photonics and telecom OEMs have converged, creating a window for TEC vendors and integrators to move beyond one‑off engineering orders toward platformized, higher‑volume solutions.
Thermoelectric Cooler (TEC) Modules Market -
Commercial timing: The market’s projected expansion in 2026 is large enough to justify investments in capacity, certification and new product lines — but still early enough that first movers who execute on standards, supply security and design partnerships can capture disproportionate share gains.
Thermoelectric Cooler (TEC) Modules Market -
Supply chain leverage: Bismuth telluride remains the dominant semiconductor material for active TECs; capacity expansions and concentrated upstream supply make contracts, quality control and supplier diversification central to near‑term competitiveness.
What the PW Consulting report delivers — practical, decision‑ready content
-
Market sizing and forecasting model (2020–2025 historical; 2026–2032 forecast) with scenario capability to test demand under different adoption and policy pathways.
-
Segment-level diagnostics (by type, application and geography) presented as growth narratives and purchase‑driver maps — we intentionally withhold raw subsegment tables here to preserve the value of the full report, but the study includes granular shipment and revenue models by segment.
-
Competitive playbooks: product benchmarking, capability matrices, route‑to‑market maps and supplier scorecards for the industry’s active players.
-
Technology and standards tracker: performance roadmaps (ΔT, cooling power, efficiency), Telcordia and telecom qualification pathways, and certification cost/time estimates.
-
Supply‑chain and input‑cost models: bismuth telluride sourcing scenarios, labor and capital intensity benchmarks, and a stress‑test module for pricing and margin planning.
-
Commercial playbook: go‑to‑market options, OEM engagement strategies, prototyping and time‑to‑design‑win accelerators, plus an M&A/opportunity short‑list and diligence checklist.
Competitive landscape — who matters and why
The TEC vendor set in 2026 combines specialists with broad thermal portfolios, mass‑producers that enable cost scale, and boutique engineering houses focused on high‑reliability applications. The market is moderately concentrated: top suppliers hold meaningful share but there remains room for new entrants and regional champions. Below is a curated snapshot of firms we track closely (profile summaries are drawn from public disclosures):
-
Sheetak — Austin, Texas, USA ( https://sheetak.com/): Active manufacturer of CENTUM® single‑ and multi‑stage TEC modules, µCENTUM™ micro TECs, and custom Peltier coolers for photonics, optoelectronics, aerospace, and high‑performance applications. Notable 2026 moves: new miniature µCENTUM™ SKUs, a modular CryoSnap™ development kit, and expanded North American partnerships and trade show presence to accelerate design‑wins.
-
TEC Microsystems GmbH — Berlin, Germany ( https://www.tec-microsystems.com/): Manufacturer of aluminum‑plate and ceramic TEC series optimized for telecom, detectors and heavy‑load applications; market positioning emphasizes reliability and standards compliance for telecom qualification.
-
Ferrotec Corporation — Tokyo, Japan ( https://www.ferrotec.com/): Provider of high‑power Peltier TEC families targeting industrial and electronics cooling with broad high‑power portfolios and global manufacturing footprint.
-
Laird Thermal Systems — Delaware, USA ( https://lairdthermal.com/): Supplies OptoTEC micro TEC modules and high‑power thermoelectric coolers for telecom and industrial systems; strong channel and integration capabilities.
-
TE Technology, Inc. — Sherman Township, Pennsylvania, USA ( https://www.thermoelectric.com/): High‑quality manufacturer of TEC modules, cold plates and liquid coolers for electronics, medical and industrial markets; strengths in custom engineering.
-
Crystal Ltd. — Hong Kong ( https://www.crystalltherm.com/): Mass producer of bismuth telluride TEC modules and assemblies serving industrial and specialized cooling applications; cost leadership through scale.
-
KELK Ltd. — Tokyo, Japan ( https://www.kelk.co.jp/): Manufacturer under Komatsu Group with specializations in optoelectronics and precision cooling.
-
RMT Ltd. — Russia ( https://www.rmt-group.com/): Supplier of multi‑purpose TECs for high heat‑absorption applications, including deep‑cooled CMOS and IR sensors.
-
Thermonamic Electronics (Jiangxi) Corp. Ltd. — Jiangxi, China ( https://www.thermonamic.com/): Producer focused on high‑performance assemblies and regional volume supply.
-
KRYOTHERM — Germany ( https://kryotherm.com/): Manufacturer of high‑power and standard TEC modules for demanding thermal management tasks.
Recent competitive dynamics have been anchored by product launches and enabling offerings: Sheetak’s 2026 catalog introductions and prototyping kits are representative of a broader push to shorten design cycles and lock in OEM design positions early.
Key dynamics, inputs and risks
-
Raw material dependency — Bismuth telluride is the dominant active material. Manufacturers are expanding production capacity, but supply concentration and quality variance create near‑term procurement risk and bargaining asymmetry.
-
Standards and qualification — Telcordia GR‑468 and telecom reliability pathways matter for photonics and communications applications; certification timelines materially affect time‑to‑revenue for new products.
-
Labor and manufacturing intensity — High‑reliability TECs are labor and skill intensive. Labor cost pressures and specialized assembly needs mean automation and process control investments have favorable payback for firms targeting telecom and medical segments.
-
Market adoption drivers — Energy efficiency mandates and the push for refrigerant‑free cooling keep demand momentum steady; however, pockets of volatility exist by end‑market (e.g., automotive adoption cadence vs medical program cycles).
-
Infrastructure buildout — Expansion of capacity for bismuth‑telluride TECs and regional manufacturing investments are enabling nearer‑shoring options but require capital discipline to avoid overcapacity in adverse demand scenarios.
2026 decision playbook — concrete moves for executives
-
Prioritize design‑wins over one‑off sales. Shorten prototype cycles by investing in kits, application‑specific reference designs, and co‑engineering programs with target OEMs. Time to first shipment will meaningfully influence share gains in 2026–2027.
-
Lock material supply now. Secure multi‑year agreements for bismuth telluride or explore vertical partnerships to reduce volatility. Hedging raw material costs should be part of pricing models.
-
Certify early for high‑value verticals. Telcordia and equivalent standards certification should be a gating criteria for product roadmaps aimed at telecom and photonics customers.
-
Segment product portfolio: offer platformized single‑stage and multi‑stage product lines with clear performance tiers, while keeping a bespoke engineering arm for high‑margin, high‑reliability programs.
-
Invest in manufacturing resilience: targeted automation, quality control, and regional buffer capacity reduce lead times and improve margin stability.
-
Map M&A and partnership targets: pursue bolt‑on suppliers that add raw material security, assembly capabilities, or established OEM relationships rather than broad, expensive diversification.
-
Operationalize commercial intelligence: deploy a competitor watchlist, customer decision triggers, and an early‑warning dashboard for leading indicators such as telecom procurement cycles, photonics testbench orders and medical device qualification starts.
How PW Consulting’s report converts insight into executable advantage
Our full study delivers the analytical building blocks executives need to operationalize the above playbook: downloadable financial models, segment demand drivers, supplier scorecards, product GAP analyses, cost and margin simulators, and an M&A short‑list with diligence checklists. We also include scenario matrices that let teams stress‑test capacity investments and certification timelines against slower or faster adoption curves.
In keeping with this primer’s role as a directional preview, we have intentionally withheld the granular subsegment revenue tables and regional/application breakdowns from this summary. Those details — including shipment counts, ASP trajectories by product family, and segment‑level margins — are included in the subscription report and interactive model, which are essential for bid justification, capex planning and target selection.
Next steps for 2026
-
Download the full PW Consulting TEC Modules Market report to access the detailed segment models, supplier scorecards and scenario tools necessary to operationalize the strategy above.
-
Schedule a workshop with our thermal‑management practice to translate the market scenarios into a 90‑day action roadmap (procurement commitments, certification plan, and product roadmap milestones).
Thermoelectric cooling is entering a growth phase where engineering excellence, supply‑chain foresight and standards compliance will determine winners. Our research equips leaders to move from observation to decisive action in 2026 — but the window to position for scale is narrow. For the full data set, company scorecards and executable models, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Thermoelectric Cooler (TEC) Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com