

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glass Partition Wall Market to Reach USD 1,779.3M by 2032 at 6.5% CAGR

Glass Partition Wall Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive preview of our Glass Partition Wall Market study — a tactical briefing designed to equip corporate leaders, investors, and procurement strategists with the high‑level intelligence they need to make decisive moves in 2026. This narrative synthesizes the study’s macro trajectory, competitive dynamics, supply‑chain signals and regulatory inflection points, while intentionally withholding granular segment tables and regional splits to prompt full report access for operational deployment.
Glass Partition Wall Market
Market trajectory at a glance — what matters to 2026 decisions
- The study uses 2025 as the base year and incorporates a five‑year historical run (2020–2025) plus a seven‑year forecast window (2026–2032).
- At the macro level, the global glass partition wall market is growing. Our output shows the market valued at approximately USD 1,150 million in 2025, with the forecast pointing to roughly USD 1,241 million in 2026 and an expected expansion to about USD 1,779 million by 2032.
- The forecast period reflects a compound annual growth rate (CAGR) of 6.5% — a rate that signals steady demand expansion driven by renovation cycles, flexible workspace adoption, and increased specification of high‑performance glazing in commercial and institutional projects.
- Concentration metrics indicate a market where leading groups hold material influence but substantial white‑space remains for challengers: the three‑firm concentration ratio (CR3) stands in the mid‑50s percent range, while the top five players account for under 70% of the market — a structure that favors strategic consolidation, targeted differentiation, and regional plays.
Why this matters for your 2026 strategy
For executives making capital allocation, product roadmap, or M&A choices in 2026, the report’s macro picture yields four practical implications:
Glass Partition Wall Market
- Resource allocation should balance growth and resilience. A mid‑single digit CAGR implies predictable expansion; allocate growth capital to scalable modular product lines and digital specification tools, while preserving agility against input volatility.
- Go‑to‑market segmentation will be a differentiator. With demand spread across commercial, institutional and industrial end markets, success will hinge on tailored offerings (acoustic performance, fire rating, demountability) rather than broad commoditization.
- Supply‑chain optimization is time‑sensitive. Raw material signals (notably soda ash dynamics) have recently softened prices — a window to renegotiate contracts and lock in favorable terms — but suppliers remain exposed to cyclical swings, making dual‑sourcing and local production attractive hedges.
- Regulatory preparedness is non‑negotiable. Evolving test standards and fire/ acoustic codes are influencing specification cycles; early compliance and certification convert into bid‑win advantages on large institutional projects.
Competitive landscape — what to watch in 2026
The market’s concentration profile creates a two‑tier competitive dynamic: established players with integrated design‑to‑install capabilities, and nimble specialists who compete on lead time, customization and cost. The companies profiled in our study exemplify the strategic archetypes:
Glass Partition Wall Market
- Integrated design‑manufacture‑install players that emphasize end‑to‑end service and fast lead times (e.g., established U.S. specialists). These firms win large commercial contracts by coupling engineered systems with installation logistics.
- Regional manufacturers that compete on factory pricing and customization for local projects, often leveraging direct‑to‑site supply chains in high‑growth corridors.
- Premium, sustainability‑oriented producers that emphasize accredited production sites, lifecycle credentials and design awards — attractive to high‑end architects and major corporate occupiers.
- Modular and fit‑out innovators who deliver demountable, reconfigurable walls with short construction timelines, appealing to the flexible workspace trend.
Recent industry moves underline these dynamics. Product introductions and trade show activity in late 2025 and early 2026 show vendors prioritizing slim profiles, demountability and designer aesthetics, while major fit‑out suppliers emphasize lifetime warranties and acoustic performance. These developments underscore the market’s current emphasis on design flexibility and total cost of ownership rather than simple price competition.
Supply‑chain and input risks — actionable signals
- Raw material trend: soda ash — a principal glass feedstock — experienced price declines in 2025 due to oversupply and softer demand in adjacent sectors, while domestic production grew modestly. For manufacturers and buyers, this implies a near‑term cushion in glass melt costs, but not a permanent margin windfall. Procurement teams should exploit the easing for forward buys and renegotiation, while keeping contingency plans for potential supply disruptions.
- Logistics and lead‑times: lead‑time compression has become a commercial advantage. Firms that shorten lead times through regional warehousing, modular components or local glazing capacity gain share in fast‑track refurbishments and tenant‑improvement projects.
- Capital intensity: manufacturers that invest in automated handling, tempering and laminating lines can lower per‑unit cost and reduce breakage exposure; however, payback periods require demand visibility — something the report’s scenario models help to validate.
Regulatory and standards environment — compliance as advantage
Standards and fire/sound testing regimes are converging toward stricter classifications. Key developments include enhanced guidance for mounting and reaction‑to‑fire testing (recent international standards updates) and the continued centrality of airborne sound transmission testing per established ASTM protocols. For suppliers and specifiers alike, documented compliance with these standards is increasingly a gating item for large institutional and public sector tenders. Our report maps out which product attributes and test certifications materially affect bid outcomes across project types.
Practical content of the full report — what you’ll get
Designed as a board‑level playbook and working‑level toolkit, the full study contains:
- Quantitative market model (historical 2020–2025 and forecasts 2026–2032) with downloadable datasets for scenario testing against your internal assumptions.
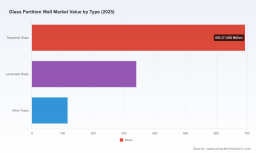
- Segmented demand analytics across product types, applications and regions — presented with supplier benchmarking and margin analysis. (Note: detailed segment tables and regional splits are intentionally reserved for the full report to maintain our "trailer" posture here.)
- Supplier profiles and a competitive scorecard that rates capabilities in manufacturing footprint, lead time, sustainability credentials and compliance testing.
- Deal‑level and M&A playbooks: valuation drivers, integration checklist, and three acquisition archetypes calibrated to market concentration dynamics.
- Procurement playbook: hedging strategies for raw materials, inventory optimization templates, and contract terms that convert lower input cost into durable margin gains.
- Scenario planning tools and sensitivity analyses that stress test growth under differing macro and input price regimes.
Recommendations for executive action in 2026
- Prioritize certified performance. Expedite testing and certification for acoustic and fire standards if you bid on institutional or high‑end commercial projects — certifications are quickly becoming a table stake.
- Shorten the order‑to‑install cycle. Invest in modular offerings and local assembly hubs to capture faster‑moving tenant improvement business and to defend against low‑cost competitors.
- Use the current input price environment tactically. Lock favorable contracts where possible, but retain flexible sourcing to respond to cyclical rebounds in key feedstocks.
- Evaluate M&A selectively. Given the market’s CR3/CR5 profile, bolt‑on acquisitions that add regional distribution or specialized testing capabilities can produce outsized returns versus broad consolidation plays.
- Embed sustainability and lifecycle arguments into pricing. Clients increasingly value whole‑life performance; demonstrating lifecycle benefits can justify premium pricing and reduce procurement churn.
Final note — the strategic utility of the full study
This preview demonstrates the type of actionable thinking and forecasting that PW Consulting delivers: a market growth pathway, competitive map, supplier‑risk framework and decision tools calibrated for 2026. To translate these strategic insights into operational plans — from capex choices to bid strategies and acquisition screening — you will need the report’s segmented tables, regional demand matrices and supplier scorecards. Those detailed datasets and benchmarks are intentionally withheld here to preserve the report’s value proposition and to guide practitioners to the full intelligence pack.
If you are preparing budgets, revising product roadmaps, or evaluating M&A in 2026, the full Glass Partition Wall Market report provides the granular evidence base and executable playbooks you will use to move from strategy to results. Contact PW Consulting to access the complete study and the underlying datasets that will allow you to run tailored scenarios against your portfolio.
For detailed analysis of this topic, please visit the official page: Glass Partition Wall Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com