

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
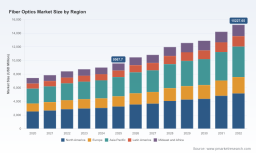
PW Consulting: Fiber Optics Market to Reach USD 15,227.7M by 2032 at 6.86% CAGR

Fiber Optics Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive primer — why this study matters in 2026
The fiber optics industry has moved from incremental utility to strategic infrastructure. Our PW Consulting analysis positions the global market as a multi‑billion dollar growth opportunity with a compound annual growth rate (CAGR) of 6.86% through the 2026–2032 forecast window. After steady expansion during 2020–2025, the base‑year market (2025) is reported at USD 9,567.7 Million and is projected to climb meaningfully over the next several years. For executives planning CAPEX, sourcing, R&D, or M&A in 2026, the timing to translate directional trends into concrete decisions is now: the market is large, growing, and being reshaped by concentrated technology demand, supply‑side stressors, and policy action.
Fiber Optics Market
What this report delivers — practical, decision‑grade outputs
- Clear top‑line trajectory and scenario models: Time‑series demand and revenue models covering 2020–2032, with three stress‑tested scenarios that map different AI, broadband, and industrial adoption curves against price and capacity shocks.
- Executive dashboards and playbooks: Actionable dashboards for boardroom briefings and a set of playbooks (sourcing, localization, vertical integration, and strategic partnerships) tailored for OEMs, cable manufacturers, hyperscalers, and telecom operators.
- Vendor and technology scorecards: Standardized criteria to evaluate suppliers across performance (fiber type and loss characteristics), manufacturing footprint, contractual flexibility, and geopolitical risk exposure.
- Supply‑chain risk maps and mitigations: Identification of single‑point dependencies (materials, components, and equipment), lead time scenarios, and practical hedging strategies—spanning contractual levers, inventory policy, and dual‑sourcing templates.
- Capital planning templates: CAPEX/OPEX overlays tied to network architectures (centralized vs. distributed), total cost of ownership (TCO) calculators, and payback analyses for fiber upgrades, replacement cycles, and co‑packaged optics investments.
- Regulatory & funding trackers: A living summary of major public funding programs and regulatory changes that affect deployment economics and procurement rules across major markets.
Core dynamics that should drive your 2026 choices
Several interconnected forces are steering the industry’s commercial logic in 2026. These are not abstract trends—each alters supplier economics, contract design, and technology roadmaps.
Fiber Optics Market
- Demand concentration in AI and hyperscale networking: Rapid densification of data center interconnects and co‑packaged optics initiatives are creating high‑intensity pockets of demand that differ materially from traditional telco and FTTH needs. Buyers must design procurement strategies that reconcile very different lifecycle and performance requirements.
- Policy and public funding acceleration: Large‑scale broadband and infrastructure programs continue to catalyze national deployment initiatives and influence where manufacturers and integrators allocate capacity and capital.
- Raw‑material and supply sensitivities: The upstream supply chain—particularly specialty dopants and preform materials—has become a strategic choke point. Recent months have seen notable price volatility and capacity rebalancing; companies without hedging or validated secondary sources face margin and delivery risks.
- Manufacturing reshoring and capacity expansion: Responding to hyperscaler demand and sovereign supply concerns, significant new capacity is being added in target markets. This alters lead times and cost curves for regional buyers but also intensifies competition for skilled labor and specialized equipment.
- Technology modularization: Multicore fibers, micro‑cables, and connector innovations are shifting cost/performance tradeoffs. Standards and MSAs for multicore designs are forming rapidly—early participation in these industry consortia can shape interoperable ecosystems and create supplier advantage.
Competitive landscape — strategic takes on leading players
The market combines global incumbents with regional specialists. The competitive field is characterized by deep technological capabilities, global manufacturing footprints, and an acceleration of strategic partnerships. Our sector analysis in the report synthesizes public disclosures, product roadmaps, and partnership announcements to produce a comparative, decision‑oriented view.
Fiber Optics Market
- Corning Incorporated: The incumbent technology leader—recognized for scale in single‑mode and advanced multicore solutions—has repositioned manufacturing and supply to serve hyperscale AI customers and is rapidly commercializing higher‑density optics and connector ecosystems. Recent product launches and supply agreements underscore a strategy of integrated system provision for data centers.
- Sumitomo Electric: Focused on ultra‑low‑loss fibers and end‑to‑end interconnect solutions, Sumitomo’s technical leadership in long‑haul and low‑attenuation fibers positions it well for capacity‑intensive network backbones and premium data center links.
- Fujikura: Active in multicore fiber standardization, Fujikura is aligned with AI‑optimized campus architectures and is leveraging consortium activity to accelerate adoption of higher‑density cabling in hyperscale environments.
- Prysmian Group and Nexans: European incumbents with strong systems capability across energy and telecom markets; their strengths lie in project execution for large infrastructure and industrial applications where end‑to‑end delivery and warranty are decision factors.
- Fitel / OFS, Sterlite, YOFC, FiberHome, CommScope, Amphenol: A cohort of specialized manufacturers and connectivity suppliers offering targeted value—whether in specialty fibers, local manufacturing scale, or high‑performance connectors. These players are often preferred by regional operators and system integrators for speed and price competitiveness.
Recent moves that change the strategic calculus
Industry collaboration and vendor commitments in early 2026 have accelerated momentum around multicore fiber standards and high‑density interconnects. Several leading suppliers have announced concerted efforts to standardize multicore architectures and to launch integrated systems aimed at AI campus densities. Such initiatives reduce integration risk for early adopters, but they also shorten windows for differentiation—firms that miss the early standards phase may find themselves dependent on commodity pricing rather than shaping specifications.
Risk scenarios — what to stress test in boardroom planning
The report provides scenario templates; here are the top strategic stress tests executives should run in 2026:
- Demand surge vs. supply constraint: Model the impact of a rapid hyperscaler procurement cycle on your supplier base and internal build schedules. Identify which contracts can scale without renegotiation and where minimum order quantities create risk.
- Material embargo or licensing restrictions: Assess the time‑to‑switch for critical dopants and preform inputs, and the cost of maintaining buffer stocks or alternative process routes.
- Price shock pass‑through: Simulate different pricing regimes for core materials and identify product lines where margins compress first; design pricing clauses and indexation strategies accordingly.
- Standards divergence: Evaluate the commercial impact if competing multicore standards gain asymmetric market acceptance, and map options for alliance, porting, or parallel qualification.
How to convert insight into action in 90–180 days
Based on our advisory engagements, successful companies follow a pragmatic, three‑track approach:
- Immediate (0–90 days): Run supplier risk audits, finalize short‑term hedging for critical inputs, and prioritize qualification of at least one secondary supplier for each high‑risk material or component.
- Medium (90–180 days): Negotiate scalable supply agreements with clear ramp profiles, invest in joint development agreements where standards are forming, and align procurement T&Cs to allow flexibility in volume and delivery.
- Organizationally: Create a cross‑functional fiber strategy cell (procurement, engineering, legal, M&A) to translate scenario outputs into contract templates, R&D priorities, and capital allocation decisions.
Why PW Consulting’s report is different
We combine a bottom‑up, transaction‑grade dataset (serial‑level production and orderbook analysis) with top‑down scenario engineering. The deliverable is designed for decision makers who need both a defensible forecast and an executable playbook: not just “what the market will be,” but “what you should do about it.” The report includes granular supplier scorecards, an operational risk atlas, and downloadable financial models aligned to the 2026 planning calendar.
Next steps — how to capture the intelligence you need
This article is a high‑precision extract. For the full suite—interactive dashboards, supplier matrices, scenario spreadsheets, and procurement playbooks—visit our report landing page. The full report contains the granular segmentation, regional and application dynamics, and vendor detailed profiles that are necessary to operationalize the strategies outlined here.
In a market where technology standards, buyer concentration, and supply fragilities are converging, timely, data‑driven choices will determine who captures value as the industry scales. PW Consulting’s Fiber Optics Market report arms leaders with the models and tools to make those choices with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Fiber Optics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com