

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PEMFC Market Accelerating with a 16.5% CAGR

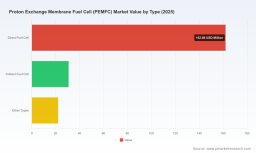
PEMFC Market Outlook 2026: Strategic Imperatives for Decision-Makers
Executive summary
The Proton Exchange Membrane Fuel Cell (PEMFC) market is entering a decisive phase as organizations across mobility, stationary power, and industrial applications move from pilot projects to scaled commercialization. Our analysis shows the market expanding from approximately USD 163 million in 2020 to roughly USD 215 million in the base year (2025), with a projected compound annual growth rate (CAGR) of 16.5% across the 2026–2032 forecast window. By 2032, the industry is expected to approach the upper hundreds of millions in revenue, driven by more mature stack platforms, vehicle OEM adoption, and infrastructure alignment.
Proton Exchange Membrane Fuel Cell (PEMFC) Market
This introduction previews the strategic value of PW Consulting’s full PEMFC Market study for corporate leaders planning capital allocation, product roadmaps, and supply chain investments in 2026. It is designed as a high-fidelity teaser: we present the analytic posture, key dynamics, and competitive implications while intentionally withholding granular segment-level numbers and proprietary model outputs to encourage access to the full report.
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Why this study matters for 2026 decisions
-
Timing of investment: With the sector growing at a double-digit CAGR, 2026 will be a pivot year for converting technological parity into commercial scale. Companies deciding on manufacturing footprint, vertical integration, or long-term supplier commitments need a defensible view of market trajectories and scenario-based demand curves.
Proton Exchange Membrane Fuel Cell (PEMFC) Market -
Platform choices: PEMFC stack architectures and balance-of-plant decisions made in 2026 will define cost structures and upgrade pathways for a decade. Firms must weigh high-power density platforms against manufacturability and supply risk.
-
Procurement and sourcing strategies: As the industry moves from prototype to production, procurement windows for critical components—membranes, bipolar plates, and catalysts—will open and close rapidly. The full study provides procurement playbooks tied to vendor maturity and lead-time scenarios.
Market overview (what the macro numbers mean)
The PEMFC market’s historical trajectory (2020–2025) demonstrates a recovery from early commercialization bumps into sustained growth driven by fleet-level adoption and industrial stationary pilots. The base-year sizing in 2025 represents an inflection where modular, higher-power stacks and system-level integration improvements translate into clearer TCO pathways for end customers.
Projecting forward, the modeled 16.5% CAGR captures a convergence of factors: declining stack costs through volume and design-for-manufacturing gains; broader hydrogen ecosystem investments; and regulatory pushes that favor zero-emission heavy-duty and niche commercial platforms. The forecast horizon to 2032 presents a range of viable outcomes; the central scenario anticipates continued technology maturation and steady policy support, but upside and downside pathways are explicitly modeled in the report’s scenario suite.
What the PW Consulting PEMFC report contains (practical, actionable content)
-
Proprietary market-sizing methodology and transparent assumptions, calibrated to 2020–2025 historicals and stress-tested across demand scenarios for 2026–2032.
-
Supply-chain heat maps identifying concentration risks (critical materials, tooling, long-lead suppliers), supplier maturity tiers, and recommended dual-sourcing strategies for risk mitigation.
-
Technology deep dives—stack architectures, bipolar plate materials, membrane chemistries, and system integration trade-offs—benchmarked by power density, durability, and manufacturability.
-
Commercialization playbooks for OEMs and tier suppliers covering product roadmap sequencing, pilot-to-production gating criteria, and contracting templates aligned with performance warranties.
-
Regulatory and standards tracker focused on heavy-duty validation protocols, automotive low-temperature resistance requirements, and certification roadmaps that affect time-to-market.
-
Investor-grade competitive intelligence: leadership profiles, capability matrices, partnership ecosystems, recent deals, and scenario-based share trajectories for near-term strategy planning.
-
Financial models with sensitivity analyses (price curves, learning rates, capex/OPEX trade-offs) and a set of investment decision frameworks for M&A, joint ventures, and greenfield manufacturing.
Competitive landscape — what to watch in 2026
The PEMFC market remains moderately fragmented, with the top players accounting for a plurality but not a dominant share—an environment that benefits nimble technology leaders and well-funded incumbents alike. Key companies and their strategic positions include:
-
Ballard Power Systems (Vancouver, Canada) — Ballard’s FCgen platform targets mobility with high-power-density stacks. Recent commercial agreements signal a transition from development partnerships to volume-enabling supply relationships in the bus and coach segments. For corporate decision-makers, Ballard represents a partner of choice for mobility integrators seeking established stack platforms with system engineering support.
-
EKPO Fuel Cell Technologies (Dettingen/Erms, Germany) — EKPO is positioning production-ready NM-series modules for light- and medium-duty vehicles. Their public product showcases indicate a leap toward automotive-grade modules, which matters for OEMs planning platform integration within automotive supply chains and for suppliers assessing qualification timelines.
-
Cummins Inc. (Columbus, Indiana, USA) — Cummins brings deep systems integration experience and modular hydrogen engine products aimed at on- and off-highway transport. Their approach combines traditional OEM reliability engineering with fuel-cell-specific scaling strategies, making them a credible partner for truck and bus OEMs seeking turnkey system solutions.
-
Toyota Motor Corporation (Toyota City, Japan) — Toyota’s third-generation PEM systems emphasize durability and commercial-sector readiness. As a major OEM with vertically integrated capabilities, Toyota’s product developments set important benchmarks for lifecycle requirements and durability expectations in commercial deployments.
-
Intelligent Energy Limited (Cheltenham, UK) — Intelligent Energy’s high-power modules target both automotive and stationary markets. Their ability to bridge use cases offers partnership options for companies pursuing cross-market product lines or diversified revenue streams.
-
ElringKlinger / EKPO joint venture (Dettingen/Erms, Germany) — With bipolar-plate expertise and stack-module deliveries, the JV is strategically positioned to influence material choices and manufacturability. Their role underscores the importance of in-house materials capability for companies aiming to manage cost and weight trade-offs.
-
Hyundai Motor Company (Seoul, South Korea) — Hyundai’s integrated approach to stack and system development—often via joint collaborations—remains pivotal for commercial vehicle deployment strategies and for alliances seeking an OEM-led route to market.
-
Nedstack Fuel Cell Technology BV (Almelo, Netherlands) — Nedstack’s focus on mission-critical, high-power stacks positions them for niche opportunities where uptime and reliability are non-negotiable, such as rail or remote industrial power.
-
PowerCell Sweden AB (Aalborg, Denmark) — PowerCell’s systems for on-road, rail, and marine propulsion highlight cross-domain applicability and the importance of marine/rail certification pathways for firms targeting diversified mobility portfolios.
Recent signals and why they matter
-
Strategic commercial agreements—such as newly announced supply deals for bus engines—illustrate maturation in buyer-supplier contracting and the emergence of repeatable procurement cycles.
-
Product showcases and production-ready stack modules at major trade events are indicative of vendors closing the gap between lab performance and manufacturability; procurement teams should accelerate technical qualification timelines accordingly.
-
OEM product development milestones—particularly announcements of next-generation PEM systems—serve as durable benchmarks for expected lifecycle and durability targets in commercial fleets.
Technology, materials, and supply-chain dynamics
Material choices and manufacturing techniques remain the fulcrum of competitive advantage. Bipolar plates, for example, account for the vast majority of a stack’s weight and are therefore central to efforts in lightweight integration for automotive PEMFC systems. Advances in polymer and composite substrates (including high-performance PPS variants) can meaningfully improve durability and cost-per-kilowatt through simplified assembly and longer service intervals.
Regulatory and testing frameworks are also tightening. Heavy-duty PEMFC deployments are increasingly validated under accelerated stress test protocols designed to mimic high-temperature and dynamic-load conditions. For manufacturers, meeting these protocols is a gating criterion for fleet adoption. Parallel to this, light-duty production follows automotive standards emphasizing low-temperature resistance and common part procurement—requirements that shape supplier selection and design-for-assembly choices.
Risks, accelerators, and decision levers
-
Risk: supply concentration for critical components and catalysts can create lead-time bottlenecks that inflate capex and slow product rollouts. Mitigation strategies include long-term offtake agreements and localized manufacturing partnerships.
-
Accelerator: coordinated policy and infrastructure investments (refueling networks, incentives) materially shorten commercialization timelines and improve fleet economics.
-
Decision lever: choose platform partners based on a composite of power density, durability validation, and supplier maturity rather than single-metric comparisons. Our vendor scorecards quantify these trade-offs for procurement and strategic sourcing teams.
How to use the full PW Consulting PEMFC study in 2026
-
Board-level scenario planning: incorporate our scenario outputs into capital allocation and M&A playbooks to stress-test investments under different policy and technology uptake conditions.
-
Procurement roadmaps: align supplier qualification schedules with our recommended gating criteria to avoid time- and cost-overruns during pilot-to-production transitions.
-
Product strategy: use technology benchmarking to prioritize R&D investments that close the gap between lab metrics and field durability requirements.
-
Partnership evaluation: apply our competitive intelligence to select co-development partners and to negotiate fair-value commercial terms that reflect stage-of-maturity risk.
Closing and next steps
The 2026 decision window will reward clarity of assumptions and speed of execution. PW Consulting’s full PEMFC Market report provides the granular segmentation, regional and application-level forecasts, vendor matrices, and financial models needed to convert strategic intent into executable plans. This introduction has surfaced the principal dynamics, the competitive field, and the practical levers available to leadership teams—but the complete dataset, scenario outputs, and supplier-level insights are reserved for the full study.
To access the end-to-end models, detailed segment-level forecasts, and procurement playbooks that underpin the conclusions summarized here, please refer to the PW Consulting report landing page or contact our industry team for a briefing and customized decision-support package.
For detailed analysis of this topic, please visit the official page: Proton Exchange Membrane Fuel Cell (PEMFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com