

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Online Accounting Software Market: Why a 9.6% CAGR and SaaS Shift Change Everything
By pmarketresearch, 2026-09-21
The $26 Billion Horizon: Strategic Shifts in the Online Accounting Software Market
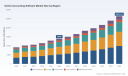
The global online accounting software market has matured into a foundational digital infrastructure for enterprises of every scale. With revenue surpassing $14 billion in 2025 and a projected expansion to approximately $26.4 billion by 2032, the sector is advancing at a compound annual growth rate of 9.6 percent. This trajectory reflects more than routine digitization; it signals a structural realignment in how firms capture, reconcile, and act upon financial data. As cloud-native platforms replace legacy on-premise systems, accounting software is increasingly functioning as the operational core of broader enterprise technology stacks. For executives, strategists, and investors, the critical question is no longer whether to adopt online accounting solutions, but how to navigate the compounding technological, regulatory, and competitive dynamics that will determine market positioning over the next half decade.
Despite the favorable growth trajectory, the industry confronts several structural friction points that are reshaping vendor roadmaps, customer purchasing behavior, and capital allocation strategies. First, legacy migration and process standardization remain persistent barriers. Organizations still operating fragmented spreadsheets, outdated desktop packages, or heavily customized ERPs face steep integration and training costs. The perceived risk of operational disruption often delays adoption, even when long-term efficiency gains are clear. Second, the accounting talent bottleneck is intensifying. As platforms automate data entry, reconciliation, and reporting, firms are demanding higher-order analytical and advisory capabilities from finance teams, yet the pipeline of professionals skilled in both financial operations and digital tooling remains constrained. Third, the post-pandemic normalization of remote and hybrid work models has altered procurement expectations. Decision-makers now prioritize seamless cross-device access, real-time collaboration, and integration with geographically distributed banking and payment ecosystems. These pressures are not merely operational; they are redefining vendor selection criteria and accelerating the shift from point-solution purchasing toward unified, workflow-aware platforms.
Market authorities, vendor product cycles, and macroeconomic indicators point to a clear inflection point. Cloud accounting is no longer a convenience layer; it is becoming the data spine for treasury management, compliance automation, and strategic decision-making. The firms that will capture disproportionate value are those that align platform capabilities with these evolving operational realities rather than simply replicating traditional bookkeeping functions in a browser.
Key Drivers Reshaping the Market
Technology Innovation and the Automation Ceiling
The most consequential driver in the online accounting software space is the rapid integration of artificial intelligence and machine learning into core financial workflows. Early automation focused on rule-based transaction categorization and recurring invoice generation. Contemporary platforms are advancing toward intelligent reconciliation, contextual anomaly detection, and narrative financial summarization. Vendors are embedding AI-assisted bookkeeping, predictive cash flow modeling, and automated audit trail generation directly into cloud environments. The operational impact is substantial: finance teams are reducing manual review cycles, lowering error rates in high-volume transaction processing, and freeing capacity for scenario planning and working capital optimization. For mid-market and enterprise buyers, the value proposition has shifted from basic digitization to continuous, low-friction financial intelligence.
This shift is already visible in product development cycles across the ecosystem. Platform updates from major providers increasingly emphasize generative capabilities for report drafting, intelligent receipt and invoice matching, and natural-language query interfaces. The underlying trend is a gradual erosion of the traditional boundary between accounting software and broader financial operations platforms. As AI handling of routine tasks reaches higher accuracy thresholds, vendors are reallocating engineering resources toward workflow orchestration, multi-entity consolidation, and real-time decision support. Providers that treat automation as a standalone feature rather than an integrated capability risk commoditization, while those that embed it into end-to-end processes are building defensible switching costs.
Accounting Software Market
Regulatory and Data Infrastructure Pressures
The regulatory and infrastructure environment is exerting a quieter but increasingly material influence on cloud accounting deployment. Data sovereignty requirements, cross-border reporting mandates, and evolving audit expectations are pushing vendors to invest in regional compliance frameworks and localized data handling options. Simultaneously, the physical and economic realities of cloud infrastructure are entering strategic conversations. Hyperscale data center demand driven by AI and cloud workloads is projected to more than double by the end of the decade, raising compute and storage costs that eventually cascade into software pricing, tier structures, and service-level commitments. In several U.S. jurisdictions, state-level returns on data center investments have fallen materially short of projections, prompting stricter permitting, sustainability reviews, and community-level scrutiny. Multiple large-scale facilities faced delays or denials in recent periods, and a significant volume of infrastructure capital remains stalled in permitting pipelines.
These dynamics carry direct implications for online accounting providers. Vendors dependent on centralized hyperscale environments may face capacity constraints, latency trade-offs, or cost pressures that affect scalability and deployment timelines. For enterprise buyers, this translates into a more complex evaluation matrix that now includes provider infrastructure resilience, data residency options, and long-term pricing stability. The regulatory and infrastructure conversation is no longer a back-office concern; it is becoming a factor in vendor selection, contract structuring, and multi-year technology planning.
Demand-Side Shifts and the Rise of Platform Ecosystems
Customer expectations are evolving faster than the traditional accounting software catalog. Small and mid-sized businesses increasingly view financial tooling not as isolated bookkeeping systems but as integrated components of broader operational workflows that span invoicing, payroll, inventory, CRM, banking, and payment processing. Large enterprises, meanwhile, are prioritizing consolidation, advanced multi-entity reporting, subscription billing, and alignment with existing ERP and treasury environments. In both segments, procurement decisions are being driven by interoperability, user experience, and the ability to reduce context-switching across tools. Buyers are less willing to accept rigid, standalone packages and more inclined toward modular ecosystems that can scale with organizational complexity.
This demand evolution is reshaping competitive positioning. Vendors that originally built value propositions around specific audience segments are expanding their functional footprints, while broader technology and financial services players are entering the accounting workflow space through partnerships, embedded finance products, or integrated platform suites. The result is a marketplace where differentiation increasingly depends on integration breadth, workflow customization, and the depth of domain-specific automation rather than basic cloud availability.
Competitive Landscape and Strategic Positioning
Divergent Models Among Established Leaders
Intuit maintains a strong foothold through cloud accounting platforms tailored to small and mid-sized businesses, emphasizing AI-assisted bookkeeping, invoicing, and real-time financial visibility. Its strategic emphasis has been on embedding accounting within a broader small-business ecosystem, reducing friction in everyday financial operations, and expanding the addressable use case beyond traditional ledger management. Xero has cultivated a distinct position by prioritizing real-time bank synchronization, workflow automation, and multi-currency capabilities for small to mid-sized firms. Its differentiation rests on open integration architectures and a partner network that extends platform functionality across geographies and verticals. Sage continues to focus on mid-market and enterprise complexity, offering cloud ERP and accounting solutions with advanced financial consolidation, subscription billing, and multi-entity governance. Its trajectory reflects a push toward higher-value financial management rather than transactional bookkeeping alone.
Wave and FreshBooks illustrate another strategic axis: highly segmented, user-centric solutions for freelancers, service businesses, and early-stage companies. Their emphasis on free or low-friction entry points, time tracking, expense management, and simplified invoicing demonstrates how specialized positioning can sustain growth in crowded segments by reducing adoption barriers and aligning tightly with specific workflow patterns. Zoho Books reflects the broader platform-play approach, bundling accounting with automation and cross-application interoperability for small businesses and startups, leveraging ecosystem scale to offer extensive user capacity and integrated process flow.
Recent events underscore the intensity of this competitive recalibration. In early 2025, a major provider expanded its North American presence with a new headquarters designed to accelerate cloud accounting growth and client collaboration. Later in the year, a newer entrant introduced an AI-enabled accounting agent for cloud environments, reporting high accuracy in reconciliations and receipt matching. A workflow specialist released a cloud-based practice management tool aimed at accounting firms, targeting client communication and internal process coordination. Meanwhile, a large enterprise cloud provider embedded a generative AI assistant capable of drafting financial reports and narrative summaries, and a commercial bank launched an integrated cloud accounting platform connecting banking services directly to bookkeeping for enterprise clients. These moves are not isolated product launches; they signal converging strategies around AI capability depth, workflow orchestration, and ecosystem integration.
Consolidation, Fragmentation, and New Entry Dynamics
The market is simultaneously exhibiting consolidation and differentiation. Larger players are pursuing broader functional coverage, deeper enterprise features, and strategic partnerships that extend reach into banking, payroll, and practice management. At the same time, specialized solutions continue to thrive by occupying narrow segments with superior user experience, rapid deployment, or vertical-specific automation. New entrants are emerging around AI-native reconciliation, automated compliance support, and embedded financial services, often competing on accuracy, speed, and workflow simplicity rather than legacy feature breadth.
Market concentration remains moderate, with a limited number of large vendors commanding a meaningful share of revenue while a long tail of niche and regional providers competes on service quality, localization, and integration depth. This structure suggests that competitive advantage will increasingly derive from execution quality, ecosystem relationships, and the ability to reduce total cost of ownership across the finance function rather than from proprietary ledger technology alone. For buyers, the implication is a more dynamic evaluation environment in which switching costs, integration commitments, and long-term roadmap alignment matter as much as current feature sets.
Outlook: Three Trends Shaping the Next Three to Five Years
From Bookkeeping to Continuous Financial Operations
Over the next several years, online accounting software is likely to be evaluated less as a record-keeping tool and more as a continuous financial operations layer. AI-driven reconciliation, anomaly detection, and automated reporting will become baseline expectations rather than premium differentiators. Platforms that can synthesize transactional data, banking flows, and operational inputs into forward-looking insights will gain preference in both mid-market and enterprise segments. This shift creates opportunities for vendors to expand into working capital optimization, scenario modeling, and advisory-adjacent workflows. It also raises the stakes for providers that remain anchored in retrospective accounting functions, as customers increasingly expect systems that support both compliance and decision velocity.
A persistent risk in this trajectory is the potential for uneven AI reliability across edge cases, multilingual contexts, and highly customized transaction structures. Buyers will need to balance automation enthusiasm with controlled adoption, particularly in regulated industries or multi-entity environments where auditability and explainability remain critical.
PW Consulting
Infrastructure Economics and Compliance as Strategic Variables
The economics of cloud infrastructure and the evolving regulatory landscape will increasingly influence software strategy. As compute and storage demands intensify, providers will need to manage cost structures more deliberately, potentially influencing pricing tiers, feature packaging, and data handling models. Regional compliance, data residency expectations, and sustainability-related review processes will add complexity to deployment planning, especially for global organizations. Vendors that design for flexibility—through regional deployments, modular architecture, and transparent cost models—will be better positioned to maintain scalability without eroding customer trust.
For buyers, this environment calls for more rigorous due diligence on provider infrastructure roadmaps, data governance practices, and long-term service continuity. The risk is not only cost escalation but also potential deployment friction if local permitting, energy constraints, or regulatory reviews slow capacity expansion. Organizations that treat infrastructure resilience and compliance alignment as evaluation criteria today will be better insulated from disruption tomorrow.
Ecosystem Embedding and the Blurring of Financial Toolsets
The third major trend is the progressive integration of accounting software into broader financial and operational ecosystems. Banking integrations, embedded payments, payroll connectivity, and practice management workflows are reducing the isolation of accounting tools and making them part of a continuous enterprise data flow. This convergence benefits users through reduced manual handoffs and improved data consistency, but it also complicates vendor landscapes. Procurement teams will face an expanding set of integration choices, partnership dependencies, and data-sharing considerations. Vendors that offer open, well-documented integration frameworks and clear data portability options will capture advantage in an environment where lock-in risk is increasingly scrutinized.
The opportunity here lies in building or selecting platforms that operate as connective tissue rather than closed silos. Enterprises that align accounting systems with treasury, payments, and operational planning tools can accelerate close cycles, improve forecast accuracy, and support more agile resource allocation. The uncertainty is that rapid ecosystem expansion can outpace governance maturity, creating data quality, access control, and vendor management challenges if not addressed early.
Strategic Implications for Decision Makers
For enterprise and mid-market executives evaluating online accounting software, the immediate priority is to reframe selection criteria around workflow continuity and integration economics rather than feature checklists. Platforms should be assessed on their ability to embed into existing financial operations, reduce reconciliation and reporting friction, and support the analytical needs of finance teams as they shift from data processing to interpretation and advisory work. Migration planning should account not only for transaction history and reporting requirements but also for training, process redesign, and the talent implications of higher automation levels. Organizations that treat adoption as a finance-transformation initiative rather than a software upgrade will derive materially greater value.
Cloud Accounting Software Market
For investors and corporate development teams, the market signals point toward selective value creation rather than uniform sector upside. AI-enabled accuracy, ecosystem integration, and enterprise-grade consolidation capabilities are becoming primary drivers of competitive differentiation. Companies that rely solely on commoditized cloud bookkeeping or that lack credible paths to interoperability and workflow depth face margin and retention pressure. Conversely, providers with strong partner networks, clear segment focus, and credible automation roadmaps are positioned to capture share as buyers move from basic digitization to performance-oriented financial tooling. Due diligence should emphasize retention dynamics, integration breadth, customer segment alignment, and infrastructure cost resilience.
For procurement and finance operations leaders, the practical mandate is to build evaluation frameworks that anticipate the next cycle of platform evolution. This includes demanding transparency on data handling, AI-assisted workflows, update cadence, and integration commitments; testing platforms against real operational scenarios rather than scripted demos; and negotiating contracts that preserve flexibility as requirements evolve. Early attention to data governance, user adoption planning, and cross-functional workflow mapping will reduce the risk of fragmented deployments and underutilized capabilities. In practice, the organizations gaining the most from online accounting software are those that align platform selection with broader finance operating models and treat tooling as an enabler of process redesign rather than a standalone purchase.
The strategic landscape of online accounting software is shifting from incremental digitization to integrated financial operations, shaped by AI maturation, infrastructure and regulatory realities, and increasingly connected enterprise ecosystems. Market sizing and growth trajectories provide a useful directional backdrop, but the durable sources of advantage will come from execution quality, workflow depth, and the ability to reduce friction across the full finance function. Decision makers who evaluate platforms with these dynamics in mind, and who seek detailed segmentation, vendor benchmarking, and region-specific deployment considerations, will be better positioned to convert market growth into operational advantage. For a closer examination of segment-level dynamics, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting market research report offers a more granular view of the opportunities and trade-offs ahead.
For detailed analysis of this topic, please visit the official page: Online Accounting Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Foaming Creamer Market: Strategic Trends and Commercial Opportunities Beyond Steady Growth
Market Snapshot and Structural Challenges
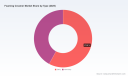
The global foaming creamer market has demonstrated consistent, albeit moderate, expansion over the past half-decade, moving from approximately 150.0 million USD in 2020 to an estimated 189.5 million USD in 2025. This trajectory reflects a compound annual growth rate of 3.5 percent, with projections pointing toward 240.25 million USD by 2032. While the growth pace is not explosive, it signals a mature yet resilient category where incremental innovation and regional penetration matter more than headline expansion. The market’s stability is anchored in its dual role: serving as a functional ingredient for beverage formulation and as a value-enhancing component in foodservice and retail channels.
Beneath the steady valuation curve lies a set of structural inflection points that demand strategic attention. First, raw material dependency remains a persistent volatility driver. Foaming creamer powders require precise formulation parameters, typically relying on 18–24 percent milk solids and 19–23 percent fat content sourced from dairy or palm and coconut oil derivatives. Fluctuations in agricultural commodity pricing, coupled with shifting sustainability expectations around palm oil and dairy sourcing, create margin compression risks for manufacturers that lack diversified supply architectures.
Second, regulatory scrutiny is intensifying across major markets, particularly around labeling transparency, additive disclosures, and nutritional claims. In the United States, food safety authorities continue to monitor foaming creamer products for compliance with health and safety criteria, while the European Union maintains stringent oversight of non-dairy ingredients, emphasizing clean-label alignment and plant-based standard adherence. Compliance is no longer a checkbox exercise; it is a competitive differentiator that shapes consumer trust, retail placement, and cross-border trade feasibility.
Non-dairy Creamer Market
Third, production economics remain tightly linked to specialized infrastructure and labor-intensive quality control. Spray-drying processes, which are essential for achieving stable foam characteristics in both hot and cold applications, require dedicated facilities and rigorous formulation oversight. This creates a barrier to entry but also concentrates operational complexity among established players. Companies that cannot manage the intersection of process precision, ingredient sourcing, and cost efficiency will struggle to scale profitably in an increasingly price-aware environment.
Core Drivers Shaping Market Trajectory
Technological evolution in ingredient engineering continues to redefine what foaming creamers can deliver. The shift from generic texture enhancement to controlled foam architecture—where stability, mouthfeel, and layering are engineered for specific brewing systems and instant beverage formats—has opened new formulation pathways. Granulation and spray-drying advancements enable manufacturers to tailor fat-to-solids ratios with greater precision, allowing products to perform consistently across single-serve brewing equipment, ready-to-mix beverage applications, and foodservice preparation. This technical maturation is gradually decoupling product performance from reliance on traditional dairy-only inputs, expanding the design space for non-dairy and hybrid formulations.
Policy and regulatory dynamics are simultaneously acting as both constraint and catalyst. Stringent ingredient standards in developed markets are pushing formulators toward cleaner profiles, fewer synthetic additives, and more transparent sourcing narratives. Rather than treating compliance as a defensive cost, leading companies are integrating regulatory alignment into product architecture early in the development cycle. This proactive stance reduces time-to-market friction, strengthens retailer confidence, and positions brands favorably in regions where labeling and nutritional claim verification are becoming purchasing prerequisites. The regulatory environment is therefore reshaping the competitive baseline: products that meet clean-label expectations without sacrificing functional performance are gaining shelf and menu precedence.
Demand-side behavior is shifting along two reinforcing axes: premiumization and convenience. Consumers and foodservice operators alike are prioritizing beverage experiences that combine visual appeal, consistent foam structure, and familiar flavor profiles with rapid preparation. Instant drink formats, specialty coffee applications, and milk tea categories have normalized the expectation that a creamer should contribute not just richness but also a stable, enduring foam layer. At the same time, retail and foodservice buyers are seeking formulations that simplify inventory management, reduce preparation variability, and support menu standardization across locations. This convergence favors products designed for predictable performance in both hot and cold systems, with application versatility becoming a key purchasing criterion.
Supply chain and cost structure evolution is introducing both pressure and opportunity. Labor-intensive formulation and quality control steps, combined with the need for specialized spray-drying infrastructure, mean that production efficiency is increasingly tied to process automation, batch consistency, and supplier coordination. Companies that invest in tighter quality loops, ingredient traceability, and flexible production scheduling are better positioned to absorb raw material volatility while maintaining consistent output. Conversely, fragmented sourcing strategies and underinvestment in process control can quickly erode margin stability when commodity inputs or logistics costs shift. The net effect is a market where operational discipline is becoming a strategic asset as much as formulation expertise.
Competitive Landscape and Positioning Dynamics
The competitive field is characterized by a mix of specialized regional players and broader ingredient groups, with the top three firms collectively accounting for roughly 45 percent of market revenue and the top five reaching approximately 65 percent. This concentration reflects a market where scale, process capability, and application-specific formulation knowledge confer meaningful advantages, yet it also leaves room for targeted entrants that solve specific performance or compliance gaps.
Chia-Tza-Teng International Co., Ltd. has built its positioning around foaming creamer powders engineered for instant thick foam in coffee and milk tea sachets, leveraging granulation technology to deliver 18–24 percent milk solids and 19–23 percent fat content. Its recent catalog expansion in early 2026 signals continued investment in product visibility and application breadth, reinforcing a strategy centered on formulation consistency and format-specific performance. Royal FrieslandCampina N.V. has differentiated through its Kievit® Vana-Cappa line, which focuses on creating a stable foam layer with lasting texture for instant drinks and single-serve brewing systems. This positioning aligns closely with the convenience and standardization demands of modern foodservice and retail beverage formats, emphasizing reliability across preparation methods. Kerry Group plc, through its Almer division, supplies spray-dried foaming creamer powders for hot and cold beverages, with sourcing flexibility spanning palm or coconut oil bases. Its strategy highlights application adaptability and infrastructure alignment, recognizing that stable foam performance depends as much on drying and formulation control as on ingredient selection. PT Lautan Natural Krimerindo operates with a focused non-dairy orientation, manufacturing foaming creamer specifically designed to deliver coffee froth on top of beverages. Its participation in major trade platforms, including Food Taipei Mega Shows in mid-2026, underscores a regional growth play that targets emerging beverage categories and export-oriented distribution channels.
The landscape is evolving along a dual path of consolidation and segmentation. Larger ingredient groups are leveraging integrated supply chains, regulatory expertise, and cross-application portfolios to defend share and capture adjacent opportunities. At the same time, specialized manufacturers are carving out niches by emphasizing format-specific foam performance, regional taste preferences, and cost-competitive non-dairy alternatives. New entrants tend to succeed not by competing on broad commodity positioning, but by solving a precise formulation, compliance, or distribution challenge that incumbents are not optimized to address. This dynamic suggests that the next phase of competition will be less about overall market size and more about application ownership, ingredient transparency, and supply chain agility.
Worldwide Shaving Foam Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, clean-label and plant-forward formulation will move from differentiation to baseline expectation. As regulatory frameworks tighten and consumer preferences continue to favor transparent ingredient lists, foaming creamers that deliver stable performance with simplified profiles will capture disproportionate attention in retail and foodservice procurement. The commercial opportunity lies in developing formulations that maintain foam integrity and mouthfeel while reducing additive complexity and aligning with regional plant-based standards. Companies that invest early in this transition will be better positioned to secure shelf placement, streamline compliance, and respond to buyer requirements without last-minute reformulation.
PW Consulting
Second, application-specific engineering will become a more decisive competitive lever. Foam stability, temperature tolerance, and texture consistency are increasingly evaluated against specific use cases, from single-serve brewing systems to instant beverage mixes and foodservice milk tea preparation. The opportunity here is to design product architectures that are validated across multiple preparation environments, reducing formulation risk for buyers and enabling broader deployment. Manufacturers that can document performance across hot and cold systems, provide clear usage guidance, and support menu standardization will find stronger purchase justification and higher switching costs for their customers.
Third, supply chain resilience and input diversification will separate scalable operators from marginal players. Given the reliance on dairy solids, palm or coconut oil derivatives, and specialized drying infrastructure, companies that build flexible sourcing strategies, monitor commodity exposure, and invest in process consistency will be more capable of protecting margins during volatility. The associated opportunity is to pair ingredient flexibility with formulation stability, ensuring that changes in raw material inputs do not compromise foam performance or regulatory alignment. Risks remain, particularly where procurement strategies are overly concentrated, where reformulation capacity is limited, or where regional compliance requirements shift faster than product development cycles can accommodate.
Actionable Directions for Decision-Makers
For manufacturers, the priority should be to align formulation strategy with both performance validation and regulatory foresight. Investing in application testing across hot and cold beverage systems, documenting foam stability and texture consistency, and building ingredient architectures that can accommodate sourcing variation without sacrificing clean-label compliance will create durable advantages. Companies should also evaluate where spray-drying capacity, quality control rigor, and batch consistency can be strengthened to reduce operational risk and improve margin predictability.
For investors, the strategic question is less about overall market growth and more about which capabilities will command pricing power and share resilience. Interest should center on players that demonstrate differentiated application engineering, flexible ingredient sourcing, and a credible path to clean-label compliance across key regions. Monitoring how incumbents and niche players respond to regulatory evolution, raw material volatility, and foodservice standardization trends will provide early signals about which business models are most likely to scale profitably.
For procurement and sourcing leaders, the focus should be on reducing formulation and supply risk while securing consistent beverage performance. This means prioritizing suppliers that can provide transparent ingredient profiles, validated foam stability across intended applications, and clear guidance on usage compatibility with existing brewing or mixing systems. Building redundancy into sourcing, evaluating total cost beyond unit price, and requiring documentation that supports labeling and nutritional claim compliance will help protect product quality and reduce downstream disruption.
Closing Perspective
The foaming creamer market is entering a phase where steady valuation growth masks increasingly important shifts in formulation expectations, regulatory alignment, and supply chain discipline. Companies that treat these shifts as strategic design constraints rather than operational nuisances will be better positioned to capture application-specific demand, defend margins, and expand into higher-value beverage categories. For decision-makers seeking deeper segmentation data, regional demand patterns, and tailored recommendations aligned with specific product portfolios or investment criteria, a detailed market report can provide the granular context needed to convert these directional insights into execution plans.
For detailed analysis of this topic, please visit the official page: Foaming Creamer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Snow Chain Market 2026: Beyond 5.35% CAGR, Unpacking $298M Growth Drivers
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Snow Chain Market: A 2025 Executive Briefing
The snow chain market is navigating a period of measured expansion, shaped by evolving winter preparedness requirements, shifting product preferences, and tightening performance expectations across regions. From 2020 through 2025, the industry built a steady growth trajectory, with 2025 standing as the latest confirmed baseline. Looking ahead through the forecast horizon to 2032, market momentum is projected to continue at a compound annual growth rate of 5.35%, translating into a measured but consistent uplift in total value over the period. Rather than signaling a sudden surge, this pace reflects a maturing market where incremental innovation, regulatory alignment, and demand-side habit changes are working in tandem. For decision-makers, the implication is clear: snow chains are no longer treated as a seasonal commodity alone, but as a regulated, performance-critical component of winter mobility ecosystems.
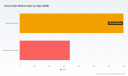
The broader market structure reflects a balanced mix of traditional and alternative traction solutions. Metal-based systems continue to command the largest share of attention, particularly where durability, load capacity, and repeated mechanical use are prioritized. Nonmetal alternatives, including textile traction devices, have carved out a meaningful position by emphasizing ease of handling, lower vehicle impact, and quick deployment. This dual-track product landscape matters because it mirrors a broader industry shift: buyers are increasingly weighing convenience and compliance alongside raw strength. At the same time, concentration remains comparatively moderate, with the top three players accounting for roughly a quarter of the market and the top five approaching just over a quarter. That fragmentation does not indicate weakness; instead, it points to a space where regional specialization, application expertise, and product positioning still create room for distinct competitive advantages.
Market Context and Core Structural Challenges
Despite the favorable growth outlook, the snow chain industry is not moving through calm waters. Executives evaluating participation, investment, or procurement strategies should pay close attention to a set of structural tensions that are reshaping how products are designed, sold, and deployed.
Polarized Demand Between Durability and Convenience
One of the persistent challenges in this market is the tension between long-established metal chain expectations and the growing appeal of lightweight, user-friendly traction alternatives. Metal chains remain the default in environments where repeated use, heavy loads, and harsh surface conditions are common. Their strength and familiarity make them the safe choice in many fleet, construction, and mountainous logistics settings. At the same time, textile and composite products are gaining credibility among passenger vehicle owners and lighter commercial users who value faster installation, reduced wear on road surfaces, and simpler storage. The challenge for manufacturers and distributors is not simply offering both categories, but aligning each with the right use case, performance claim, and pricing logic without blurring distinctions that matter to regulators and end users.
Regulation as Both Catalyst and Complexity
Winter traction requirements are undergoing visible updates in multiple jurisdictions, increasing the strategic importance of compliance-ready product portfolios. In several markets, authorities have refined expectations around when traction devices must be carried or fitted, and in some cases they have clarified preferred device types for specific conditions or vehicle classes. This is beneficial for the market as a whole because it strengthens the practical case for carrying chains or approved alternatives. Yet it also introduces complexity. Regulations can favor particular technologies in particular contexts, encourage faster product cycles, and raise the bar on documentation, testing, and quality assurance. Companies that treat compliance as an afterthought risk losing credibility with fleet buyers, dealer networks, and public-sector procurement teams.
Quality, Standards, and the Cost of Trust
A third challenge lies in the increasing expectation that traction products meet consistent international quality, safety, and environmental standards. Certified manufacturers are expected to demonstrate not only fit and function, but also controlled production practices and reliable performance under variable winter conditions. This raises the barrier for informal or loosely managed entrants and rewards players that have invested in disciplined manufacturing and testing. For the broader market, the upside is stronger buyer confidence and less price-only competition. The downside is that margins can be pressured when companies must absorb higher compliance, testing, and documentation costs while still competing in a fragmented landscape.
Key Drivers Reshaping the Snow Chain Market
The market’s trajectory is being pushed forward by several reinforcing forces. None of these drivers operates in isolation; together, they are redefining which products win, where growth concentrates, and how quickly new solutions can scale.
Technology and Product Design Innovation
Product innovation remains one of the most visible levers in the market. Easy-fit mechanisms, improved tensioning systems, more predictable fitment across tire sizes, and clearer integration with vehicle specifications are all helping reduce the friction historically associated with traction devices. In parallel, textile-based traction products have matured as practical alternatives in defined use cases, giving buyers a lighter, less intrusive option that can satisfy many everyday winter-driving needs. The strategic significance of this innovation is not limited to convenience. Better design lowers the barrier to proper use, which matters because a traction device only delivers value if it is deployed correctly and consistently. Companies that reduce installation time, improve fit confidence, and make storage and transport easier are indirectly strengthening compliance and safety outcomes.
A Regulatory Environment That Is Becoming More Explicit
Recent winter-equipment updates provide a clear example of how policy can shape demand. In France, mandatory winter equipment requirements for designated mountainous areas have been refreshed for the November 2025 to March 31, 2026 period, with metal snow chains or textile snow socks specified as acceptable options for light vehicles and vans. The same guidance also notes that metal chains are recommended over textile socks for frequent use in mountainous settings during that window. This distinction is strategically important because it signals that authorities are not treating all traction devices as interchangeable in every context. Meanwhile, in Colorado, a revised Passenger Vehicle Traction Law effective from fall 2025 requires chains or approved alternative devices for some 4WD/AWD vehicles without qualifying winter tires during severe storms. These changes reinforce a broader point: traction requirements are becoming more specific, more conditional, and more tied to real-time severity rather than generic seasonal memory. For manufacturers, that means product messaging must be precise, and portfolios must be flexible enough to address both baseline mandates and storm-triggered enforcement.
Changing User Behavior and Vehicle Mix
Demand-side behavior is shifting in ways that favor both safety and versatility. Across passenger and light commercial segments, users increasingly expect traction solutions that can be deployed without specialized effort, stored compactly, and trusted to work across a range of conditions. At the same time, vehicle fleets are not uniform; the proportion of all-wheel and four-wheel drive vehicles, varying tire sizes, and mixed light-commercial use patterns complicates one-size-fits-all product logic. Buyers are therefore looking for solutions that reduce uncertainty: clear fit guidance, application-specific recommendations, and devices that can be justified as a practical part of winter readiness rather than an emergency-only purchase. The business implication is that product leadership increasingly depends on the surrounding experience—guidance tools, compatibility clarity, and confidence in real-world performance—as much as on the chain itself.
Tire Protection Chains Market
Supply Chain Discipline and Cost Structure Pressures
Cost dynamics are also shaping strategy. Materials, production consistency, logistics, certification, and inventory planning all influence the final economics of traction products. Because snow chains are highly seasonal in many markets, inventory misalignment can create noticeable margin volatility. In addition, standards-aligned manufacturing and testing add structural cost but also create differentiation. Companies that can balance disciplined cost control with dependable quality are better positioned to serve both price-sensitive volume channels and performance-sensitive buyers. The supply chain challenge, then, is not simply to cut cost, but to manage a more complex value equation in which reliability, certification, and availability are all part of the price proposition.
Competitive Landscape and Leadership Strategies
The competitive field in this market is shaped by players with distinct regional strengths, product orientations, and customer interfaces. Rather than a single dominant template, the landscape shows several viable paths to relevance, each tied to a different interpretation of what buyers value most.
Differentiated Positioning Among Established Players
Several companies illustrate how strategic positioning can diverge even within the same category. Pewag Group has built a manufacturing footprint spanning Austria, the Czech Republic, and Pueblo, Colorado, supporting production for cars, SUVs, light trucks, heavy trucks, and utility vehicles. That broad vehicle coverage and multi-site production structure suggests an emphasis on scale, application breadth, and supply resilience across heavier-duty and utility segments. König, by contrast, has carved an identity around consumer-facing snow chains with patented easy-fit technologies and vehicle integration solutions. Its approach highlights the importance of usability and product design in the passenger and light-vehicle segments, where fit confidence and installation simplicity can be decisive purchase factors. RUD Group contributes a wider traction-device narrative, spanning snow chains, automatic traction chains, and off-road traction devices for passenger, truck, and industrial vehicles. That positioning gives the company a bridge between classic winter traction and more specialized mobility demands, which can be valuable in mixed-use and industrial contexts.
PW Consulting
Thule Group adds another angle by developing snow chains and traction devices with an emphasis on integration with vehicles and accessories, reflecting a broader mobility-and-safety ecosystem mindset. Peerless Chain Company reinforces the North American market with light truck, SUV, and passenger snow chains, including Auto-Trac automatic models and tire finder tools. The inclusion of fitment tools is notable because it lowers the friction of choosing the right device, an important commercial advantage in channels where compatibility questions often slow purchase decisions. Quality Chain Corp stands out as a major North American wholesaler and supplier for passenger cars, light trucks, and SUVs, underscoring the continued importance of distribution strength and channel reach in a market where availability during the winter window can be as important as product design. AutoSock Operations AS represents the textile traction segment, offering lightweight snow socks as an alternative traction device that meets recognized safety expectations. Its presence in the competitive landscape signals that alternative-material traction is now an established commercial category, not a niche curiosity.
How the Landscape Is Evolving
Several evolution patterns are worth watching. First, the market appears to be strengthening around players that can combine regional presence with product clarity. Companies that serve both consumers and professional buyers often need separate value propositions, because the criteria for purchase differ: everyday users prioritize ease and confidence, while fleets and commercial operators prioritize durability, compliance, and operational consistency. Second, the competitive field is likely to see continued specialization rather than only broad consolidation. The presence of strong wholesalers, integrated mobility brands, automatic-traction specialists, and textile-alternative producers indicates that customers are choosing among different solution philosophies. Third, new entrants or expanding players may gain ground by reducing friction in fitment, improving transparency around compatibility, or offering stronger warranty and support structures that make winter-readiness purchasing less risky. In a moderately concentrated market, differentiation can be achieved through experience, distribution, and application focus as much as through raw product novelty.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, the snow chain market is likely to be shaped by a small number of high-impact trends. Each carries both opportunity and risk, and the strategic value lies in identifying where a company’s capabilities can align with the direction of demand.
Traction Products as Part of a Compliance-Driven Readiness Model
Winter traction is increasingly treated as part of a broader readiness discipline rather than an optional accessory. As winter equipment expectations become more defined and more conditional, buyers in both consumer and commercial channels are likely to seek products that fit cleanly into compliance planning, fleet policies, and seasonal preparation routines. The commercial opportunity here is to build portfolios and support systems that make readiness easier to implement at scale. That can include clearer application guidance, stronger fitment tools, and product lines that map well to common regulatory scenarios. The risk is that generic or poorly positioned offerings may be squeezed out when buyers compare devices against explicit legal or policy requirements rather than convenience alone.
Continued Expansion of Alternative Traction Solutions in Defined Use Cases
Textile and other nonmetal traction alternatives are likely to continue gaining relevance in specific segments where ease of use, lower vehicle impact, and quick deployment are particularly valuable. The opportunity lies in matching these products to the right conditions and communicating their strengths without overstating their applicability. In mountainous or frequent-use contexts, the preference for metal chains in some guidance underscores the need for balanced portfolio strategy. Companies that can clearly differentiate where each technology fits—and why—will be better positioned to defend margin and customer trust. The risk is mis-positioning: if alternative traction products are sold into use cases where durability or abrasion resistance is the priority, satisfaction and reputation can erode quickly.
Standardization, Quality Assurance, and the Premium on Reliability
As expectations around quality, safety, and certification become more embedded across regions, reliability is likely to command a stronger premium. This favors manufacturers and distributors that can demonstrate consistent production, controlled quality systems, and credible performance claims. The commercial opportunity is to use quality assurance not only as a compliance expense, but as a market-facing differentiator that supports pricing, buyer confidence, and institutional sales. The uncertainty is that standards and enforcement expectations can continue to evolve, and companies that do not keep pace may face both commercial and reputational exposure.
Strategic Actions for Decision-Makers
For executives operating in or adjacent to this market, the most valuable next step is to convert high-level trends into concrete decisions about product mix, channel strategy, and compliance readiness.
Winter Tire Market
For Manufacturers and Product-Led Players
Build product architectures that separately address durability-critical, ease-of-use, and compliance-driven scenarios. A strong portfolio should make it obvious which device is intended for repeated mountain use, which is optimized for quick deployment, and which is best suited to a particular vehicle class or regulatory context. It is equally important to invest in fitment clarity and compatibility tools, because reducing selection friction can improve both conversion and proper use. Manufacturers should also treat certification and quality discipline as market-facing assets, not back-office requirements, especially when institutional buyers and larger fleets evaluate suppliers.
For Investors and Strategic Acquirers
Evaluate opportunities through the lens of channel strength, application coverage, and regional regulatory alignment rather than product category alone. A distributor with strong winter-window availability in key markets, a manufacturer with broad vehicle coverage, or a brand with a strong usability and integration story can each create defensible positions. Due diligence should pay close attention to seasonality risk, inventory planning, certification readiness, and the ability to serve both consumer and professional buyers without blurring the value proposition. Businesses that combine product credibility with dependable supply and clear positioning are likely to be more resilient than those competing primarily on price.
For Fleet Operators, Dealers, and Procurement Teams
Treat traction procurement as a readiness investment with compliance and safety implications, not merely a seasonal purchase. Selection should be informed by vehicle mix, likely operating conditions, and the specific requirements that apply in the regions where vehicles operate. Where conditions include frequent mountainous use or strict enforcement windows, it is prudent to match device type to the intended use pattern and to ensure that driver training, storage, and inspection practices support correct deployment. Procurement strategies that incorporate fitment tools, clear compatibility checks, and dependable seasonal availability can reduce operational risk more effectively than purchasing decisions based on lowest unit cost alone.
Closing Perspective
The snow chain market is entering a phase in which growth is steady, but the definition of winning is becoming more nuanced. Regulatory clarity, product innovation, application-specific demand, and quality expectations are all pushing the market toward more disciplined competition. The companies and buyers that benefit most will be those that treat traction devices as part of a broader winter-mobility strategy: the right device for the right condition, supported by clear guidance, reliable supply, and credible quality. For organizations seeking more granular segmentation, regional dynamics, and tailored strategic options, a closer look at the full research scope can help translate these market signals into precise action plans.
For detailed analysis of this topic, please visit the official page: Snow Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Sampling Pumps Market: Why 4.53% CAGR and Asia Pacific Demand Redefine Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Air Sampling Pumps Market
Market Trajectory and Structural Pressures
The global air sampling pumps market has established a consistent growth trajectory, with revenue reaching approximately USD 59.34 million in 2025 and projected to climb to USD 80.4 million by 2032. This expansion reflects a compound annual growth rate of 4.53 percent across the 2026 to 2032 forecast period, signaling steady demand evolution rather than speculative boom cycles. Historical performance from 2020 through 2025 shows incremental gains, with year-over-year increases ranging from modest to moderate, reinforcing a market driven by regulatory compliance, occupational health priorities, and environmental monitoring requirements rather than volatile consumer behavior.
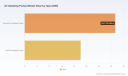
Within this landscape, regional concentration patterns reveal distinct maturity levels. Asia Pacific currently commands the largest revenue share, followed by North America and Europe, while Latin America and the Mideast and Africa represent smaller but developing footprints. The geographic distribution aligns closely with industrial activity density, regulatory enforcement intensity, and the spread of occupational hygiene programs. Product segmentation remains balanced between personal air sampling pumps and area air sampling pumps, each serving distinct monitoring requirements. Application-wise, industrial manufacturing, health industry, and environment industry collectively anchor demand, though their relative weight shifts as regional compliance priorities mature.
Key Challenges and Inflection Points
Despite the predictable growth path, the market faces structural challenges that will test vendor positioning and buyer decision-making in the coming years. The first challenge centers on regulatory alignment across jurisdictions. Monitoring standards increasingly demand tighter control over flow stability, pulsation limits, and post-calibration verification. Equipment that previously met baseline requirements may now fall short when deployed in regions adopting upgraded directives or stricter interpretation of existing standards. Manufacturers must balance compliance readiness with cost accessibility, particularly when serving multi-regional clients with divergent enforcement timelines.
The second challenge involves the tension between precision and portability. Occupational and environmental monitoring teams increasingly require devices that maintain laboratory-grade accuracy while fitting into confined workspaces, mobile monitoring setups, or rapid-deployment scenarios. Engineering teams must navigate competing design priorities: smaller form factors, extended battery performance, and reduced weight must not compromise calibration consistency or flow reliability. Buyers evaluating procurement options often face trade-offs between ruggedized configurations for heavy industrial settings and compact units optimized for indoor air quality or healthcare environments.
A third inflection point relates to market concentration and buyer leverage. The market remains moderately consolidated among established manufacturers, which creates both stability and pricing pressure. While leading vendors benefit from brand recognition, service networks, and long-standing compliance credentials, buyers are increasingly equipped with more information and alternative sourcing options. This dynamic pressures incumbents to justify premium positioning through demonstrable performance advantages, service quality, and integrated support ecosystems rather than heritage alone.
Core Growth Drivers Reshaping Demand
Technology Innovation and Performance Evolution
Product development is shifting from basic flow delivery toward smarter monitoring capability. Recent catalog updates and product introductions signal a clear direction: manufacturers are refining pump platforms to address flow stability, pulsation control, calibration ease, and connectivity for workflow integration. For example, updated personal sampling pump catalogs have introduced refined model specifications that emphasize usability, calibration verification, and application-specific configurations. Meanwhile, new portable air sampling pump additions reflect demand for lighter, more adaptable equipment in indoor air quality and environmental monitoring contexts.
This innovation trajectory matters because it connects directly to operator efficiency and data confidence. Devices that simplify calibration, reduce setup time, and maintain stable flow characteristics under variable conditions reduce the risk of non-compliant sampling results. In practical terms, engineering improvements are not merely product features; they are risk mitigation tools for industrial hygienists, safety managers, and environmental consultants who must produce defensible monitoring records.
Active Air Sampler Market
Regulatory and Standards Pressure as Compliance Catalyst
Regulatory frameworks continue to act as one of the strongest demand drivers. Occupational exposure monitoring depends on methods that require calibrated air sampling pumps with stable flow performance, and several standards reinforce this expectation. ISO 13137:2019, for instance, requires personal sampling pumps to maintain pulsation not exceeding 10 percent of the flow rate to support accurate workplace exposure monitoring. NIOSH NMAM methods reinforce the need for constant flow in analyses involving asbestos, lead, and crystalline silica. OSHA sampling methods further specify flow ranges and post-calibration verification expectations for personal air sampling pumps.
At the regional level, the EU Worker Exposure Directive revision has strengthened pulsation and flow stability requirements across member states, raising the compliance bar for organizations operating in Europe or supplying equipment into that market. These regulatory dynamics create a structural pull for equipment that can demonstrably meet evolving requirements. They also raise the stakes for buyers who must ensure that monitoring programs remain defensible during audits, incident investigations, or internal compliance reviews.
Demand-Side Shifts in Occupational Health and Environmental Monitoring
Demand is increasingly shaped by a broader interpretation of exposure risk. Industrial operations continue to represent a major application base, but health industry and environment industry usage is expanding as organizations broaden monitoring beyond traditional manufacturing floors. Healthcare settings, public facilities, and indoor air quality programs are driving interest in portable and area monitoring equipment that can support indoor environments, infection control-related airflow assessments, and general environmental surveillance.
Simultaneously, workplace safety culture is becoming more data-oriented. Safety teams are placing higher value on repeatable measurements, documented calibration, and equipment that integrates smoothly into field workflows. This shift favors vendors that can support not only the hardware but also the operational discipline surrounding sampling programs. In effect, the market is rewarding solutions that make compliance easier to execute consistently rather than only occasionally.
Supply Chain Realities and Cost Structure Considerations
Cost structures remain an important factor in procurement decisions, especially as organizations balance compliance budgets against broader operational spending. While the market is not experiencing volatile commodity shocks as a dominant narrative, equipment durability, service availability, and replacement part accessibility still influence total cost of ownership. Procurement teams increasingly evaluate pumps not as isolated instruments but as part of a monitoring system that includes calibration equipment, maintenance support, and training.
This broader purchasing lens benefits manufacturers with strong service networks and transparent support models. It also elevates the importance of product longevity and maintainability. In segments where buyers deploy equipment across multiple sites or rotating crews, reliability and service responsiveness can outweigh marginal price differences. As a result, suppliers that can deliver consistent field performance and predictable upkeep gain an advantage in multi-year purchasing decisions.
Competitive Landscape and Strategic Positioning
Established Players and Differentiating Strengths
The market features a set of well-known manufacturers with distinct product and service orientations. SKC Inc. has built recognition around personal air sampling pumps used in occupational exposure monitoring, with pump families designed for field sampling workflows. Sensidyne LP is associated with Gilian personal and high-flow air sampling pumps, along with calibrators supporting industrial hygiene and area sampling, which positions the company at the intersection of sampling and calibration equipment. Zefon International, Inc. offers personal and area environmental monitoring pumps, expanding its relevance across both occupational and environmental use cases. Casella USA provides personal air sampling pumps with connectivity features aimed at workplace exposure assessments, reflecting a strong emphasis on usability and field integration.
These companies differentiate not only through product specifications but also through how they support compliance workflows. Some compete on pump performance and pulsation control. Others emphasize calibration tools, training, documentation support, and field-ready design. The practical distinction for buyers often lies in whether the vendor can reduce the operational burden of sampling programs through integrated hardware, calibration consistency, and reliable after-sales support.
Recent Developments as Indicators of Strategic Focus
Recent company activities provide insight into how incumbents are navigating the market. Trade show participation by major pump and calibrator suppliers has continued through 2025, with exhibition activity at industry events highlighting ongoing engagement with occupational hygiene communities. These appearances are not mere marketing exercises; they function as channels for demonstrating flow performance, calibration practices, and equipment reliability to audiences that evaluate compliance-critical tools.
Product catalog updates have also underscored incremental innovation. Updated pump catalogs have introduced refined model details, while newer portable pump additions have broadened portfolios for indoor and environmental monitoring applications. Such moves suggest that established manufacturers are pursuing portfolio expansion and specification refinement rather than disruptive product replacement. This measured approach aligns with a market where compliance acceptance, service history, and user familiarity carry significant weight.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure appears likely to evolve through a combination of consolidation and targeted differentiation. Moderate market concentration gives leading firms room to defend positions through service networks and compliance credentials, but it also leaves space for specialized entrants in subsegments such as compact indoor air quality monitoring, improved connectivity for field data workflows, or region-specific compliance configurations. Potential consolidation may occur where service coverage, calibration support, and geographic reach become decisive purchase factors.
At the same time, fragmentation remains possible in application-specific niches. Buyers in healthcare environments, environmental consulting, or specialized industrial processes may prioritize features that larger generalist portfolios do not fully optimize. This creates opportunity for companies that can deliver focused solutions, provided they can also meet the compliance and reliability expectations associated with sampling instrumentation.
Forward-Looking Trends and Commercial Implications
Trend 1: Compliance-Driven Product Specifications Will Become a Baseline Expectation
Over the next three to five years, flow stability, pulsation control, and calibration verification are likely to transition from desirable features to baseline requirements in many procurement processes. As regional directives and occupational hygiene methods continue to reinforce consistent sampling performance, equipment that cannot document stable performance will face increasing friction in regulated environments. The commercial implication is clear: manufacturers that proactively align product design and documentation with evolving standards will reduce adoption barriers for compliance-focused buyers.
For procurement teams, this trend increases the importance of verification. Purchasing decisions will need to account not only for flow range and portability but also for how easily a pump can be calibrated, verified, and documented in routine use. Equipment that simplifies compliance workflows will likely command stronger preference in competitive bids.
Trend 2: Connectivity and Field Workflow Integration Will Gain Commercial Weight
As monitoring programs become more data-driven, devices with Bluetooth connectivity, streamlined field setup, and better integration into exposure assessment workflows will become more relevant. Connectivity does not replace measurement accuracy, but it can reduce administrative burden, improve record-keeping consistency, and support faster field decisions. In practical terms, the market is moving toward tools that help teams manage sampling programs more efficiently, not just collect samples more accurately.
Microbial Air Samplers Market
This trend opens commercial opportunities for vendors that can link hardware performance with workflow convenience. It also creates a differentiation path for companies that can demonstrate tangible improvements in setup time, calibration tracking, and exposure assessment documentation. The risk for buyers is overvaluing connectivity without confirming that core sampling performance still meets required standards.
PW Consulting Automotive & Machinery Research Center
Trend 3: Application Diversification Will Redefine Competitive Priorities
Industrial manufacturing will remain a core demand base, but growth in health industry and environment industry applications will encourage product strategies that address a wider range of monitoring contexts. Portable equipment for indoor environments, area sampling for environmental programs, and adaptable configurations for varying flow requirements will become more commercially important. Companies that can serve multiple application profiles without sacrificing compliance credibility will gain broader market relevance.
The corresponding risk is portfolio over-extension. Manufacturers expanding into new application areas must ensure that product claims, calibration support, and service models remain credible for each use case. Buyers in specialized settings will quickly distinguish between equipment that is genuinely suited to their environment and equipment that is merely marketed into it.
Strategic Recommendations for Decision-Makers
For Manufacturers and Suppliers
Prioritize compliance documentation and performance verifiability as core product assets. In a market where regulatory expectations continue to tighten, spec sheets alone are insufficient. Suppliers should ensure that product platforms clearly support flow stability, pulsation control, and calibration verification, and that this support is easy for customers to demonstrate in audits and field use. Equally important is service and calibration support; in compliance-driven purchasing, reliable after-sales infrastructure can be as influential as the instrument itself. Companies should also evaluate whether portfolio expansion into indoor air quality, environmental monitoring, or connectivity-enabled workflows creates genuine differentiation or merely broadens exposure without sufficient support depth.
For Investors
Assess exposure to regulatory-driven demand rather than relying solely on end-market growth narratives. Companies with strong positions in occupational hygiene, industrial hygiene, and compliance-related monitoring are better positioned to benefit from sustained standards pressure. Investment due diligence should examine calibration support, service networks, product acceptance in regulated environments, and the ability to maintain performance claims across multiple jurisdictions. Growth potential is likely to be strongest where vendors can combine product reliability with workflow-relevant features and credible documentation. At the same time, investors should monitor whether expansion into lower-margin application areas dilutes margin stability or operational focus.
For Procurement and Operations Leaders
Evaluate sampling pumps as part of a compliance system rather than as standalone hardware purchases. Total value should account for calibration consistency, field usability, service availability, and the ease of maintaining documentation across multiple sites or rotating crews. Where monitoring programs span different environments, consider whether standardized equipment reduces training burden and audit risk, or whether application-specific tools offer better performance despite increased procurement complexity. It is also prudent to confirm that any connectivity or workflow features do not distract from the fundamental requirement of stable, verifiable flow performance.
Closing Perspective
The air sampling pumps market is moving through a phase where regulatory expectations, workflow efficiency, and application diversification are reshaping purchasing logic. Growth is steady and structurally supported, but competitive advantage will increasingly depend on how well manufacturers translate performance and compliance readiness into practical field value. For buyers, the most effective decisions will come from evaluating equipment against both measurement integrity and operational burden. For suppliers and investors, the opportunity lies in aligning product strategy with the compliance-intensive, workflow-sensitive nature of modern exposure monitoring. Detailed segment-level data, regional breakdowns, and customized scenario analysis can further sharpen these decisions for organizations seeking a more precise path through the market's next phase of development.
For detailed analysis of this topic, please visit the official page: Air Sampling Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Enclosure Market: Why 7.5% CAGR and Strategic Shifts Reshape the Industry by 2032
By pmarketresearch, 2026-09-21
Navigating the Electric Enclosure Market: Strategic Trends and Commercial Opportunities
Market Overview and Pressing Challenges
The electric enclosure market has entered a phase of sustained expansion, with revenue projected to grow from approximately $5.5 billion in 2020 to just over $12.2 billion by 2032. This translates to a compound annual growth rate of 7.5 percent over the forecast period, signaling a market that is outpacing broader industrial equipment segments. The trajectory reflects more than cyclical demand; it is being reshaped by fundamental shifts in how electrical infrastructure is designed, deployed, and protected across multiple end-use ecosystems. Growth has been consistent across recent years, with revenue climbing through 2025 and accelerating into the mid-2030s as new infrastructure build-outs and modernization programs scale globally.
Despite the positive outlook, the industry faces structural friction that will separate agile participants from those relying on legacy operating models. First, the widening gap between standardized protection requirements and increasingly demanding environmental conditions is forcing rapid product adaptation. Enclosures must now accommodate submersion-level ingress protection, extreme thermal cycling, and corrosive exposure while maintaining accessibility for maintenance and compliance verification. Second, regulatory complexity is intensifying across jurisdictions. Compliance frameworks around environmental sealing, installation marking, and voltage-specific safety considerations are becoming more prescriptive, raising the cost of non-compliance and narrowing the window for generic solutions. Third, supply chain volatility and input cost fluctuations continue to pressure margins, particularly for manufacturers balancing metallic and non-metallic material portfolios against fluctuating steel, polymer, and casting costs. These dynamics are not isolated headwinds; they are reshaping competitive criteria and forcing a reevaluation of where value is created in the enclosure value chain.
PW Consulting Automotive & Machinery Research Center
Key Drivers Reshaping Market Trajectory
Technological Innovation and Performance Thresholds
Performance expectations for electric enclosures have evolved beyond basic containment. The integration of advanced sealing architectures, corrosion-resistant material formulations, and pre-engineered mounting interfaces is enabling faster deployment in environments that previously required custom engineering. Die-cast and rigid enclosure platforms are increasingly being offered with expanded ingress protection ratings and surface-mount options, reducing on-site fabrication time and improving consistency across installations. Simultaneously, climate control integration and thermal management features are becoming standard considerations for enclosures deployed in energy distribution, industrial automation, and data center-adjacent applications. This shift is moving enclosures from passive housings toward integrated protection systems, where reliability, serviceability, and environmental resilience directly influence procurement decisions.
Electronic Plastic Enclosure Market
Policy, Standards, and Compliance-Driven Demand
Regulatory and standards-based requirements are becoming a decisive filter in procurement. Enclosures used in electrical installations must align with recognized environmental protection classifications, installation marking directives, and safety considerations for systems operating up to higher voltage thresholds. In parallel, underground utility enclosures and power distribution assets are subject to specifications that address longevity, accessibility, and environmental safety. These requirements are not static; they are tightening in sectors where failure costs are high, such as EV infrastructure and data center power ecosystems. As a result, compliance capability is increasingly a market entry condition rather than a differentiator, pushing manufacturers to standardize certification pathways and design products that can satisfy multiple jurisdictional expectations without costly customization.
Demand-Side Shifts Across Industrial, Energy, and Utility Applications
Demand is being pulled from multiple directions. Industrial control systems continue to represent a substantial share of consumption, but growth is increasingly linked to modernization programs that replace aging enclosures with more durable, modular, and service-friendly alternatives. Energy and power applications are expanding as grid hardening, distributed generation, and EV charging infrastructure accelerate deployment cycles. At the same time, non-metallic conduit and enclosure accessories are gaining traction in applications where weight, corrosion resistance, and installation flexibility matter more than traditional metallic form factors. This diversification is broadening the addressable market while also fragmenting buying criteria, since project owners now weigh environmental exposure, maintenance access, longevity, and installation speed alongside base pricing.
Supply Chain and Cost Structure Evolution
Material availability and pricing dynamics remain central to margin management. Manufacturers with diversified material strategies—spanning steel, stainless steel, fiberglass, and polymer solutions—are better positioned to adapt to regional cost shifts and lead-time disruptions. Procurement teams are also placing greater emphasis on component standardization and interchangeability to reduce inventory complexity and streamline replacement cycles. The competitive advantage is increasingly tied to design efficiency, manufacturing scalability, and the ability to maintain certified product lines without sacrificing responsiveness. Companies that can align material selection with application-specific performance requirements while preserving cost predictability are capturing outsized share in a market where price competition alone is insufficient.
Competitive Landscape and Leading Strategies
Established Players and Strategic Positioning
The market remains moderately concentrated, with the largest players holding meaningful but not dominant shares, leaving room for specialized and regional competitors to thrive through application focus and service capabilities. Leading manufacturers are differentiating through a combination of material breadth, certification maturity, and application-specific engineering rather than volume pricing alone. For example, some firms emphasize rugged die-cast platforms with expanded ingress protection and flexible mounting configurations, targeting environments where reliability and installation simplicity are paramount. Others focus on enclosures designed for harsh conditions, pairing protection with climate control and EV-related inverter solutions to address integrated deployment needs. Utility and underground-focused manufacturers are leaning into below-ground and fiber-reinforced solutions for power distribution, while large industrial suppliers are expanding standard and non-metallic enclosure ranges to serve commercial and industrial projects at scale. Modular, freestanding, and hygienic-design offerings further illustrate how product families are being shaped around maintenance, sanitation, and configuration flexibility. Universal enclosure ranges that span metal, plastic, and polyester options are also being positioned for indoor and outdoor power distribution use, reflecting a push toward cross-environment applicability.
Recent Signals from the Market
Recent product and commercial activity underscores how companies are translating these strategies into executable moves. A major die-cast enclosure supplier introduced an IP68-rated flanged variant with added surface-mount options, extending the versatility of a rugged series for applications requiring higher environmental protection and easier installation alignment. In parallel, a non-metallic conduit specialist expanded its portfolio with new conduit bodies and gang boxes, reinforcing the shift toward lightweight, corrosion-resistant protection solutions for electrical installations. On the commercial side, a diversified enclosures and electrification player reported record first-quarter sales, orders, and backlog while raising full-year guidance, reflecting sustained demand across enclosure-adjacent segments and the confidence of customers in continued infrastructure investment. These developments point to a market where capability expansion, certification readiness, and demand visibility are reinforcing each other.
Market Structure Evolution
The competitive map is evolving along three axes. Consolidation is likely to continue among mid-tier players seeking scale in certification, distribution, and material procurement, while fragmentation will persist where regional compliance nuances, specialized materials, or niche application requirements create barriers to one-size-fits-all offerings. New entrants and adjacent players are finding opportunities in modular design, integrated thermal management, and non-metallic alternatives that lower installation friction. The broader trend is toward portfolios that balance standardized, certifiable platforms with configurable options that reduce custom engineering without sacrificing performance. Companies that can navigate this balance while maintaining regulatory alignment and supply chain resilience are best positioned to capture share as procurement teams increasingly prioritize lifecycle value over upfront cost.
Future Outlook: Trends and Commercial Implications
Higher Protection Standards as a Baseline Expectation
Over the next three to five years, stronger environmental protection and safety alignment will become baseline expectations rather than premium features. This will accelerate adoption of enclosures that already meet rigorous ingress and durability criteria, especially in EV infrastructure, data center power environments, and utility deployments where downtime and exposure risks carry significant financial consequences. The commercial opportunity lies in standardizing certified, high-protection platforms that reduce project risk and accelerate approval timelines. Manufacturers and solution providers that can offer repeatable compliance across multiple environments will see stronger demand pull, while late movers may face rising rejection rates and retrofit costs.
Modular and Configurable Designs as a Growth Multiplier
Configurability is emerging as a powerful growth lever. Modular enclosure systems, interchangeable mounting options, and pre-engineered accessories allow end users to adapt solutions to changing site conditions without redesigning from scratch. This modularity also supports maintenance, expansion, and replacement cycles, aligning product economics with long-term asset management priorities. The opportunity here is not simply offering more parts, but designing families that balance standardization with flexibility, enabling faster specification, reduced inventory burden, and lower field error rates. Solutions that make specification easier and retrofit less disruptive will gain preference in recurring industrial and energy projects.
Material Diversification and Non-Metallic Expansion
Material strategy will increasingly define competitive relevance. As installation environments become more varied and corrosive-resistance requirements rise, non-metallic and hybrid material solutions will capture additional share in specific applications, while stainless steel and fiber-reinforced options continue to serve harsh or sanitary-use conditions. Manufacturers that maintain disciplined material-to-application mapping, supported by reliable sourcing and clear certification documentation, will be better equipped to manage cost swings and meet project-specific constraints. The risk lies in over-indexing on any single material category without adequate application validation, which can create exposure to substitution pressure and regional cost volatility.
Actions for Decision-Makers
For Manufacturers and Solution Providers
Invest in platform-level design that supports multiple protection ratings, mounting configurations, and material options without fragmenting the core product architecture. Prioritize certification readiness and documentation as core capabilities, since compliance now functions as a procurement prerequisite in many sectors. Expand application-specific accessory ecosystems to reduce field customization, and align supply planning with material variability so that lead times and cost structures remain stable as demand scales.
Electric Control Cabinet Market
For Investors and Strategic Buyers
Evaluate exposure to segments where protection requirements are tightening fastest and where backlog visibility suggests durable demand. Look for companies that combine modular design, material flexibility, and strong compliance footprints, since these attributes support both share gain and margin resilience. Assess supply chain and sourcing strategies as indicators of future cost control, and consider how well-positioned a company is to serve energy distribution, industrial modernization, and infrastructure build-outs rather than relying on single-sector cyclicality.
For Procurement and End-User Teams
Shift evaluation criteria toward lifecycle protection, installation efficiency, and compliance certainty rather than lowest initial unit cost. Standardize on enclosure platforms that can be specified across multiple sites and environmental conditions to reduce specification errors and replacement complexity. Where possible, prioritize solutions with clear certification alignment and modular accessory support, since these reduce project risk and improve long-term maintainability as installations evolve.
For decision-makers seeking deeper segmentation, company-level performance benchmarks, regional deployment patterns, and application-specific sizing, a comprehensive market report can provide the granularity needed to translate these trends into precise commercial plans. Detailed breakdowns of product families, end-use demand, competitive positioning, and forward demand scenarios help shorten the path from insight to execution, especially when paired with tailored assessments of where to prioritize investment, sourcing, and specification strategy.
For detailed analysis of this topic, please visit the official page: Electric Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Reinsurance Market 2026: 8.2% CAGR Trajectory and the Real Shifts Reshaping Industry Growth
By pmarketresearch, 2026-09-21
Reinsurance Market: Strategic Shifts and Commercial Opportunities in a Transforming Landscape
The global reinsurance market has entered a phase of structural expansion, driven by a combination of hardening premiums, evolving risk profiles, and accelerating digital transformation. Following a consistent upward trajectory over the past half-decade, the market surpassed the 200-billion mark in 2024 and reached 215 billion in 2025 at the base year level. Forward projections indicate sustained momentum, with the sector expected to grow at a compound annual rate of 8.2 percent through 2032, culminating in a market size approaching 345 billion. This growth is not merely a reflection of cyclical pricing but signals deeper shifts in how risk is transferred, managed, and financed across jurisdictions and asset classes. For executives and capital allocators, the numbers suggest a market that is both scaling and fragmenting in capability, creating pockets of premium returns alongside operational complexity.
Beneath the headline figures lies a market structure that remains moderately concentrated, with the top three players accounting for roughly 29 percent of total revenue and the top five holding just over 30 percent. This distribution indicates that while scale advantages persist, the market is not dominated by a handful of incumbents to the point of stifling innovation or new capacity entry. The relatively flat concentration curve between the third and fifth positions suggests competitive intensity among mid-tier and specialized carriers, particularly in non-life and life lines where pricing, underwriting discipline, and technological stack maturity diverge. The room between the leader cluster and the long tail of participants creates strategic space for platforms, service providers, and niche reinsurers that can differentiate on speed, data integration, or regulatory navigation.
Market Dynamics and Structural Challenges
Pricing Normalization Meets Risk Complexity
The post-2020 expansion reflects a market that has moved through several pricing cycles while absorbing growing exposure to climate-related losses, cyber accumulation, and demographic-driven longevity shifts. Rather than a single shock driving growth, the current phase is characterized by broad-based premium firming, improved loss recognition, and a recalibration of capital allocation toward lines with clearer risk-return profiles. This environment rewards reinsurers and brokers that can price risk with granularity and document assumptions transparently. At the same time, it raises the bar for underwriting rigor and actuarial validation, particularly where reinsured portfolios interact with complex asset structures or long-dated liabilities.
Regulatory Tightening as a Competitive Filter
A second defining challenge is the shifting regulatory architecture, which is reshaping how cedants and reinsurers prove solvency, adequacy, and collateral efficiency. In the United States, Actuarial Guideline 55, approved by the NAIC and effective from the end of 2025, requires cedants to incorporate reinsured business alongside net retained business in asset adequacy testing for statutory reserves. In Europe and comparable markets, solvency frameworks continue to mandate stringent capital equivalence, including 100 percent solvency capital requirement coverage and own-funds thresholds that support collateral-free transactions. These rules elevate the cost of compliance but also create differentiation opportunities for carriers and platforms that can operationalize asset adequacy documentation, investment accelerators, and principles-based bond definitions with minimal friction. The net effect is a market where regulatory fluency is becoming a commercial capability rather than a back-office necessity.
Talent, Automation, and the Cost of Expertise
A third pressure point is the intensifying demand for specialized actuarial and claims expertise. Updated guidelines such as AG 55, combined with tighter supervisory expectations for third-party cloud and AI deployments, increase the operational labor required to complete filings and maintain audit-ready documentation. Teams must interpret evolving asset adequacy standards, align investment matching adjustments, and demonstrate governance over automated reinsurance workflows. Where platforms and processes remain manual or fragmented, labor costs and cycle times expand, eroding margin and slowing decision velocity. Conversely, organizations that embed automation, standardized reporting, and embedded compliance into their reinsurance operations can convert this pressure into a durability advantage.
Key Growth Drivers
Digital Platforms and Automation of the Reinsurance Lifecycle
Technology is moving from experimentation to core infrastructure. Cloud-native reinsurance administration platforms are increasingly automating cessions, recoverables, commission calculations, and claims recovery across both traditional and non-proportional structures. Modular architectures allow insurers and brokers to integrate reinsurance operations with existing policy and finance systems without rip-and-replace disruptions. The emphasis is shifting from point solutions to end-to-end lifecycle coverage that spans contract initiation, ongoing administration, and retrocession management. As these platforms mature, they reduce reconciliation errors, accelerate settlements, and provide data lineage that supports regulatory exams and actuarial review. The recent wave of platform updates and launches underscores this direction, with new releases targeting automated cessions and recoverable tracking for property and casualty insurers and brokers, and sovereign-backed initiatives launching global reinsurance platforms anchored in financial free zones with institutional partners to facilitate cross-border operations.
Regulatory Modernization Enabling More Flexible Asset Deployment
Complementary regulatory changes are expanding the toolkit for matching long-tail liabilities with suitable assets. Principles-based bond definitions and investment accelerator mechanisms introduced in late 2025 are designed to facilitate more flexible asset deployment for matching adjustments within reinsurance portfolios. Alongside solvency frameworks that support collateral-free transactions when capital and own-funds thresholds are met, these developments allow market participants to optimize asset-liability alignment while preserving liquidity and governance standards. The practical implication is that reinsurers and cedants can structure transactions with greater latitude in asset selection and duration matching, provided they can evidence adequacy and maintain robust oversight. This flexibility is particularly valuable for life and annuity lines, where asset duration and crediting strategies interact directly with reinsured liabilities.
Demand-Side Shifts Toward Resilience and Capital Efficiency
On the demand side, primary insurers and corporate buyers are increasingly treating reinsurance as a strategic lever for balance-sheet resilience rather than a pure cost of risk transfer. Harder markets and elevated catastrophe volatility have reinforced the value of capacity certainty, tailored coverage, and transparent terms. At the same time, capital market participants and institutional allocators are exploring avenues to support reinsurance operations, especially in jurisdictions that offer regulatory clarity and operational efficiency. This convergence expands the ecosystem around reinsurance, creating demand for platforms and services that can coordinate ceded and assumed contracts, streamline reporting, and support multi-jurisdiction compliance. Brokers and intermediaries benefit as well, since structured automation reduces processing overhead and improves turnaround for complex placements.
Operational Cost Structures and the Value of Integrated Workflows
Cost structures are being reshaped by the interplay of technology adoption, labor scarcity, and supervisory expectations. As AI-assisted models gain traction in underwriting support, reserving, and claims triage, regulators are increasing governance, risk management, and third-party audit requirements for cloud providers and model operators. Organizations that standardize data, document model usage, and maintain audit trails can harness automation without compromising supervisory confidence. Where workflows remain siloed, the cumulative cost of manual reconciliation, rework, and compliance documentation compresses operating leverage. The emerging competitive logic is clear: integration of policy, finance, actuarial, and reinsurance administration into coherent workflows is becoming a determinant of margin and speed, especially as filing deadlines tighten and documentation expectations rise.
Competitive Landscape and Leading Strategies
The competitive field blends global reinsurers with technology and service providers, each pursuing distinct positions along the value chain. Incumbent carriers continue to anchor the market with broad risk appetite, diversified portfolios, and established distribution relationships. Their strategic emphasis typically centers on disciplined underwriting, integrated digital client tools, and robust risk-transfer and administration capabilities across life, non-life, and specialty lines. Many have built or acquired proprietary platforms and client portals to reduce friction in the placement and servicing of reinsurance contracts, reinforcing the perception of reliability and continuity that matters in long-tail and capital-intensive transactions.
Technology and software providers are carving a parallel track focused on the operational backbone of reinsurance. SaaS reinsurance administration platforms deliver modular automation for contract initiation, claims recovery, retrocession, and full lifecycle management for both traditional and non-proportional treaties. Other providers offer cloud or on-premise insurance suites that cover premiums, loss reserves, commission calculation, claims processing, and regulatory reporting for ceded and assumed contracts. These platforms increasingly target the pain points identified earlier—manual reconciliation, fragmented reporting, and audit readiness—while enabling interoperability with core policy and financial systems. The value proposition is not solely cost reduction; it is the creation of data continuity that supports solvency and asset adequacy documentation, accelerates settlements, and gives executives a clearer view of ceded exposures and recoverables.
The market is evolving through a combination of consolidation, specialization, and new entry. Scale incumbents compete on breadth and capital strength, while specialists compete on depth in particular lines or geographies. Newer entrants and platform operators compete on speed, configurability, and the ability to plug into existing ecosystems with limited disruption. Strategic differentiation is increasingly defined by three factors: the completeness of the reinsurance administration lifecycle covered, the strength of regulatory and actuarial documentation support, and the ability to operate across jurisdictions with consistent governance. As a result, partnerships between carriers, platforms, and institutional players are becoming more common, especially where an anchor in a well-regulated financial hub can streamline cross-border capacity and operations.
PW Consulting
For decision-makers evaluating partners and vendors, the practical question is not whether a provider offers a feature list, but whether its architecture reduces the cost of compliance, improves data lineage, and supports the lines and structures that matter to the organization. Providers that combine lifecycle automation with actuarial and claims support, or that can evidence alignment with asset adequacy and solvency expectations, are better positioned to capture share in a market where documentation and control are increasingly part of the commercial conversation.
Forward Outlook: Trends and Opportunities
Automation Becomes the Baseline, Not the Differentiator
Over the next three to five years, cloud-native reinsurance administration and integrated automation will move from competitive advantage to operational baseline. Organizations that standardize cessions, recoverables, commission flows, and claims recovery within connected workflows will reduce cycle times and improve the reliability of reporting used in both internal decision-making and external reviews. The commercial opportunity lies in extending these workflows to cover specialty and non-proportional structures, retrocession, and multi-currency settlements, where manual processing has historically introduced the most friction and error. Companies that achieve this baseline earlier will free managerial attention for pricing strategy, asset-liability optimization, and client service rather than administrative remediation.
Regulatory Fluency as a Commercial Capability
Regulatory and actuarial guideline evolution will continue to influence transaction structuring and platform design. Asset adequacy documentation, investment matching adjustments, and principles-based classification will require systems that can trace assumptions, evidence testing, and maintain auditability across ceded and retained portfolios. Firms that build or adopt tooling to operationalize these requirements will gain speed and credibility in filings, while those that rely on manual processes will face rising labor costs and execution risk around deadlines. The upside is not only compliance efficiency but also the ability to structure transactions with greater flexibility in asset deployment and collateral arrangements where supervisory frameworks permit, particularly in life and asset-intensive portfolios.
Market Structure Continues to Fragment in Capability, Consolidate in Ecosystems
While revenue concentration remains moderate, capability concentration will likely increase among providers that can span administration, analytics, and regulatory support within a coherent stack. Expect continued partnership activity between incumbents, platform operators, and institutional participants, especially where a regulated hub and aligned governance can reduce cross-border friction. At the same time, specialization will persist in lines with distinct underwriting, reserving, or asset dynamics, creating room for focused carriers and boutique platforms. The strategic implication is that the most resilient participants will be those that can combine clear risk appetite with interoperable technology, disciplined documentation, and the ability to scale operations without proportional increases in manual effort.
Risks and Uncertainties to Monitor
The outlook is constructive, but not without caveats. Catastrophe volatility and the accumulation of secondary perils can re-rate pricing and capacity quickly, pressuring returns and testing reserving discipline. Regulatory interpretation can shift as supervisors deepen scrutiny of AI-assisted models and third-party cloud dependencies, potentially increasing governance costs or constraining certain automation paths until standards settle. Talent constraints in actuarial and specialized claims roles may continue to elevate operational expenses where workflows are not sufficiently automated or standardized. Finally, macro and capital market dynamics can affect asset deployment strategies and the attractiveness of collateral-free structures, influencing transaction economics in life and non-life lines alike. Participants should therefore pair growth ambitions with scenario planning, data quality, and flexible operating models.
Strategic Implications for Decision-Makers
For Executives and Strategy Teams
Prioritize integration over point fixes. Decision velocity and margin protection increasingly depend on connected workflows that span policy, finance, actuarial, and reinsurance administration. Establish clear ownership of data lineage and documentation so that asset adequacy testing, solvency reporting, and recoverable tracking can be produced consistently and on time. Evaluate partners and platforms against their ability to cover the full lifecycle, support the lines and structures most relevant to the portfolio, and demonstrate governance aligned with supervisory expectations. Where feasible, sequence adoption to first reduce the highest-friction manual processes, then extend automation to specialty and non-proportional structures and multi-currency operations.
Worldwide Real Estate Insurance Market
For Investors and Capital Allocators
Assess exposure and resilience across the value chain rather than relying on headline market size alone. Differentiate between carriers with diversified, disciplined underwriting and those more exposed to concentrated catastrophe or cyber accumulation. In technology and service providers, focus on evidence of workflow completeness, customer retention, and the ability to reduce compliance and reconciliation costs, since these qualities translate into durable operating leverage as regulatory and documentation demands rise. Consider jurisdictional and partnership dynamics that can lower cross-border friction, while monitoring the regulatory trajectory for AI and cloud governance, which may affect cost structures and deployment options in the medium term.
For Procurement and Vendor Selection Teams
FrameRFP criteria around outcomes rather than feature counts. Define requirements for automated cessions, recoverable tracking, commission handling, claims support, and audit-ready reporting, and verify how each candidate maps to existing policy and financial systems. Require demonstrations of data lineage, documentation support for asset adequacy and solvency contexts, and clear migration or interoperability plans to avoid rip-and-replace risk. Weight vendor stability, roadmap coherence, and support for multi-jurisdiction operations where relevant, and build pilot metrics around cycle-time reduction, error reduction, and documentation completeness so that adoption decisions are anchored in measurable operational improvement.
The reinsurance market is scaling within a framework of rising expectations for speed, transparency, and regulatory discipline. Those that treat technology, data, and compliance fluency as core commercial capabilities will be better positioned to absorb complexity, protect margin, and access capacity where it is most valuable. For readers seeking a deeper segmentation of regional and line-level dynamics, detailed revenue paths across the forecast horizon, and tailored recommendations calibrated to specific portfolio structures, the full research report provides the granular data and scenario analysis needed to convert these strategic signals into concrete plans.
Insurance Market
For detailed analysis of this topic, please visit the official page: Reinsurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Urea Formaldehyde Resin Market: Why the 2% CAGR Trajectory Signals Real Growth Drivers
By pmarketresearch, 2026-09-21
Urea Formaldehyde Resin Market: Navigating the Crossroads of Compliance, Cost, and Innovation
The global urea formaldehyde resin market stands at a strategic inflection point, where established demand patterns intersect with tightening regulatory frameworks and evolving supply chain dynamics. Valued at approximately $11.71 billion in 2020, the market expanded steadily through 2023, reaching $12.47 billion, before experiencing a modest contraction to $12.93 billion in 2025. Looking ahead, the trajectory projects growth to $14.85 billion by 2032, reflecting a compound annual growth rate of roughly 2.0% over the forecast horizon. This measured expansion masks significant underlying volatility, as the market navigates structural shifts in end-use demand, raw material pricing pressures, and regulatory mandates that are fundamentally reshaping product specifications and competitive positioning. For executives and investors operating in downstream manufacturing, chemical distribution, or advanced materials, understanding these dynamics is no longer optional; it is a prerequisite for capital allocation, product roadmap planning, and supplier diversification strategies.
Market Landscape and Structural Headwinds
A Moderating Growth Curve with Regional Asymmetry
The market’s historical progression from $11.79 billion in 2021 to $13.08 billion in 2024 illustrates a period of steady adoption, primarily fueled by construction activity, furniture manufacturing, and panelboard production across key industrial corridors. However, the slight pullback in 2025 to $12.93 billion signals a transitional phase rather than a cyclical downturn. Demand composition remains heavily anchored in traditional adhesive applications, with powder and liquid formulations splitting the revenue base in ways that reflect both application engineering preferences and logistical constraints. Liquid grades continue to dominate environments requiring on-site mixing flexibility or continuous processing lines, while powder variants maintain relevance in settings where shelf stability, transportation efficiency, and controlled inventory management outweigh handling complexity.
PW Consulting Chemical & Energy Research Center
Three Critical Challenges Shaping the Next Cycle
First, regulatory tightening around volatile organic compound emissions has moved from a compliance checkbox to a product architecture constraint. Standards such as CARB Phase-III and EPA TSCA Title VI now require composite wood products to limit formaldehyde emissions to 0.05 ppm, effectively mandating reformulation across legacy adhesive portfolios. The operational implication extends beyond chemistry; it touches manufacturing line validation, certification timelines, and customer acceptance cycles, creating a compliance burden that disproportionately affects mid-tier producers without dedicated R&D or regulatory affairs capacity.
Second, raw material cost volatility has introduced margin compression risks that are difficult to hedge through conventional procurement strategies. Formaldehyde pricing in Europe reached 370 euros per ton in early 2025, marking a historical high, while urea formaldehyde resin prices in the United States climbed to 908 USD per metric ton in September 2025, closely tracking feedstock urea movements. These cost pressures are not isolated to a single region or feedstock; they reflect broader energy, logistics, and agricultural input dynamics that ripple through the value chain and challenge the economics of both conventional and low-emission formulations.
Third, the cost differential between conventional and low-emission resin variants introduces a strategic dilemma for downstream buyers. Industry analysis indicates that meeting EU and global low-emission requirements can add 10–15% to production costs for standard UF resins compared with compliant low-emission grades. This premium is not uniformly absorbed across end markets; cost-sensitive applications face pricing resistance, while premium wood bonding and construction panel segments increasingly treat low-emission compliance as a baseline entry requirement rather than a differentiated feature.
Paraformaldehyde Market
Key Drivers Reshaping the Market Trajectory
Regulatory Architecture as a Catalyst for Product Innovation
Regulatory pressure is no longer a static compliance backdrop; it is actively steering formulation pathways and competitive differentiation. The requirement for a 40% reduction in VOC emissions by 2026 under CARB Phase-III has accelerated reformulation programs across the adhesive and panelboard ecosystem. This regulatory trajectory is pushing producers to invest in low-emission UF grades that meet E0, CARB, and LEF/ULEF standards without sacrificing bond strength, cure speed, or process compatibility. The practical outcome is a market where regulatory conformity becomes a gatekeeper for market access, particularly in North American and European composite wood segments, while simultaneously creating a technical moat for suppliers that can deliver compliant formulations at scale.
Green Chemistry and Low-Emission Formulation as Competitive Levers
The push toward reduced formaldehyde emissions has coincided with broader sustainability mandates across the chemical and manufacturing sectors, creating a convergence of compliance and corporate ESG objectives. Leading producers are responding by developing resin lines that lower formaldehyde output while maintaining performance benchmarks for plywood, particleboard, fibreboard, and impregnation applications. Some offerings now emphasize emission reductions of up to 90% relative to conventional benchmarks, positioning low-emission grades as enablers for downstream manufacturers seeking to satisfy both regulatory standards and customer-facing sustainability claims. This trend is not merely a technical adjustment; it is reshaping procurement criteria, as panel producers and wood product manufacturers increasingly evaluate resin suppliers on emission profiles, certification support, and formulation flexibility alongside price and delivery reliability.
Demand-Side Shifts in Construction, Furniture, and Panel Manufacturing
Downstream demand patterns are evolving in response to housing market dynamics, interior fit-out cycles, and the expansion of engineered wood solutions in both developed and emerging economies. Wood adhesives remain the dominant application driver, reflecting the continued reliance on UF resins in panelboard production and furniture assembly. At the same time, demand for molding compounds, surface coatings, and textile finishing applications introduces segments with distinct performance requirements and growth profiles. The practical implication for resin producers is that volume growth is increasingly tied to application-specific engineering rather than broad commodity displacement. Customers are looking for formulations that balance cure compatibility, moisture resistance, emission compliance, and total cost of ownership, which elevates the importance of technical service, application testing, and co-development arrangements.
Supply Chain Reconfiguration and Cost Structure Dynamics
Feedstock pricing, energy costs, and logistics constraints are collectively reshaping the cost structure of UF resin production. The convergence of elevated formaldehyde prices in Europe and urea-linked resin pricing movements in the United States underscores the vulnerability of input cost pass-through strategies, particularly in markets where downstream price sensitivity limits aggressive adjustments. In response, some producers are exploring formulation optimization, regional sourcing adjustments, and inventory positioning strategies to mitigate exposure. For downstream manufacturers, this environment heightens the importance of supplier diversification, contractual flexibility, and scenario planning around input cost trajectories. It also reinforces the strategic value of long-term supply agreements that incorporate transparency on feedstock indices and formulation change timelines.
Urea Formaldehyde Concentrate (UFC) Market
Competitive Landscape and Strategic Positioning
Fragmented Leadership with Clear Differentiation Paths
The market exhibits a moderate concentration profile, with a handful of large players commanding a significant share of revenue while a broader base of specialty and regional suppliers competes on formulation, service, and application expertise. This structure supports both scale-driven efficiency and differentiation-driven premium positioning, depending on the segment and geography. Leading companies are pursuing distinct strategic paths that reflect their product portfolios, geographic footprints, and sustainability commitments.
Ercros has focused on low-emission UF resin offerings designed to meet stringent formaldehyde standards across plywood, particleboard, fibreboard, and impregnation applications. Its resin range emphasizes compatibility with LEF, ULEF, CARB, and E0 requirements, positioning the company as a solution provider for downstream manufacturers navigating emission compliance without sacrificing processing performance. Prefere Resins has pursued a sustainability-forward strategy, integrating green chemistry principles into its amino resin portfolio for wood adhesives, insulation, and construction panels. The company’s emphasis on CO2-neutral and bio-based resin innovations, reinforced by recent sustainability certifications and reporting, signals a strategic alignment between regulatory compliance and corporate ESG positioning.
Hexion Inc. continues to leverage established methylated UF grades and resin platforms tailored for wood panel adhesives and particleboard production, emphasizing performance consistency and application familiarity in mature markets. BASF SE maintains a broad specialty chemicals footprint, with urea formaldehyde resin grades positioned for wood bonding and adjacent applications, benefiting from integrated supply chain capabilities and cross-market formulation expertise. Dynea Oy and Advachem contribute through specialized resin technology and niche chemical portfolios, respectively, serving panel adhesives and wood product manufacturing with focused application support. Kronospan Limited’s in-house UF resin production for particleboard, MDF, and plywood illustrates a vertical integration model that prioritizes supply control and formulation alignment with internal panel specifications. Metadynea International GmbH complements this landscape with targeted UF resin offerings for wood panel and adhesive applications, reinforcing the diversity of strategic approaches across the competitive field.
Strategic Takeaways from Recent Industry Moves
Recent developments underscore how sustainability credentials and transparency are becoming embedded in competitive positioning. Prefere Resins’ achievement of an EcoVadis Gold rating for ESG performance, alongside the publication of its first Group Sustainability Report covering 2023–2024, reflects a broader trend in which ESG performance is increasingly treated as a procurement consideration rather than a peripheral corporate initiative. The company’s earlier emphasis on Mission Zero 2050 CO2-neutral bio-based resin innovations further illustrates how long-term decarbonization targets are being translated into product strategy. For buyers and investors, these moves signal that supplier selection is increasingly influenced by verifiable sustainability performance, formulation roadmaps, and the ability to support downstream compliance narratives.
Market Evolution: Integration, Specialization, and New Entrant Dynamics
The competitive landscape is evolving along two complementary paths. On one hand, scale-oriented players continue to pursue integration and portfolio breadth to capture efficiency advantages, support multi-application supply, and reinforce regional distribution reach. On the other hand, specialization is intensifying around low-emission formulations, application-specific engineering, and sustainability-linked product attributes. This dual dynamic creates opportunities for incumbents to defend share through performance and compliance leadership, while also opening space for new entrants or expanding specialists that can address underserved application niches or regional compliance requirements. The likely outcome over the next several years is a market where broad-scale suppliers coexist with highly differentiated formulation specialists, and where downstream buyers increasingly manage a dual-sourcing strategy that balances cost, compliance, and technical support.
Forward Outlook: Three Trends Shaping the 2026–2032 Window
Low-Emission Compliance as a Baseline, Not a Premium
As regulatory mandates mature and enforcement intensifies, low-emission UF grades are likely to transition from differentiated offerings to market-entry requirements in key regions. This shift will compress the commercial advantage of early compliance while simultaneously raising the cost of late adaptation. Manufacturers that have already validated low-emission formulations, secured certification pathways, and aligned production lines with compliant grades will be better positioned to manage transition risk. Conversely, suppliers and downstream buyers that delay reformulation or certification readiness may face margin erosion, supply disruption, or exclusion from regulated procurement channels.
Formulation Engineering and Application-Specific Value Creation
Volume growth is expected to increasingly depend on application-specific value creation rather than broad-based resin displacement. Wood adhesives will remain the core demand anchor, but opportunities in molding compounds, surface coatings, and textile finishing will require tailored performance profiles, processing compatibility, and technical service. This trend favors suppliers that can combine formulation flexibility with application engineering, testing support, and regional responsiveness. For downstream manufacturers, it creates an incentive to deepen technical collaboration with resin partners, particularly where product performance, emission profile, and total cost of ownership must be optimized simultaneously.
Cost Volatility and Supply Chain Resilience as Strategic Priorities
Input cost volatility, particularly around formaldehyde and urea-linked feedstocks, is likely to remain a defining feature of the market environment. While long-term contracts, index-linked pricing, and regional sourcing adjustments can mitigate some exposure, the broader reality is that cost resilience will become a strategic priority for both producers and buyers. This includes evaluating supplier diversity, inventory positioning, formulation flexibility, and scenario planning around feedstock price trajectories. For investors, this environment rewards companies that demonstrate disciplined cost management, transparent input exposure, and the ability to adapt formulations without compromising compliance or performance.
Strategic Actions for Decision-Makers
For Manufacturers and Panel Producers
- Validate low-emission resin compatibility across existing and planned production lines before regulatory deadlines tighten further, prioritizing formulations that meet CARB, EPA TSCA, and E0/EU expectations without disrupting cure profiles or bond performance.
- Diversify resin sourcing to balance cost, compliance, and technical support, while establishing clear criteria for supplier evaluation that include emission data, certification support, formulation adaptability, and supply continuity.
- Invest in application testing and co-development with resin suppliers where performance or emission targets require custom formulation, reducing the risk of line stoppages, rework, or certification delays.
For Investors and Strategic Capital Allocators
- Prioritize companies that demonstrate verifiable progress on low-emission formulation roadmaps, ESG transparency, and cost discipline, as these attributes are increasingly correlated with market access and procurement preference in regulated segments.
- Monitor feedstock exposure and pricing pass-through capabilities, recognizing that margin resilience will depend on formulation optimization, regional sourcing flexibility, and contract structures that align input costs with downstream pricing reality.
- Evaluate consolidation and specialization dynamics as indicators of where value is being created, particularly in segments where low-emission compliance, application engineering, and sustainability credentials are reshaping buyer selection criteria.
For Procurement and Supply Chain Leaders
- Integrate emission compliance, certification support, and sustainability reporting into supplier scorecards alongside price, lead time, and quality metrics, ensuring that procurement decisions reflect both regulatory readiness and corporate ESG objectives.
- Establish scenario planning for raw material cost movements, including index-linked contracting, alternative supplier qualification, and inventory strategies that reduce exposure to sudden feedstock price spikes.
- Engage early with resin suppliers on formulation change timelines and certification requirements, aligning procurement calendars with technical validation cycles to avoid disruption during regulatory transitions.
Closing Perspective
The urea formaldehyde resin market is not defined by a single growth driver or a uniform competitive narrative. It is a market in which regulatory compliance, feedstock economics, application-specific performance, and sustainability positioning intersect to shape buyer behavior and supplier strategy. The modest headline growth projection conceals a more nuanced reality: value creation is shifting toward compliance readiness, formulation flexibility, and supply chain resilience, while cost volatility and certification complexity reward companies that act early and coordinate across technical, commercial, and procurement functions. For executives, investors, and supply chain leaders, the practical imperative is to treat resin selection and supplier relationships as strategic variables rather than transactional inputs, and to align product roadmaps, sourcing decisions, and investment priorities with the regulatory and cost realities that will define the next cycle.
For detailed segmentation data, regional demand profiles, application-level revenue splits, and tailored scenario analysis, the full research report provides the granular data and customized recommendations needed to translate these market dynamics into concrete planning parameters.
For detailed analysis of this topic, please visit the official page: Urea Formaldehyde Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electroretinography Market: Why 8% CAGR and Clinical Diagnostics Shift Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Electroretinography Market
The electroretinography (ERG) market has entered a phase of structural expansion, driven by the convergence of regulatory alignment, technological miniaturization, and the clinical need for objective functional assessment of retinal health. Spanning a base year of 2025 with historical tracking from 2020 through 2025 and a forecast period extending to 2032, the market demonstrates a consistent upward trajectory. Revenue grew from 300.0 million in 2020 to an estimated 414.0 million in 2025, and is projected to reach 711.32 million by 2032, reflecting a compound annual growth rate of 8.0 percent. This growth is not merely incremental; it signals a market transitioning from a niche diagnostic tool toward a more integrated component of routine ophthalmic and neurological evaluation.
The revenue distribution across testing modalities reveals a clear hierarchy. Full-field flash ERG remains the dominant segment, accounting for the largest share of market value, while multifocal ERG holds a substantial secondary position, reflecting its growing utility in localized retinal function mapping. Pattern ERG and other specialized variants occupy smaller but strategically important niches, often tied to specific clinical indications or research applications. On the application side, clinical diagnostics represent the overwhelming majority of demand, with research activities comprising a meaningful but smaller portion. Geographically, North America leads in market size, followed by Europe, with the Asia Pacific region representing a smaller but rapidly evolving base. Latin America and the Middle East and Africa collectively account for a modest share, though emerging healthcare infrastructure investment suggests latent demand that may unlock as reimbursement pathways mature.
Market concentration remains relatively fragmented. The top three participants collectively hold approximately 24.6 percent of revenue, while the top five reach 26.2 percent. This dispersion indicates that no single entity controls the market, leaving room for strategic consolidation, differentiated technology plays, and regional expansion by mid-tier manufacturers. The absence of dominant concentration also suggests that competitive advantage will increasingly derive from clinical validation, reimbursement alignment, and workflow integration rather than sheer scale alone.
1. Market Status and Core Challenges
The electroretinography market operates at the intersection of diagnostic precision and practical clinical adoption. Despite clear growth signals, several structural challenges shape how manufacturers, providers, and investors approach the space.
PW Consulting
1.1 Reimbursement Ambiguity and Coding Fragmentation
One of the most persistent friction points is the uneven reimbursement landscape for ERG testing. While certain Current Procedural Terminology codes, such as CPT 92273 for full-field ERG with interpretation and report, are recognized under Medicare with defined reimbursement levels and supported by major Medicare Administrative Contractors for medically necessary indications, coverage is not universal across payers. Pattern ERG codes, for example, are frequently classified as investigational by commercial insurers, creating a reimbursement gap that limits routine adoption in some clinical settings. This fragmentation forces manufacturers and provider networks to navigate a patchwork of coverage policies, which can slow procurement cycles and complicate revenue forecasting for diagnostic service providers.
1.2 Standardization Gaps and Protocol Variability
Although the International Society for Clinical Electrophysiology of Vision has published updated standards for full-field clinical electroretinography to promote reproducible recordings using dark-adapted and light-adapted stimuli, real-world implementation varies. Differences in stimulus calibration, electrode placement, patient preparation, and interpretation workflows can affect result consistency across sites. For clinicians, this variability can undermine confidence in ERG as a longitudinal monitoring tool, particularly when integrating findings with structural imaging modalities. For manufacturers, it creates both a challenge and an opportunity: devices that embed standardized protocols, built-in quality checks, and guided workflows can reduce inter-site variability and improve adoption.
1.3 Workflow Integration and Clinical Practicality
Traditional ERG testing has often been perceived as technically demanding, time-consuming, and dependent on dilated pupils or specialized setups. In high-volume clinical environments, any test that disrupts patient flow or requires extensive technician training faces adoption friction. The market is therefore at a turning point where portability, non-mydriatic operation, and streamlined interpretation are becoming decisive factors. Devices that reduce preparation time, allow testing in broader patient populations including newborns and non-cooperative patients, and integrate with existing electronic health record workflows are better positioned to convert clinical interest into sustained purchasing decisions.
2. Key Demand Drivers
The growth trajectory of the electroretinography market is not accidental; it reflects a set of reinforcing drivers that are reshaping how retinal function is assessed, reimbursed, and commercialized.
2.1 Technological Innovation and Portable Non-Mydriatic Systems
The most consequential technological shift is the emergence of handheld, portable ERG platforms that enable functional retinal assessment without dilation and with reduced setup complexity. These systems expand the feasible testing environment beyond specialized electrophysiology labs to outpatient clinics, primary care-linked ophthalmology settings, and even screening programs. By lowering the practical barriers to testing, portable devices increase the addressable patient population and create new use cases for routine diabetic retinopathy monitoring, glaucoma suspect evaluation, and inherited retinal disease screening. The clinical value proposition is reinforced when portable systems demonstrate performance comparable or superior to conventional imaging in predicting disease progression, particularly in moderate to severe non-proliferative diabetic retinopathy, where functional assessment can complement structural imaging and help identify patients at risk of vision-threatening complications.
2.2 Regulatory Clarity and Guideline Alignment
Regulatory and guideline developments are steadily reducing uncertainty around ERG’s clinical role. The inclusion of full-field and multifocal ERG in updated ophthalmologic preferred practice pattern guidelines for diabetic retinopathy management represents a meaningful endorsement, signaling that functional testing has a place in routine disease management rather than being confined to specialized referrals. At the same time, FDA clearance pathways and international certification frameworks, including ISO 13485 and MDSAP compliance, provide a structured route for manufacturers to demonstrate safety and performance. The alignment between standards bodies, regulatory agencies, and clinical guidelines creates a more predictable environment for product development and market entry, particularly for devices that are designed to meet ISCEV-aligned protocols from the outset.
Automated Ophthalmic Perimeters Market
2.3 Demand-Side Shifts Toward Objective Functional Biomarkers
Clinicians and health systems are increasingly seeking objective, quantifiable functional biomarkers that can track disease progression, guide treatment decisions, and support payer discussions. Structural imaging alone does not always capture functional decline, especially in early or moderate disease stages where anatomical changes may be subtle. ERG provides a direct measure of retinal electrical response, offering a complementary data point that can strengthen diagnostic confidence and support longitudinal monitoring. This demand-side shift is particularly relevant in diabetic retinopathy management, where the ability to identify patients at higher risk of progression can influence follow-up intervals, referral patterns, and intervention timing. As value-based care models emphasize outcomes and risk stratification, functional testing that contributes to more precise patient management becomes more attractive to providers and payers alike.
2.4 Supply Chain Consolidation and Portfolio Integration
Recent corporate activity illustrates a broader supply-side trend: established medtech and electronic instruments companies are expanding their ophthalmic diagnostic portfolios through acquisition and integration. By absorbing specialized ERG manufacturers, larger platforms can combine regulatory expertise, distribution networks, and cross-selling capabilities with proven clinical technologies. This consolidation can accelerate market reach, improve service and support infrastructure, and create bundled solutions that pair ERG with other diagnostic modalities. For smaller manufacturers, the environment presents both pressure and opportunity: pressure from potential acquisition or competition with better-resourced rivals, but also opportunity to differentiate through proprietary stimulation methods, advanced protocol libraries, or region-specific reimbursement strategies.
3. Competitive Landscape and Leading Strategies
The competitive field in electroretinography is characterized by a mix of established electrophysiology specialists, vision monitoring companies, and broader diagnostic portfolios that have expanded into retinal functional testing. Rather than competing solely on hardware specifications, leading players are increasingly differentiating through clinical evidence, workflow design, regulatory positioning, and ecosystem integration.
3.1 Strategic Positioning of Leading Participants
Several companies illustrate the range of viable strategic postures within the market. One U.S.-based manufacturer has concentrated on portable, handheld full-field ERG and visual evoked potential systems, emphasizing FDA-cleared, non-mydriatic operation suitable for clinical functional assessment. This positioning targets the practical adoption barrier directly, making the technology accessible in settings where conventional ERG infrastructure is impractical. Clinical evidence linking the device’s scoring approach to prediction of progression in moderate to severe non-proliferative diabetic retinopathy further strengthens the commercial narrative by tying the product to a high-impact clinical use case.
Another U.S. specialist focuses on full-field and multifocal ERG systems with advanced protocols for both clinical and research electrophysiology. This company’s strategy leans toward technical depth, protocol flexibility, and support for rigorous electrophysiological evaluation, appealing to centers that require detailed functional mapping and research-grade capability. In Europe, a French manufacturer has built its identity around a vision monitoring platform that supports multiple ERG modalities and visual evoked potential testing, incorporating proprietary constant-luminance stimulation methods. This approach highlights the importance of stimulation precision and modality breadth as differentiators for customers who need a single platform capable of spanning multiple testing requirements.
A German producer emphasizes electrophysiological diagnostic systems for clinical use across full-field, multifocal, and pattern ERG as well as visual evoked potential testing, positioning around clinical reliability and standards alignment. A U.S. vendor offering multifocal and flash ERG systems for clinical settings continues to serve a segment that values established platforms and specialized electroretinography equipment. An Italian manufacturer provides clinical ERG and electrophysiological diagnostic equipment with an emphasis on compliance with international standards, which can be an important factor in markets where regulatory and procurement processes are closely tied to certification and conformity. A Russian manufacturer has extended its reach into full-field and extended ERG testing across age groups, including newborns, illustrating how demographic coverage and pediatric capability can open niche but valuable application spaces.
Worldwide 12 Channel Electrocardiograph Market
The acquisition of the portable ERG platform by a larger electronic instruments company in early 2026 exemplifies the portfolio integration strategy. By embedding the handheld device within a broader ophthalmic diagnostics portfolio, the acquiring company gains a differentiated functional testing offering, an established regulatory and quality framework, and a channel to expand distribution. This move also signals to the market that portable non-mydriatic ERG is viewed as a strategic asset rather than a peripheral niche product.
3.2 Market Evolution Trends
The competitive landscape is evolving along several interrelated dimensions. Consolidation is likely to continue as larger platforms seek to strengthen their diagnostic portfolios and smaller specialists evaluate whether independence or partnership better serves their growth ambitions. At the same time, differentiation is shifting toward clinical validation, reimbursement readiness, and workflow integration. Devices that can demonstrate alignment with recognized standards, support Medicare and commercial coverage pathways, and fit smoothly into clinic operations are gaining an advantage over products that rely primarily on technical specifications.
Regional dynamics also shape competition. In North America, reimbursement alignment and guideline inclusion are powerful adoption catalysts, favoring products with strong regulatory documentation and clinical evidence. In Europe, standards conformity, multi-modality platforms, and regional service networks influence purchasing decisions. In Asia Pacific and other emerging markets, adoption may be more sensitive to price, training support, and the ability to operate in varied clinical settings, suggesting that a one-size-fits-all go-to-market approach will underperform. New entrants that can address specific gaps, such as pediatric testing, portable screening, or integrated interpretation tools, may find opportunities even in a market with established incumbents.
4. Future Trend Predictions
Looking ahead across the next three to five years, several trends are likely to define the market’s direction and shape the commercial opportunities available to manufacturers, providers, and investors.
4.1 From Specialized Testing to Routine Functional Assessment
As portable, non-mydriatic systems mature and clinical guidelines continue to recognize the role of full-field and multifocal ERG in conditions such as diabetic retinopathy, functional retinal testing is likely to move from specialized referral settings toward more routine use. This shift creates opportunities for manufacturers to design products that prioritize speed, ease of use, and interpretation support, and for providers to build service lines around objective functional monitoring. The commercial implication is clear: devices that can be deployed in broader clinical environments and supported by clear reimbursement logic will capture more consistent demand than those tied to niche specialist workflows.
4.2 Evidence-Led Adoption and Predictive Clinical Value
The next phase of adoption will be increasingly driven by clinical evidence that ties ERG findings to meaningful outcomes, particularly risk stratification and progression prediction. Studies demonstrating that functional scoring can outperform or complement structural imaging in forecasting vision-threatening complications provide a template for how evidence can accelerate uptake. As more data accumulate, sales cycles may shorten in settings where ERG is framed not merely as an alternative test but as a decision-support tool that influences management. Manufacturers and service providers that invest in robust clinical validation and real-world evidence generation will be better positioned to justify formulary inclusion, procurement priority, and payer coverage.
4.3 Ecosystem Integration and Multi-Modal Workflows
ERG is unlikely to replace structural imaging; instead, it will increasingly be integrated into multi-modal diagnostic workflows. Platforms that combine functional and structural data, support standardized reporting, and connect with electronic health records will offer greater value to busy clinical teams. This trend also encourages portfolio-level competition, where companies aim to provide a coherent diagnostic suite rather than isolated instruments. For investors, this suggests that value may accrue not only to best-in-class standalone devices but also to platforms that can embed ERG within broader ophthalmic or neurological diagnostic ecosystems.
4.4 Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Reimbursement policy remains fluid, and adverse changes to coverage for pattern ERG or shifts in medical necessity documentation requirements could slow adoption in certain segments. Standardization, while improving, is not yet universally implemented; sites that lack trained personnel or consistent protocols may underutilize available technology. Competition from alternative functional or structural assessments, including advanced imaging and artificial intelligence-assisted diagnostics, could compress ERG’s role if those modalities prove more convenient or better reimbursed. Finally, macroeconomic pressure on healthcare capital spending may extend procurement cycles, particularly in smaller practices and emerging markets, making clear return-on-investment arguments more important than ever.
5. Strategic Recommendations for Decision-Makers
Companies operating in or entering the electroretinography market face a landscape where clinical utility, regulatory alignment, and workflow practicality determine commercial success more than specification comparisons alone. The following recommendations translate the current dynamics into actionable priorities for different stakeholder groups.
5.1 For Manufacturers
Develop products with reimbursement and guideline alignment built into the design and commercialization plan, not treated as an afterthought. Where possible, support ISCEV-aligned protocols, document performance against recognized standards, and generate clinical evidence that connects functional testing to decision-making in high-prevalence conditions such as diabetic retinopathy. Prioritize portability, non-mydriatic operation, and streamlined interpretation to broaden the addressable setting beyond specialized labs. Consider whether independent positioning or portfolio integration best fits your capabilities, and invest in service, training, and workflow compatibility to reduce adoption friction.
5.2 For Investors
Evaluate opportunities not only on technology novelty but on the strength of clinical evidence, reimbursement readiness, and the ability to integrate into routine care pathways. Companies that can demonstrate a clear link between functional assessment and risk stratification, supported by credible validation and standards alignment, are better positioned for durable adoption. Monitor consolidation trends, as acquired platforms may gain distribution and service advantages, while independent specialists may offer niche leadership in areas such as pediatric testing, advanced protocols, or region-specific reimbursement strategies. Scrutinize portfolio fit and cross-selling potential when assessing larger platforms that are expanding into ophthalmic diagnostics.
5.3 For Procurement and Clinical Leaders
Assess ERG solutions based on how well they fit into existing workflows, the availability of standardized protocols, and the practical training burden for staff. Favor systems that support consistent, reproducible recordings and provide clear interpretation support, particularly if the goal is to use ERG for longitudinal monitoring or risk stratification. Evaluate total cost of ownership in the context of reimbursement realities, including whether the intended use cases align with covered indications and documentation requirements. Where possible, seek evidence that the selected solution contributes to measurable improvements in patient management, rather than treating ERG as an isolated diagnostic add-on.
The electroretinography market is advancing along a path shaped by portable technology, guideline recognition, and a growing appetite for objective functional biomarkers. The companies and clinical programs that succeed will be those that treat ERG as part of a broader diagnostic strategy, supported by evidence, standards, and practical workflow design. For decision-makers who need granular segmentation data, competitive benchmarking, reimbursement mapping, and customized scenario analysis, a comprehensive market research report can provide the level of detail required to translate these trends into concrete investment, product, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Electroretinography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com