

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Foaming Creamer Market: Why $189.5M in Demand Changes Everything

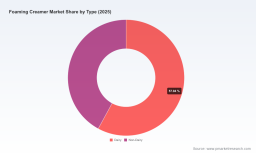
Foaming Creamer Market: Strategic Trends and Commercial Opportunities Beyond Steady Growth
Market Snapshot and Structural Challenges
The global foaming creamer market has demonstrated consistent, albeit moderate, expansion over the past half-decade, moving from approximately 150.0 million USD in 2020 to an estimated 189.5 million USD in 2025. This trajectory reflects a compound annual growth rate of 3.5 percent, with projections pointing toward 240.25 million USD by 2032. While the growth pace is not explosive, it signals a mature yet resilient category where incremental innovation and regional penetration matter more than headline expansion. The market’s stability is anchored in its dual role: serving as a functional ingredient for beverage formulation and as a value-enhancing component in foodservice and retail channels.
Beneath the steady valuation curve lies a set of structural inflection points that demand strategic attention. First, raw material dependency remains a persistent volatility driver. Foaming creamer powders require precise formulation parameters, typically relying on 18–24 percent milk solids and 19–23 percent fat content sourced from dairy or palm and coconut oil derivatives. Fluctuations in agricultural commodity pricing, coupled with shifting sustainability expectations around palm oil and dairy sourcing, create margin compression risks for manufacturers that lack diversified supply architectures.
Second, regulatory scrutiny is intensifying across major markets, particularly around labeling transparency, additive disclosures, and nutritional claims. In the United States, food safety authorities continue to monitor foaming creamer products for compliance with health and safety criteria, while the European Union maintains stringent oversight of non-dairy ingredients, emphasizing clean-label alignment and plant-based standard adherence. Compliance is no longer a checkbox exercise; it is a competitive differentiator that shapes consumer trust, retail placement, and cross-border trade feasibility.
Non-dairy Creamer Market
Third, production economics remain tightly linked to specialized infrastructure and labor-intensive quality control. Spray-drying processes, which are essential for achieving stable foam characteristics in both hot and cold applications, require dedicated facilities and rigorous formulation oversight. This creates a barrier to entry but also concentrates operational complexity among established players. Companies that cannot manage the intersection of process precision, ingredient sourcing, and cost efficiency will struggle to scale profitably in an increasingly price-aware environment.
Core Drivers Shaping Market Trajectory
Technological evolution in ingredient engineering continues to redefine what foaming creamers can deliver. The shift from generic texture enhancement to controlled foam architecture—where stability, mouthfeel, and layering are engineered for specific brewing systems and instant beverage formats—has opened new formulation pathways. Granulation and spray-drying advancements enable manufacturers to tailor fat-to-solids ratios with greater precision, allowing products to perform consistently across single-serve brewing equipment, ready-to-mix beverage applications, and foodservice preparation. This technical maturation is gradually decoupling product performance from reliance on traditional dairy-only inputs, expanding the design space for non-dairy and hybrid formulations.
Policy and regulatory dynamics are simultaneously acting as both constraint and catalyst. Stringent ingredient standards in developed markets are pushing formulators toward cleaner profiles, fewer synthetic additives, and more transparent sourcing narratives. Rather than treating compliance as a defensive cost, leading companies are integrating regulatory alignment into product architecture early in the development cycle. This proactive stance reduces time-to-market friction, strengthens retailer confidence, and positions brands favorably in regions where labeling and nutritional claim verification are becoming purchasing prerequisites. The regulatory environment is therefore reshaping the competitive baseline: products that meet clean-label expectations without sacrificing functional performance are gaining shelf and menu precedence.
Demand-side behavior is shifting along two reinforcing axes: premiumization and convenience. Consumers and foodservice operators alike are prioritizing beverage experiences that combine visual appeal, consistent foam structure, and familiar flavor profiles with rapid preparation. Instant drink formats, specialty coffee applications, and milk tea categories have normalized the expectation that a creamer should contribute not just richness but also a stable, enduring foam layer. At the same time, retail and foodservice buyers are seeking formulations that simplify inventory management, reduce preparation variability, and support menu standardization across locations. This convergence favors products designed for predictable performance in both hot and cold systems, with application versatility becoming a key purchasing criterion.
Supply chain and cost structure evolution is introducing both pressure and opportunity. Labor-intensive formulation and quality control steps, combined with the need for specialized spray-drying infrastructure, mean that production efficiency is increasingly tied to process automation, batch consistency, and supplier coordination. Companies that invest in tighter quality loops, ingredient traceability, and flexible production scheduling are better positioned to absorb raw material volatility while maintaining consistent output. Conversely, fragmented sourcing strategies and underinvestment in process control can quickly erode margin stability when commodity inputs or logistics costs shift. The net effect is a market where operational discipline is becoming a strategic asset as much as formulation expertise.
Competitive Landscape and Positioning Dynamics
The competitive field is characterized by a mix of specialized regional players and broader ingredient groups, with the top three firms collectively accounting for roughly 45 percent of market revenue and the top five reaching approximately 65 percent. This concentration reflects a market where scale, process capability, and application-specific formulation knowledge confer meaningful advantages, yet it also leaves room for targeted entrants that solve specific performance or compliance gaps.
Chia-Tza-Teng International Co., Ltd. has built its positioning around foaming creamer powders engineered for instant thick foam in coffee and milk tea sachets, leveraging granulation technology to deliver 18–24 percent milk solids and 19–23 percent fat content. Its recent catalog expansion in early 2026 signals continued investment in product visibility and application breadth, reinforcing a strategy centered on formulation consistency and format-specific performance. Royal FrieslandCampina N.V. has differentiated through its Kievit® Vana-Cappa line, which focuses on creating a stable foam layer with lasting texture for instant drinks and single-serve brewing systems. This positioning aligns closely with the convenience and standardization demands of modern foodservice and retail beverage formats, emphasizing reliability across preparation methods. Kerry Group plc, through its Almer division, supplies spray-dried foaming creamer powders for hot and cold beverages, with sourcing flexibility spanning palm or coconut oil bases. Its strategy highlights application adaptability and infrastructure alignment, recognizing that stable foam performance depends as much on drying and formulation control as on ingredient selection. PT Lautan Natural Krimerindo operates with a focused non-dairy orientation, manufacturing foaming creamer specifically designed to deliver coffee froth on top of beverages. Its participation in major trade platforms, including Food Taipei Mega Shows in mid-2026, underscores a regional growth play that targets emerging beverage categories and export-oriented distribution channels.
The landscape is evolving along a dual path of consolidation and segmentation. Larger ingredient groups are leveraging integrated supply chains, regulatory expertise, and cross-application portfolios to defend share and capture adjacent opportunities. At the same time, specialized manufacturers are carving out niches by emphasizing format-specific foam performance, regional taste preferences, and cost-competitive non-dairy alternatives. New entrants tend to succeed not by competing on broad commodity positioning, but by solving a precise formulation, compliance, or distribution challenge that incumbents are not optimized to address. This dynamic suggests that the next phase of competition will be less about overall market size and more about application ownership, ingredient transparency, and supply chain agility.
Worldwide Shaving Foam Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, clean-label and plant-forward formulation will move from differentiation to baseline expectation. As regulatory frameworks tighten and consumer preferences continue to favor transparent ingredient lists, foaming creamers that deliver stable performance with simplified profiles will capture disproportionate attention in retail and foodservice procurement. The commercial opportunity lies in developing formulations that maintain foam integrity and mouthfeel while reducing additive complexity and aligning with regional plant-based standards. Companies that invest early in this transition will be better positioned to secure shelf placement, streamline compliance, and respond to buyer requirements without last-minute reformulation.
PW Consulting
Second, application-specific engineering will become a more decisive competitive lever. Foam stability, temperature tolerance, and texture consistency are increasingly evaluated against specific use cases, from single-serve brewing systems to instant beverage mixes and foodservice milk tea preparation. The opportunity here is to design product architectures that are validated across multiple preparation environments, reducing formulation risk for buyers and enabling broader deployment. Manufacturers that can document performance across hot and cold systems, provide clear usage guidance, and support menu standardization will find stronger purchase justification and higher switching costs for their customers.
Third, supply chain resilience and input diversification will separate scalable operators from marginal players. Given the reliance on dairy solids, palm or coconut oil derivatives, and specialized drying infrastructure, companies that build flexible sourcing strategies, monitor commodity exposure, and invest in process consistency will be more capable of protecting margins during volatility. The associated opportunity is to pair ingredient flexibility with formulation stability, ensuring that changes in raw material inputs do not compromise foam performance or regulatory alignment. Risks remain, particularly where procurement strategies are overly concentrated, where reformulation capacity is limited, or where regional compliance requirements shift faster than product development cycles can accommodate.
Actionable Directions for Decision-Makers
For manufacturers, the priority should be to align formulation strategy with both performance validation and regulatory foresight. Investing in application testing across hot and cold beverage systems, documenting foam stability and texture consistency, and building ingredient architectures that can accommodate sourcing variation without sacrificing clean-label compliance will create durable advantages. Companies should also evaluate where spray-drying capacity, quality control rigor, and batch consistency can be strengthened to reduce operational risk and improve margin predictability.
For investors, the strategic question is less about overall market growth and more about which capabilities will command pricing power and share resilience. Interest should center on players that demonstrate differentiated application engineering, flexible ingredient sourcing, and a credible path to clean-label compliance across key regions. Monitoring how incumbents and niche players respond to regulatory evolution, raw material volatility, and foodservice standardization trends will provide early signals about which business models are most likely to scale profitably.
For procurement and sourcing leaders, the focus should be on reducing formulation and supply risk while securing consistent beverage performance. This means prioritizing suppliers that can provide transparent ingredient profiles, validated foam stability across intended applications, and clear guidance on usage compatibility with existing brewing or mixing systems. Building redundancy into sourcing, evaluating total cost beyond unit price, and requiring documentation that supports labeling and nutritional claim compliance will help protect product quality and reduce downstream disruption.
Closing Perspective
The foaming creamer market is entering a phase where steady valuation growth masks increasingly important shifts in formulation expectations, regulatory alignment, and supply chain discipline. Companies that treat these shifts as strategic design constraints rather than operational nuisances will be better positioned to capture application-specific demand, defend margins, and expand into higher-value beverage categories. For decision-makers seeking deeper segmentation data, regional demand patterns, and tailored recommendations aligned with specific product portfolios or investment criteria, a detailed market report can provide the granular context needed to convert these directional insights into execution plans.
For detailed analysis of this topic, please visit the official page: Foaming Creamer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com