

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electric Enclosure Market: Why 7.5% CAGR and Strategic Shifts Reshape the Industry by 2032

Navigating the Electric Enclosure Market: Strategic Trends and Commercial Opportunities
Market Overview and Pressing Challenges
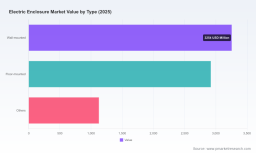
The electric enclosure market has entered a phase of sustained expansion, with revenue projected to grow from approximately $5.5 billion in 2020 to just over $12.2 billion by 2032. This translates to a compound annual growth rate of 7.5 percent over the forecast period, signaling a market that is outpacing broader industrial equipment segments. The trajectory reflects more than cyclical demand; it is being reshaped by fundamental shifts in how electrical infrastructure is designed, deployed, and protected across multiple end-use ecosystems. Growth has been consistent across recent years, with revenue climbing through 2025 and accelerating into the mid-2030s as new infrastructure build-outs and modernization programs scale globally.
Despite the positive outlook, the industry faces structural friction that will separate agile participants from those relying on legacy operating models. First, the widening gap between standardized protection requirements and increasingly demanding environmental conditions is forcing rapid product adaptation. Enclosures must now accommodate submersion-level ingress protection, extreme thermal cycling, and corrosive exposure while maintaining accessibility for maintenance and compliance verification. Second, regulatory complexity is intensifying across jurisdictions. Compliance frameworks around environmental sealing, installation marking, and voltage-specific safety considerations are becoming more prescriptive, raising the cost of non-compliance and narrowing the window for generic solutions. Third, supply chain volatility and input cost fluctuations continue to pressure margins, particularly for manufacturers balancing metallic and non-metallic material portfolios against fluctuating steel, polymer, and casting costs. These dynamics are not isolated headwinds; they are reshaping competitive criteria and forcing a reevaluation of where value is created in the enclosure value chain.
PW Consulting Automotive & Machinery Research Center
Key Drivers Reshaping Market Trajectory
Technological Innovation and Performance Thresholds
Performance expectations for electric enclosures have evolved beyond basic containment. The integration of advanced sealing architectures, corrosion-resistant material formulations, and pre-engineered mounting interfaces is enabling faster deployment in environments that previously required custom engineering. Die-cast and rigid enclosure platforms are increasingly being offered with expanded ingress protection ratings and surface-mount options, reducing on-site fabrication time and improving consistency across installations. Simultaneously, climate control integration and thermal management features are becoming standard considerations for enclosures deployed in energy distribution, industrial automation, and data center-adjacent applications. This shift is moving enclosures from passive housings toward integrated protection systems, where reliability, serviceability, and environmental resilience directly influence procurement decisions.
Electronic Plastic Enclosure Market
Policy, Standards, and Compliance-Driven Demand
Regulatory and standards-based requirements are becoming a decisive filter in procurement. Enclosures used in electrical installations must align with recognized environmental protection classifications, installation marking directives, and safety considerations for systems operating up to higher voltage thresholds. In parallel, underground utility enclosures and power distribution assets are subject to specifications that address longevity, accessibility, and environmental safety. These requirements are not static; they are tightening in sectors where failure costs are high, such as EV infrastructure and data center power ecosystems. As a result, compliance capability is increasingly a market entry condition rather than a differentiator, pushing manufacturers to standardize certification pathways and design products that can satisfy multiple jurisdictional expectations without costly customization.
Demand-Side Shifts Across Industrial, Energy, and Utility Applications
Demand is being pulled from multiple directions. Industrial control systems continue to represent a substantial share of consumption, but growth is increasingly linked to modernization programs that replace aging enclosures with more durable, modular, and service-friendly alternatives. Energy and power applications are expanding as grid hardening, distributed generation, and EV charging infrastructure accelerate deployment cycles. At the same time, non-metallic conduit and enclosure accessories are gaining traction in applications where weight, corrosion resistance, and installation flexibility matter more than traditional metallic form factors. This diversification is broadening the addressable market while also fragmenting buying criteria, since project owners now weigh environmental exposure, maintenance access, longevity, and installation speed alongside base pricing.
Supply Chain and Cost Structure Evolution
Material availability and pricing dynamics remain central to margin management. Manufacturers with diversified material strategies—spanning steel, stainless steel, fiberglass, and polymer solutions—are better positioned to adapt to regional cost shifts and lead-time disruptions. Procurement teams are also placing greater emphasis on component standardization and interchangeability to reduce inventory complexity and streamline replacement cycles. The competitive advantage is increasingly tied to design efficiency, manufacturing scalability, and the ability to maintain certified product lines without sacrificing responsiveness. Companies that can align material selection with application-specific performance requirements while preserving cost predictability are capturing outsized share in a market where price competition alone is insufficient.
Competitive Landscape and Leading Strategies
Established Players and Strategic Positioning
The market remains moderately concentrated, with the largest players holding meaningful but not dominant shares, leaving room for specialized and regional competitors to thrive through application focus and service capabilities. Leading manufacturers are differentiating through a combination of material breadth, certification maturity, and application-specific engineering rather than volume pricing alone. For example, some firms emphasize rugged die-cast platforms with expanded ingress protection and flexible mounting configurations, targeting environments where reliability and installation simplicity are paramount. Others focus on enclosures designed for harsh conditions, pairing protection with climate control and EV-related inverter solutions to address integrated deployment needs. Utility and underground-focused manufacturers are leaning into below-ground and fiber-reinforced solutions for power distribution, while large industrial suppliers are expanding standard and non-metallic enclosure ranges to serve commercial and industrial projects at scale. Modular, freestanding, and hygienic-design offerings further illustrate how product families are being shaped around maintenance, sanitation, and configuration flexibility. Universal enclosure ranges that span metal, plastic, and polyester options are also being positioned for indoor and outdoor power distribution use, reflecting a push toward cross-environment applicability.
Recent Signals from the Market
Recent product and commercial activity underscores how companies are translating these strategies into executable moves. A major die-cast enclosure supplier introduced an IP68-rated flanged variant with added surface-mount options, extending the versatility of a rugged series for applications requiring higher environmental protection and easier installation alignment. In parallel, a non-metallic conduit specialist expanded its portfolio with new conduit bodies and gang boxes, reinforcing the shift toward lightweight, corrosion-resistant protection solutions for electrical installations. On the commercial side, a diversified enclosures and electrification player reported record first-quarter sales, orders, and backlog while raising full-year guidance, reflecting sustained demand across enclosure-adjacent segments and the confidence of customers in continued infrastructure investment. These developments point to a market where capability expansion, certification readiness, and demand visibility are reinforcing each other.
Market Structure Evolution
The competitive map is evolving along three axes. Consolidation is likely to continue among mid-tier players seeking scale in certification, distribution, and material procurement, while fragmentation will persist where regional compliance nuances, specialized materials, or niche application requirements create barriers to one-size-fits-all offerings. New entrants and adjacent players are finding opportunities in modular design, integrated thermal management, and non-metallic alternatives that lower installation friction. The broader trend is toward portfolios that balance standardized, certifiable platforms with configurable options that reduce custom engineering without sacrificing performance. Companies that can navigate this balance while maintaining regulatory alignment and supply chain resilience are best positioned to capture share as procurement teams increasingly prioritize lifecycle value over upfront cost.
Future Outlook: Trends and Commercial Implications
Higher Protection Standards as a Baseline Expectation
Over the next three to five years, stronger environmental protection and safety alignment will become baseline expectations rather than premium features. This will accelerate adoption of enclosures that already meet rigorous ingress and durability criteria, especially in EV infrastructure, data center power environments, and utility deployments where downtime and exposure risks carry significant financial consequences. The commercial opportunity lies in standardizing certified, high-protection platforms that reduce project risk and accelerate approval timelines. Manufacturers and solution providers that can offer repeatable compliance across multiple environments will see stronger demand pull, while late movers may face rising rejection rates and retrofit costs.
Modular and Configurable Designs as a Growth Multiplier
Configurability is emerging as a powerful growth lever. Modular enclosure systems, interchangeable mounting options, and pre-engineered accessories allow end users to adapt solutions to changing site conditions without redesigning from scratch. This modularity also supports maintenance, expansion, and replacement cycles, aligning product economics with long-term asset management priorities. The opportunity here is not simply offering more parts, but designing families that balance standardization with flexibility, enabling faster specification, reduced inventory burden, and lower field error rates. Solutions that make specification easier and retrofit less disruptive will gain preference in recurring industrial and energy projects.
Material Diversification and Non-Metallic Expansion
Material strategy will increasingly define competitive relevance. As installation environments become more varied and corrosive-resistance requirements rise, non-metallic and hybrid material solutions will capture additional share in specific applications, while stainless steel and fiber-reinforced options continue to serve harsh or sanitary-use conditions. Manufacturers that maintain disciplined material-to-application mapping, supported by reliable sourcing and clear certification documentation, will be better equipped to manage cost swings and meet project-specific constraints. The risk lies in over-indexing on any single material category without adequate application validation, which can create exposure to substitution pressure and regional cost volatility.
Actions for Decision-Makers
For Manufacturers and Solution Providers
Invest in platform-level design that supports multiple protection ratings, mounting configurations, and material options without fragmenting the core product architecture. Prioritize certification readiness and documentation as core capabilities, since compliance now functions as a procurement prerequisite in many sectors. Expand application-specific accessory ecosystems to reduce field customization, and align supply planning with material variability so that lead times and cost structures remain stable as demand scales.
Electric Control Cabinet Market
For Investors and Strategic Buyers
Evaluate exposure to segments where protection requirements are tightening fastest and where backlog visibility suggests durable demand. Look for companies that combine modular design, material flexibility, and strong compliance footprints, since these attributes support both share gain and margin resilience. Assess supply chain and sourcing strategies as indicators of future cost control, and consider how well-positioned a company is to serve energy distribution, industrial modernization, and infrastructure build-outs rather than relying on single-sector cyclicality.
For Procurement and End-User Teams
Shift evaluation criteria toward lifecycle protection, installation efficiency, and compliance certainty rather than lowest initial unit cost. Standardize on enclosure platforms that can be specified across multiple sites and environmental conditions to reduce specification errors and replacement complexity. Where possible, prioritize solutions with clear certification alignment and modular accessory support, since these reduce project risk and improve long-term maintainability as installations evolve.
For decision-makers seeking deeper segmentation, company-level performance benchmarks, regional deployment patterns, and application-specific sizing, a comprehensive market report can provide the granularity needed to translate these trends into precise commercial plans. Detailed breakdowns of product families, end-use demand, competitive positioning, and forward demand scenarios help shorten the path from insight to execution, especially when paired with tailored assessments of where to prioritize investment, sourcing, and specification strategy.
For detailed analysis of this topic, please visit the official page: Electric Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com