

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Online Accounting Software Market: Why a 9.6% CAGR and SaaS Shift Change Everything

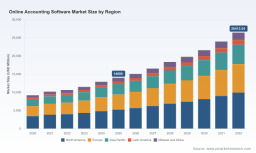
The $26 Billion Horizon: Strategic Shifts in the Online Accounting Software Market
The global online accounting software market has matured into a foundational digital infrastructure for enterprises of every scale. With revenue surpassing $14 billion in 2025 and a projected expansion to approximately $26.4 billion by 2032, the sector is advancing at a compound annual growth rate of 9.6 percent. This trajectory reflects more than routine digitization; it signals a structural realignment in how firms capture, reconcile, and act upon financial data. As cloud-native platforms replace legacy on-premise systems, accounting software is increasingly functioning as the operational core of broader enterprise technology stacks. For executives, strategists, and investors, the critical question is no longer whether to adopt online accounting solutions, but how to navigate the compounding technological, regulatory, and competitive dynamics that will determine market positioning over the next half decade.
Despite the favorable growth trajectory, the industry confronts several structural friction points that are reshaping vendor roadmaps, customer purchasing behavior, and capital allocation strategies. First, legacy migration and process standardization remain persistent barriers. Organizations still operating fragmented spreadsheets, outdated desktop packages, or heavily customized ERPs face steep integration and training costs. The perceived risk of operational disruption often delays adoption, even when long-term efficiency gains are clear. Second, the accounting talent bottleneck is intensifying. As platforms automate data entry, reconciliation, and reporting, firms are demanding higher-order analytical and advisory capabilities from finance teams, yet the pipeline of professionals skilled in both financial operations and digital tooling remains constrained. Third, the post-pandemic normalization of remote and hybrid work models has altered procurement expectations. Decision-makers now prioritize seamless cross-device access, real-time collaboration, and integration with geographically distributed banking and payment ecosystems. These pressures are not merely operational; they are redefining vendor selection criteria and accelerating the shift from point-solution purchasing toward unified, workflow-aware platforms.
Market authorities, vendor product cycles, and macroeconomic indicators point to a clear inflection point. Cloud accounting is no longer a convenience layer; it is becoming the data spine for treasury management, compliance automation, and strategic decision-making. The firms that will capture disproportionate value are those that align platform capabilities with these evolving operational realities rather than simply replicating traditional bookkeeping functions in a browser.
Key Drivers Reshaping the Market
Technology Innovation and the Automation Ceiling
The most consequential driver in the online accounting software space is the rapid integration of artificial intelligence and machine learning into core financial workflows. Early automation focused on rule-based transaction categorization and recurring invoice generation. Contemporary platforms are advancing toward intelligent reconciliation, contextual anomaly detection, and narrative financial summarization. Vendors are embedding AI-assisted bookkeeping, predictive cash flow modeling, and automated audit trail generation directly into cloud environments. The operational impact is substantial: finance teams are reducing manual review cycles, lowering error rates in high-volume transaction processing, and freeing capacity for scenario planning and working capital optimization. For mid-market and enterprise buyers, the value proposition has shifted from basic digitization to continuous, low-friction financial intelligence.
This shift is already visible in product development cycles across the ecosystem. Platform updates from major providers increasingly emphasize generative capabilities for report drafting, intelligent receipt and invoice matching, and natural-language query interfaces. The underlying trend is a gradual erosion of the traditional boundary between accounting software and broader financial operations platforms. As AI handling of routine tasks reaches higher accuracy thresholds, vendors are reallocating engineering resources toward workflow orchestration, multi-entity consolidation, and real-time decision support. Providers that treat automation as a standalone feature rather than an integrated capability risk commoditization, while those that embed it into end-to-end processes are building defensible switching costs.
Accounting Software Market
Regulatory and Data Infrastructure Pressures
The regulatory and infrastructure environment is exerting a quieter but increasingly material influence on cloud accounting deployment. Data sovereignty requirements, cross-border reporting mandates, and evolving audit expectations are pushing vendors to invest in regional compliance frameworks and localized data handling options. Simultaneously, the physical and economic realities of cloud infrastructure are entering strategic conversations. Hyperscale data center demand driven by AI and cloud workloads is projected to more than double by the end of the decade, raising compute and storage costs that eventually cascade into software pricing, tier structures, and service-level commitments. In several U.S. jurisdictions, state-level returns on data center investments have fallen materially short of projections, prompting stricter permitting, sustainability reviews, and community-level scrutiny. Multiple large-scale facilities faced delays or denials in recent periods, and a significant volume of infrastructure capital remains stalled in permitting pipelines.
These dynamics carry direct implications for online accounting providers. Vendors dependent on centralized hyperscale environments may face capacity constraints, latency trade-offs, or cost pressures that affect scalability and deployment timelines. For enterprise buyers, this translates into a more complex evaluation matrix that now includes provider infrastructure resilience, data residency options, and long-term pricing stability. The regulatory and infrastructure conversation is no longer a back-office concern; it is becoming a factor in vendor selection, contract structuring, and multi-year technology planning.
Demand-Side Shifts and the Rise of Platform Ecosystems
Customer expectations are evolving faster than the traditional accounting software catalog. Small and mid-sized businesses increasingly view financial tooling not as isolated bookkeeping systems but as integrated components of broader operational workflows that span invoicing, payroll, inventory, CRM, banking, and payment processing. Large enterprises, meanwhile, are prioritizing consolidation, advanced multi-entity reporting, subscription billing, and alignment with existing ERP and treasury environments. In both segments, procurement decisions are being driven by interoperability, user experience, and the ability to reduce context-switching across tools. Buyers are less willing to accept rigid, standalone packages and more inclined toward modular ecosystems that can scale with organizational complexity.
This demand evolution is reshaping competitive positioning. Vendors that originally built value propositions around specific audience segments are expanding their functional footprints, while broader technology and financial services players are entering the accounting workflow space through partnerships, embedded finance products, or integrated platform suites. The result is a marketplace where differentiation increasingly depends on integration breadth, workflow customization, and the depth of domain-specific automation rather than basic cloud availability.
Competitive Landscape and Strategic Positioning
Divergent Models Among Established Leaders
Intuit maintains a strong foothold through cloud accounting platforms tailored to small and mid-sized businesses, emphasizing AI-assisted bookkeeping, invoicing, and real-time financial visibility. Its strategic emphasis has been on embedding accounting within a broader small-business ecosystem, reducing friction in everyday financial operations, and expanding the addressable use case beyond traditional ledger management. Xero has cultivated a distinct position by prioritizing real-time bank synchronization, workflow automation, and multi-currency capabilities for small to mid-sized firms. Its differentiation rests on open integration architectures and a partner network that extends platform functionality across geographies and verticals. Sage continues to focus on mid-market and enterprise complexity, offering cloud ERP and accounting solutions with advanced financial consolidation, subscription billing, and multi-entity governance. Its trajectory reflects a push toward higher-value financial management rather than transactional bookkeeping alone.
Wave and FreshBooks illustrate another strategic axis: highly segmented, user-centric solutions for freelancers, service businesses, and early-stage companies. Their emphasis on free or low-friction entry points, time tracking, expense management, and simplified invoicing demonstrates how specialized positioning can sustain growth in crowded segments by reducing adoption barriers and aligning tightly with specific workflow patterns. Zoho Books reflects the broader platform-play approach, bundling accounting with automation and cross-application interoperability for small businesses and startups, leveraging ecosystem scale to offer extensive user capacity and integrated process flow.
Recent events underscore the intensity of this competitive recalibration. In early 2025, a major provider expanded its North American presence with a new headquarters designed to accelerate cloud accounting growth and client collaboration. Later in the year, a newer entrant introduced an AI-enabled accounting agent for cloud environments, reporting high accuracy in reconciliations and receipt matching. A workflow specialist released a cloud-based practice management tool aimed at accounting firms, targeting client communication and internal process coordination. Meanwhile, a large enterprise cloud provider embedded a generative AI assistant capable of drafting financial reports and narrative summaries, and a commercial bank launched an integrated cloud accounting platform connecting banking services directly to bookkeeping for enterprise clients. These moves are not isolated product launches; they signal converging strategies around AI capability depth, workflow orchestration, and ecosystem integration.
Consolidation, Fragmentation, and New Entry Dynamics
The market is simultaneously exhibiting consolidation and differentiation. Larger players are pursuing broader functional coverage, deeper enterprise features, and strategic partnerships that extend reach into banking, payroll, and practice management. At the same time, specialized solutions continue to thrive by occupying narrow segments with superior user experience, rapid deployment, or vertical-specific automation. New entrants are emerging around AI-native reconciliation, automated compliance support, and embedded financial services, often competing on accuracy, speed, and workflow simplicity rather than legacy feature breadth.
Market concentration remains moderate, with a limited number of large vendors commanding a meaningful share of revenue while a long tail of niche and regional providers competes on service quality, localization, and integration depth. This structure suggests that competitive advantage will increasingly derive from execution quality, ecosystem relationships, and the ability to reduce total cost of ownership across the finance function rather than from proprietary ledger technology alone. For buyers, the implication is a more dynamic evaluation environment in which switching costs, integration commitments, and long-term roadmap alignment matter as much as current feature sets.
Outlook: Three Trends Shaping the Next Three to Five Years
From Bookkeeping to Continuous Financial Operations
Over the next several years, online accounting software is likely to be evaluated less as a record-keeping tool and more as a continuous financial operations layer. AI-driven reconciliation, anomaly detection, and automated reporting will become baseline expectations rather than premium differentiators. Platforms that can synthesize transactional data, banking flows, and operational inputs into forward-looking insights will gain preference in both mid-market and enterprise segments. This shift creates opportunities for vendors to expand into working capital optimization, scenario modeling, and advisory-adjacent workflows. It also raises the stakes for providers that remain anchored in retrospective accounting functions, as customers increasingly expect systems that support both compliance and decision velocity.
A persistent risk in this trajectory is the potential for uneven AI reliability across edge cases, multilingual contexts, and highly customized transaction structures. Buyers will need to balance automation enthusiasm with controlled adoption, particularly in regulated industries or multi-entity environments where auditability and explainability remain critical.
PW Consulting
Infrastructure Economics and Compliance as Strategic Variables
The economics of cloud infrastructure and the evolving regulatory landscape will increasingly influence software strategy. As compute and storage demands intensify, providers will need to manage cost structures more deliberately, potentially influencing pricing tiers, feature packaging, and data handling models. Regional compliance, data residency expectations, and sustainability-related review processes will add complexity to deployment planning, especially for global organizations. Vendors that design for flexibility—through regional deployments, modular architecture, and transparent cost models—will be better positioned to maintain scalability without eroding customer trust.
For buyers, this environment calls for more rigorous due diligence on provider infrastructure roadmaps, data governance practices, and long-term service continuity. The risk is not only cost escalation but also potential deployment friction if local permitting, energy constraints, or regulatory reviews slow capacity expansion. Organizations that treat infrastructure resilience and compliance alignment as evaluation criteria today will be better insulated from disruption tomorrow.
Ecosystem Embedding and the Blurring of Financial Toolsets
The third major trend is the progressive integration of accounting software into broader financial and operational ecosystems. Banking integrations, embedded payments, payroll connectivity, and practice management workflows are reducing the isolation of accounting tools and making them part of a continuous enterprise data flow. This convergence benefits users through reduced manual handoffs and improved data consistency, but it also complicates vendor landscapes. Procurement teams will face an expanding set of integration choices, partnership dependencies, and data-sharing considerations. Vendors that offer open, well-documented integration frameworks and clear data portability options will capture advantage in an environment where lock-in risk is increasingly scrutinized.
The opportunity here lies in building or selecting platforms that operate as connective tissue rather than closed silos. Enterprises that align accounting systems with treasury, payments, and operational planning tools can accelerate close cycles, improve forecast accuracy, and support more agile resource allocation. The uncertainty is that rapid ecosystem expansion can outpace governance maturity, creating data quality, access control, and vendor management challenges if not addressed early.
Strategic Implications for Decision Makers
For enterprise and mid-market executives evaluating online accounting software, the immediate priority is to reframe selection criteria around workflow continuity and integration economics rather than feature checklists. Platforms should be assessed on their ability to embed into existing financial operations, reduce reconciliation and reporting friction, and support the analytical needs of finance teams as they shift from data processing to interpretation and advisory work. Migration planning should account not only for transaction history and reporting requirements but also for training, process redesign, and the talent implications of higher automation levels. Organizations that treat adoption as a finance-transformation initiative rather than a software upgrade will derive materially greater value.
Cloud Accounting Software Market
For investors and corporate development teams, the market signals point toward selective value creation rather than uniform sector upside. AI-enabled accuracy, ecosystem integration, and enterprise-grade consolidation capabilities are becoming primary drivers of competitive differentiation. Companies that rely solely on commoditized cloud bookkeeping or that lack credible paths to interoperability and workflow depth face margin and retention pressure. Conversely, providers with strong partner networks, clear segment focus, and credible automation roadmaps are positioned to capture share as buyers move from basic digitization to performance-oriented financial tooling. Due diligence should emphasize retention dynamics, integration breadth, customer segment alignment, and infrastructure cost resilience.
For procurement and finance operations leaders, the practical mandate is to build evaluation frameworks that anticipate the next cycle of platform evolution. This includes demanding transparency on data handling, AI-assisted workflows, update cadence, and integration commitments; testing platforms against real operational scenarios rather than scripted demos; and negotiating contracts that preserve flexibility as requirements evolve. Early attention to data governance, user adoption planning, and cross-functional workflow mapping will reduce the risk of fragmented deployments and underutilized capabilities. In practice, the organizations gaining the most from online accounting software are those that align platform selection with broader finance operating models and treat tooling as an enabler of process redesign rather than a standalone purchase.
The strategic landscape of online accounting software is shifting from incremental digitization to integrated financial operations, shaped by AI maturation, infrastructure and regulatory realities, and increasingly connected enterprise ecosystems. Market sizing and growth trajectories provide a useful directional backdrop, but the durable sources of advantage will come from execution quality, workflow depth, and the ability to reduce friction across the full finance function. Decision makers who evaluate platforms with these dynamics in mind, and who seek detailed segmentation, vendor benchmarking, and region-specific deployment considerations, will be better positioned to convert market growth into operational advantage. For a closer examination of segment-level dynamics, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting market research report offers a more granular view of the opportunities and trade-offs ahead.
For detailed analysis of this topic, please visit the official page: Online Accounting Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com