

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electroretinography Market: Why 8% CAGR and Clinical Diagnostics Shift Strategy

Strategic Trends and Commercial Opportunities in the Electroretinography Market
The electroretinography (ERG) market has entered a phase of structural expansion, driven by the convergence of regulatory alignment, technological miniaturization, and the clinical need for objective functional assessment of retinal health. Spanning a base year of 2025 with historical tracking from 2020 through 2025 and a forecast period extending to 2032, the market demonstrates a consistent upward trajectory. Revenue grew from 300.0 million in 2020 to an estimated 414.0 million in 2025, and is projected to reach 711.32 million by 2032, reflecting a compound annual growth rate of 8.0 percent. This growth is not merely incremental; it signals a market transitioning from a niche diagnostic tool toward a more integrated component of routine ophthalmic and neurological evaluation.
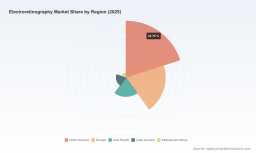
The revenue distribution across testing modalities reveals a clear hierarchy. Full-field flash ERG remains the dominant segment, accounting for the largest share of market value, while multifocal ERG holds a substantial secondary position, reflecting its growing utility in localized retinal function mapping. Pattern ERG and other specialized variants occupy smaller but strategically important niches, often tied to specific clinical indications or research applications. On the application side, clinical diagnostics represent the overwhelming majority of demand, with research activities comprising a meaningful but smaller portion. Geographically, North America leads in market size, followed by Europe, with the Asia Pacific region representing a smaller but rapidly evolving base. Latin America and the Middle East and Africa collectively account for a modest share, though emerging healthcare infrastructure investment suggests latent demand that may unlock as reimbursement pathways mature.
Market concentration remains relatively fragmented. The top three participants collectively hold approximately 24.6 percent of revenue, while the top five reach 26.2 percent. This dispersion indicates that no single entity controls the market, leaving room for strategic consolidation, differentiated technology plays, and regional expansion by mid-tier manufacturers. The absence of dominant concentration also suggests that competitive advantage will increasingly derive from clinical validation, reimbursement alignment, and workflow integration rather than sheer scale alone.
1. Market Status and Core Challenges
The electroretinography market operates at the intersection of diagnostic precision and practical clinical adoption. Despite clear growth signals, several structural challenges shape how manufacturers, providers, and investors approach the space.
PW Consulting
1.1 Reimbursement Ambiguity and Coding Fragmentation
One of the most persistent friction points is the uneven reimbursement landscape for ERG testing. While certain Current Procedural Terminology codes, such as CPT 92273 for full-field ERG with interpretation and report, are recognized under Medicare with defined reimbursement levels and supported by major Medicare Administrative Contractors for medically necessary indications, coverage is not universal across payers. Pattern ERG codes, for example, are frequently classified as investigational by commercial insurers, creating a reimbursement gap that limits routine adoption in some clinical settings. This fragmentation forces manufacturers and provider networks to navigate a patchwork of coverage policies, which can slow procurement cycles and complicate revenue forecasting for diagnostic service providers.
1.2 Standardization Gaps and Protocol Variability
Although the International Society for Clinical Electrophysiology of Vision has published updated standards for full-field clinical electroretinography to promote reproducible recordings using dark-adapted and light-adapted stimuli, real-world implementation varies. Differences in stimulus calibration, electrode placement, patient preparation, and interpretation workflows can affect result consistency across sites. For clinicians, this variability can undermine confidence in ERG as a longitudinal monitoring tool, particularly when integrating findings with structural imaging modalities. For manufacturers, it creates both a challenge and an opportunity: devices that embed standardized protocols, built-in quality checks, and guided workflows can reduce inter-site variability and improve adoption.
1.3 Workflow Integration and Clinical Practicality
Traditional ERG testing has often been perceived as technically demanding, time-consuming, and dependent on dilated pupils or specialized setups. In high-volume clinical environments, any test that disrupts patient flow or requires extensive technician training faces adoption friction. The market is therefore at a turning point where portability, non-mydriatic operation, and streamlined interpretation are becoming decisive factors. Devices that reduce preparation time, allow testing in broader patient populations including newborns and non-cooperative patients, and integrate with existing electronic health record workflows are better positioned to convert clinical interest into sustained purchasing decisions.
2. Key Demand Drivers
The growth trajectory of the electroretinography market is not accidental; it reflects a set of reinforcing drivers that are reshaping how retinal function is assessed, reimbursed, and commercialized.
2.1 Technological Innovation and Portable Non-Mydriatic Systems
The most consequential technological shift is the emergence of handheld, portable ERG platforms that enable functional retinal assessment without dilation and with reduced setup complexity. These systems expand the feasible testing environment beyond specialized electrophysiology labs to outpatient clinics, primary care-linked ophthalmology settings, and even screening programs. By lowering the practical barriers to testing, portable devices increase the addressable patient population and create new use cases for routine diabetic retinopathy monitoring, glaucoma suspect evaluation, and inherited retinal disease screening. The clinical value proposition is reinforced when portable systems demonstrate performance comparable or superior to conventional imaging in predicting disease progression, particularly in moderate to severe non-proliferative diabetic retinopathy, where functional assessment can complement structural imaging and help identify patients at risk of vision-threatening complications.
2.2 Regulatory Clarity and Guideline Alignment
Regulatory and guideline developments are steadily reducing uncertainty around ERG’s clinical role. The inclusion of full-field and multifocal ERG in updated ophthalmologic preferred practice pattern guidelines for diabetic retinopathy management represents a meaningful endorsement, signaling that functional testing has a place in routine disease management rather than being confined to specialized referrals. At the same time, FDA clearance pathways and international certification frameworks, including ISO 13485 and MDSAP compliance, provide a structured route for manufacturers to demonstrate safety and performance. The alignment between standards bodies, regulatory agencies, and clinical guidelines creates a more predictable environment for product development and market entry, particularly for devices that are designed to meet ISCEV-aligned protocols from the outset.
Automated Ophthalmic Perimeters Market
2.3 Demand-Side Shifts Toward Objective Functional Biomarkers
Clinicians and health systems are increasingly seeking objective, quantifiable functional biomarkers that can track disease progression, guide treatment decisions, and support payer discussions. Structural imaging alone does not always capture functional decline, especially in early or moderate disease stages where anatomical changes may be subtle. ERG provides a direct measure of retinal electrical response, offering a complementary data point that can strengthen diagnostic confidence and support longitudinal monitoring. This demand-side shift is particularly relevant in diabetic retinopathy management, where the ability to identify patients at higher risk of progression can influence follow-up intervals, referral patterns, and intervention timing. As value-based care models emphasize outcomes and risk stratification, functional testing that contributes to more precise patient management becomes more attractive to providers and payers alike.
2.4 Supply Chain Consolidation and Portfolio Integration
Recent corporate activity illustrates a broader supply-side trend: established medtech and electronic instruments companies are expanding their ophthalmic diagnostic portfolios through acquisition and integration. By absorbing specialized ERG manufacturers, larger platforms can combine regulatory expertise, distribution networks, and cross-selling capabilities with proven clinical technologies. This consolidation can accelerate market reach, improve service and support infrastructure, and create bundled solutions that pair ERG with other diagnostic modalities. For smaller manufacturers, the environment presents both pressure and opportunity: pressure from potential acquisition or competition with better-resourced rivals, but also opportunity to differentiate through proprietary stimulation methods, advanced protocol libraries, or region-specific reimbursement strategies.
3. Competitive Landscape and Leading Strategies
The competitive field in electroretinography is characterized by a mix of established electrophysiology specialists, vision monitoring companies, and broader diagnostic portfolios that have expanded into retinal functional testing. Rather than competing solely on hardware specifications, leading players are increasingly differentiating through clinical evidence, workflow design, regulatory positioning, and ecosystem integration.
3.1 Strategic Positioning of Leading Participants
Several companies illustrate the range of viable strategic postures within the market. One U.S.-based manufacturer has concentrated on portable, handheld full-field ERG and visual evoked potential systems, emphasizing FDA-cleared, non-mydriatic operation suitable for clinical functional assessment. This positioning targets the practical adoption barrier directly, making the technology accessible in settings where conventional ERG infrastructure is impractical. Clinical evidence linking the device’s scoring approach to prediction of progression in moderate to severe non-proliferative diabetic retinopathy further strengthens the commercial narrative by tying the product to a high-impact clinical use case.
Another U.S. specialist focuses on full-field and multifocal ERG systems with advanced protocols for both clinical and research electrophysiology. This company’s strategy leans toward technical depth, protocol flexibility, and support for rigorous electrophysiological evaluation, appealing to centers that require detailed functional mapping and research-grade capability. In Europe, a French manufacturer has built its identity around a vision monitoring platform that supports multiple ERG modalities and visual evoked potential testing, incorporating proprietary constant-luminance stimulation methods. This approach highlights the importance of stimulation precision and modality breadth as differentiators for customers who need a single platform capable of spanning multiple testing requirements.
A German producer emphasizes electrophysiological diagnostic systems for clinical use across full-field, multifocal, and pattern ERG as well as visual evoked potential testing, positioning around clinical reliability and standards alignment. A U.S. vendor offering multifocal and flash ERG systems for clinical settings continues to serve a segment that values established platforms and specialized electroretinography equipment. An Italian manufacturer provides clinical ERG and electrophysiological diagnostic equipment with an emphasis on compliance with international standards, which can be an important factor in markets where regulatory and procurement processes are closely tied to certification and conformity. A Russian manufacturer has extended its reach into full-field and extended ERG testing across age groups, including newborns, illustrating how demographic coverage and pediatric capability can open niche but valuable application spaces.
Worldwide 12 Channel Electrocardiograph Market
The acquisition of the portable ERG platform by a larger electronic instruments company in early 2026 exemplifies the portfolio integration strategy. By embedding the handheld device within a broader ophthalmic diagnostics portfolio, the acquiring company gains a differentiated functional testing offering, an established regulatory and quality framework, and a channel to expand distribution. This move also signals to the market that portable non-mydriatic ERG is viewed as a strategic asset rather than a peripheral niche product.
3.2 Market Evolution Trends
The competitive landscape is evolving along several interrelated dimensions. Consolidation is likely to continue as larger platforms seek to strengthen their diagnostic portfolios and smaller specialists evaluate whether independence or partnership better serves their growth ambitions. At the same time, differentiation is shifting toward clinical validation, reimbursement readiness, and workflow integration. Devices that can demonstrate alignment with recognized standards, support Medicare and commercial coverage pathways, and fit smoothly into clinic operations are gaining an advantage over products that rely primarily on technical specifications.
Regional dynamics also shape competition. In North America, reimbursement alignment and guideline inclusion are powerful adoption catalysts, favoring products with strong regulatory documentation and clinical evidence. In Europe, standards conformity, multi-modality platforms, and regional service networks influence purchasing decisions. In Asia Pacific and other emerging markets, adoption may be more sensitive to price, training support, and the ability to operate in varied clinical settings, suggesting that a one-size-fits-all go-to-market approach will underperform. New entrants that can address specific gaps, such as pediatric testing, portable screening, or integrated interpretation tools, may find opportunities even in a market with established incumbents.
4. Future Trend Predictions
Looking ahead across the next three to five years, several trends are likely to define the market’s direction and shape the commercial opportunities available to manufacturers, providers, and investors.
4.1 From Specialized Testing to Routine Functional Assessment
As portable, non-mydriatic systems mature and clinical guidelines continue to recognize the role of full-field and multifocal ERG in conditions such as diabetic retinopathy, functional retinal testing is likely to move from specialized referral settings toward more routine use. This shift creates opportunities for manufacturers to design products that prioritize speed, ease of use, and interpretation support, and for providers to build service lines around objective functional monitoring. The commercial implication is clear: devices that can be deployed in broader clinical environments and supported by clear reimbursement logic will capture more consistent demand than those tied to niche specialist workflows.
4.2 Evidence-Led Adoption and Predictive Clinical Value
The next phase of adoption will be increasingly driven by clinical evidence that ties ERG findings to meaningful outcomes, particularly risk stratification and progression prediction. Studies demonstrating that functional scoring can outperform or complement structural imaging in forecasting vision-threatening complications provide a template for how evidence can accelerate uptake. As more data accumulate, sales cycles may shorten in settings where ERG is framed not merely as an alternative test but as a decision-support tool that influences management. Manufacturers and service providers that invest in robust clinical validation and real-world evidence generation will be better positioned to justify formulary inclusion, procurement priority, and payer coverage.
4.3 Ecosystem Integration and Multi-Modal Workflows
ERG is unlikely to replace structural imaging; instead, it will increasingly be integrated into multi-modal diagnostic workflows. Platforms that combine functional and structural data, support standardized reporting, and connect with electronic health records will offer greater value to busy clinical teams. This trend also encourages portfolio-level competition, where companies aim to provide a coherent diagnostic suite rather than isolated instruments. For investors, this suggests that value may accrue not only to best-in-class standalone devices but also to platforms that can embed ERG within broader ophthalmic or neurological diagnostic ecosystems.
4.4 Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Reimbursement policy remains fluid, and adverse changes to coverage for pattern ERG or shifts in medical necessity documentation requirements could slow adoption in certain segments. Standardization, while improving, is not yet universally implemented; sites that lack trained personnel or consistent protocols may underutilize available technology. Competition from alternative functional or structural assessments, including advanced imaging and artificial intelligence-assisted diagnostics, could compress ERG’s role if those modalities prove more convenient or better reimbursed. Finally, macroeconomic pressure on healthcare capital spending may extend procurement cycles, particularly in smaller practices and emerging markets, making clear return-on-investment arguments more important than ever.
5. Strategic Recommendations for Decision-Makers
Companies operating in or entering the electroretinography market face a landscape where clinical utility, regulatory alignment, and workflow practicality determine commercial success more than specification comparisons alone. The following recommendations translate the current dynamics into actionable priorities for different stakeholder groups.
5.1 For Manufacturers
Develop products with reimbursement and guideline alignment built into the design and commercialization plan, not treated as an afterthought. Where possible, support ISCEV-aligned protocols, document performance against recognized standards, and generate clinical evidence that connects functional testing to decision-making in high-prevalence conditions such as diabetic retinopathy. Prioritize portability, non-mydriatic operation, and streamlined interpretation to broaden the addressable setting beyond specialized labs. Consider whether independent positioning or portfolio integration best fits your capabilities, and invest in service, training, and workflow compatibility to reduce adoption friction.
5.2 For Investors
Evaluate opportunities not only on technology novelty but on the strength of clinical evidence, reimbursement readiness, and the ability to integrate into routine care pathways. Companies that can demonstrate a clear link between functional assessment and risk stratification, supported by credible validation and standards alignment, are better positioned for durable adoption. Monitor consolidation trends, as acquired platforms may gain distribution and service advantages, while independent specialists may offer niche leadership in areas such as pediatric testing, advanced protocols, or region-specific reimbursement strategies. Scrutinize portfolio fit and cross-selling potential when assessing larger platforms that are expanding into ophthalmic diagnostics.
5.3 For Procurement and Clinical Leaders
Assess ERG solutions based on how well they fit into existing workflows, the availability of standardized protocols, and the practical training burden for staff. Favor systems that support consistent, reproducible recordings and provide clear interpretation support, particularly if the goal is to use ERG for longitudinal monitoring or risk stratification. Evaluate total cost of ownership in the context of reimbursement realities, including whether the intended use cases align with covered indications and documentation requirements. Where possible, seek evidence that the selected solution contributes to measurable improvements in patient management, rather than treating ERG as an isolated diagnostic add-on.
The electroretinography market is advancing along a path shaped by portable technology, guideline recognition, and a growing appetite for objective functional biomarkers. The companies and clinical programs that succeed will be those that treat ERG as part of a broader diagnostic strategy, supported by evidence, standards, and practical workflow design. For decision-makers who need granular segmentation data, competitive benchmarking, reimbursement mapping, and customized scenario analysis, a comprehensive market research report can provide the level of detail required to translate these trends into concrete investment, product, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Electroretinography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com