

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Air Sampling Pumps Market: Why 4.53% CAGR and Asia Pacific Demand Redefine Growth Through 2032

Strategic Trends and Commercial Opportunities in the Air Sampling Pumps Market
Market Trajectory and Structural Pressures
The global air sampling pumps market has established a consistent growth trajectory, with revenue reaching approximately USD 59.34 million in 2025 and projected to climb to USD 80.4 million by 2032. This expansion reflects a compound annual growth rate of 4.53 percent across the 2026 to 2032 forecast period, signaling steady demand evolution rather than speculative boom cycles. Historical performance from 2020 through 2025 shows incremental gains, with year-over-year increases ranging from modest to moderate, reinforcing a market driven by regulatory compliance, occupational health priorities, and environmental monitoring requirements rather than volatile consumer behavior.
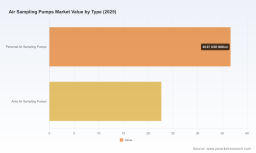
Within this landscape, regional concentration patterns reveal distinct maturity levels. Asia Pacific currently commands the largest revenue share, followed by North America and Europe, while Latin America and the Mideast and Africa represent smaller but developing footprints. The geographic distribution aligns closely with industrial activity density, regulatory enforcement intensity, and the spread of occupational hygiene programs. Product segmentation remains balanced between personal air sampling pumps and area air sampling pumps, each serving distinct monitoring requirements. Application-wise, industrial manufacturing, health industry, and environment industry collectively anchor demand, though their relative weight shifts as regional compliance priorities mature.
Key Challenges and Inflection Points
Despite the predictable growth path, the market faces structural challenges that will test vendor positioning and buyer decision-making in the coming years. The first challenge centers on regulatory alignment across jurisdictions. Monitoring standards increasingly demand tighter control over flow stability, pulsation limits, and post-calibration verification. Equipment that previously met baseline requirements may now fall short when deployed in regions adopting upgraded directives or stricter interpretation of existing standards. Manufacturers must balance compliance readiness with cost accessibility, particularly when serving multi-regional clients with divergent enforcement timelines.
The second challenge involves the tension between precision and portability. Occupational and environmental monitoring teams increasingly require devices that maintain laboratory-grade accuracy while fitting into confined workspaces, mobile monitoring setups, or rapid-deployment scenarios. Engineering teams must navigate competing design priorities: smaller form factors, extended battery performance, and reduced weight must not compromise calibration consistency or flow reliability. Buyers evaluating procurement options often face trade-offs between ruggedized configurations for heavy industrial settings and compact units optimized for indoor air quality or healthcare environments.
A third inflection point relates to market concentration and buyer leverage. The market remains moderately consolidated among established manufacturers, which creates both stability and pricing pressure. While leading vendors benefit from brand recognition, service networks, and long-standing compliance credentials, buyers are increasingly equipped with more information and alternative sourcing options. This dynamic pressures incumbents to justify premium positioning through demonstrable performance advantages, service quality, and integrated support ecosystems rather than heritage alone.
Core Growth Drivers Reshaping Demand
Technology Innovation and Performance Evolution
Product development is shifting from basic flow delivery toward smarter monitoring capability. Recent catalog updates and product introductions signal a clear direction: manufacturers are refining pump platforms to address flow stability, pulsation control, calibration ease, and connectivity for workflow integration. For example, updated personal sampling pump catalogs have introduced refined model specifications that emphasize usability, calibration verification, and application-specific configurations. Meanwhile, new portable air sampling pump additions reflect demand for lighter, more adaptable equipment in indoor air quality and environmental monitoring contexts.
This innovation trajectory matters because it connects directly to operator efficiency and data confidence. Devices that simplify calibration, reduce setup time, and maintain stable flow characteristics under variable conditions reduce the risk of non-compliant sampling results. In practical terms, engineering improvements are not merely product features; they are risk mitigation tools for industrial hygienists, safety managers, and environmental consultants who must produce defensible monitoring records.
Active Air Sampler Market
Regulatory and Standards Pressure as Compliance Catalyst
Regulatory frameworks continue to act as one of the strongest demand drivers. Occupational exposure monitoring depends on methods that require calibrated air sampling pumps with stable flow performance, and several standards reinforce this expectation. ISO 13137:2019, for instance, requires personal sampling pumps to maintain pulsation not exceeding 10 percent of the flow rate to support accurate workplace exposure monitoring. NIOSH NMAM methods reinforce the need for constant flow in analyses involving asbestos, lead, and crystalline silica. OSHA sampling methods further specify flow ranges and post-calibration verification expectations for personal air sampling pumps.
At the regional level, the EU Worker Exposure Directive revision has strengthened pulsation and flow stability requirements across member states, raising the compliance bar for organizations operating in Europe or supplying equipment into that market. These regulatory dynamics create a structural pull for equipment that can demonstrably meet evolving requirements. They also raise the stakes for buyers who must ensure that monitoring programs remain defensible during audits, incident investigations, or internal compliance reviews.
Demand-Side Shifts in Occupational Health and Environmental Monitoring
Demand is increasingly shaped by a broader interpretation of exposure risk. Industrial operations continue to represent a major application base, but health industry and environment industry usage is expanding as organizations broaden monitoring beyond traditional manufacturing floors. Healthcare settings, public facilities, and indoor air quality programs are driving interest in portable and area monitoring equipment that can support indoor environments, infection control-related airflow assessments, and general environmental surveillance.
Simultaneously, workplace safety culture is becoming more data-oriented. Safety teams are placing higher value on repeatable measurements, documented calibration, and equipment that integrates smoothly into field workflows. This shift favors vendors that can support not only the hardware but also the operational discipline surrounding sampling programs. In effect, the market is rewarding solutions that make compliance easier to execute consistently rather than only occasionally.
Supply Chain Realities and Cost Structure Considerations
Cost structures remain an important factor in procurement decisions, especially as organizations balance compliance budgets against broader operational spending. While the market is not experiencing volatile commodity shocks as a dominant narrative, equipment durability, service availability, and replacement part accessibility still influence total cost of ownership. Procurement teams increasingly evaluate pumps not as isolated instruments but as part of a monitoring system that includes calibration equipment, maintenance support, and training.
This broader purchasing lens benefits manufacturers with strong service networks and transparent support models. It also elevates the importance of product longevity and maintainability. In segments where buyers deploy equipment across multiple sites or rotating crews, reliability and service responsiveness can outweigh marginal price differences. As a result, suppliers that can deliver consistent field performance and predictable upkeep gain an advantage in multi-year purchasing decisions.
Competitive Landscape and Strategic Positioning
Established Players and Differentiating Strengths
The market features a set of well-known manufacturers with distinct product and service orientations. SKC Inc. has built recognition around personal air sampling pumps used in occupational exposure monitoring, with pump families designed for field sampling workflows. Sensidyne LP is associated with Gilian personal and high-flow air sampling pumps, along with calibrators supporting industrial hygiene and area sampling, which positions the company at the intersection of sampling and calibration equipment. Zefon International, Inc. offers personal and area environmental monitoring pumps, expanding its relevance across both occupational and environmental use cases. Casella USA provides personal air sampling pumps with connectivity features aimed at workplace exposure assessments, reflecting a strong emphasis on usability and field integration.
These companies differentiate not only through product specifications but also through how they support compliance workflows. Some compete on pump performance and pulsation control. Others emphasize calibration tools, training, documentation support, and field-ready design. The practical distinction for buyers often lies in whether the vendor can reduce the operational burden of sampling programs through integrated hardware, calibration consistency, and reliable after-sales support.
Recent Developments as Indicators of Strategic Focus
Recent company activities provide insight into how incumbents are navigating the market. Trade show participation by major pump and calibrator suppliers has continued through 2025, with exhibition activity at industry events highlighting ongoing engagement with occupational hygiene communities. These appearances are not mere marketing exercises; they function as channels for demonstrating flow performance, calibration practices, and equipment reliability to audiences that evaluate compliance-critical tools.
Product catalog updates have also underscored incremental innovation. Updated pump catalogs have introduced refined model details, while newer portable pump additions have broadened portfolios for indoor and environmental monitoring applications. Such moves suggest that established manufacturers are pursuing portfolio expansion and specification refinement rather than disruptive product replacement. This measured approach aligns with a market where compliance acceptance, service history, and user familiarity carry significant weight.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure appears likely to evolve through a combination of consolidation and targeted differentiation. Moderate market concentration gives leading firms room to defend positions through service networks and compliance credentials, but it also leaves space for specialized entrants in subsegments such as compact indoor air quality monitoring, improved connectivity for field data workflows, or region-specific compliance configurations. Potential consolidation may occur where service coverage, calibration support, and geographic reach become decisive purchase factors.
At the same time, fragmentation remains possible in application-specific niches. Buyers in healthcare environments, environmental consulting, or specialized industrial processes may prioritize features that larger generalist portfolios do not fully optimize. This creates opportunity for companies that can deliver focused solutions, provided they can also meet the compliance and reliability expectations associated with sampling instrumentation.
Forward-Looking Trends and Commercial Implications
Trend 1: Compliance-Driven Product Specifications Will Become a Baseline Expectation
Over the next three to five years, flow stability, pulsation control, and calibration verification are likely to transition from desirable features to baseline requirements in many procurement processes. As regional directives and occupational hygiene methods continue to reinforce consistent sampling performance, equipment that cannot document stable performance will face increasing friction in regulated environments. The commercial implication is clear: manufacturers that proactively align product design and documentation with evolving standards will reduce adoption barriers for compliance-focused buyers.
For procurement teams, this trend increases the importance of verification. Purchasing decisions will need to account not only for flow range and portability but also for how easily a pump can be calibrated, verified, and documented in routine use. Equipment that simplifies compliance workflows will likely command stronger preference in competitive bids.
Trend 2: Connectivity and Field Workflow Integration Will Gain Commercial Weight
As monitoring programs become more data-driven, devices with Bluetooth connectivity, streamlined field setup, and better integration into exposure assessment workflows will become more relevant. Connectivity does not replace measurement accuracy, but it can reduce administrative burden, improve record-keeping consistency, and support faster field decisions. In practical terms, the market is moving toward tools that help teams manage sampling programs more efficiently, not just collect samples more accurately.
Microbial Air Samplers Market
This trend opens commercial opportunities for vendors that can link hardware performance with workflow convenience. It also creates a differentiation path for companies that can demonstrate tangible improvements in setup time, calibration tracking, and exposure assessment documentation. The risk for buyers is overvaluing connectivity without confirming that core sampling performance still meets required standards.
PW Consulting Automotive & Machinery Research Center
Trend 3: Application Diversification Will Redefine Competitive Priorities
Industrial manufacturing will remain a core demand base, but growth in health industry and environment industry applications will encourage product strategies that address a wider range of monitoring contexts. Portable equipment for indoor environments, area sampling for environmental programs, and adaptable configurations for varying flow requirements will become more commercially important. Companies that can serve multiple application profiles without sacrificing compliance credibility will gain broader market relevance.
The corresponding risk is portfolio over-extension. Manufacturers expanding into new application areas must ensure that product claims, calibration support, and service models remain credible for each use case. Buyers in specialized settings will quickly distinguish between equipment that is genuinely suited to their environment and equipment that is merely marketed into it.
Strategic Recommendations for Decision-Makers
For Manufacturers and Suppliers
Prioritize compliance documentation and performance verifiability as core product assets. In a market where regulatory expectations continue to tighten, spec sheets alone are insufficient. Suppliers should ensure that product platforms clearly support flow stability, pulsation control, and calibration verification, and that this support is easy for customers to demonstrate in audits and field use. Equally important is service and calibration support; in compliance-driven purchasing, reliable after-sales infrastructure can be as influential as the instrument itself. Companies should also evaluate whether portfolio expansion into indoor air quality, environmental monitoring, or connectivity-enabled workflows creates genuine differentiation or merely broadens exposure without sufficient support depth.
For Investors
Assess exposure to regulatory-driven demand rather than relying solely on end-market growth narratives. Companies with strong positions in occupational hygiene, industrial hygiene, and compliance-related monitoring are better positioned to benefit from sustained standards pressure. Investment due diligence should examine calibration support, service networks, product acceptance in regulated environments, and the ability to maintain performance claims across multiple jurisdictions. Growth potential is likely to be strongest where vendors can combine product reliability with workflow-relevant features and credible documentation. At the same time, investors should monitor whether expansion into lower-margin application areas dilutes margin stability or operational focus.
For Procurement and Operations Leaders
Evaluate sampling pumps as part of a compliance system rather than as standalone hardware purchases. Total value should account for calibration consistency, field usability, service availability, and the ease of maintaining documentation across multiple sites or rotating crews. Where monitoring programs span different environments, consider whether standardized equipment reduces training burden and audit risk, or whether application-specific tools offer better performance despite increased procurement complexity. It is also prudent to confirm that any connectivity or workflow features do not distract from the fundamental requirement of stable, verifiable flow performance.
Closing Perspective
The air sampling pumps market is moving through a phase where regulatory expectations, workflow efficiency, and application diversification are reshaping purchasing logic. Growth is steady and structurally supported, but competitive advantage will increasingly depend on how well manufacturers translate performance and compliance readiness into practical field value. For buyers, the most effective decisions will come from evaluating equipment against both measurement integrity and operational burden. For suppliers and investors, the opportunity lies in aligning product strategy with the compliance-intensive, workflow-sensitive nature of modern exposure monitoring. Detailed segment-level data, regional breakdowns, and customized scenario analysis can further sharpen these decisions for organizations seeking a more precise path through the market's next phase of development.
For detailed analysis of this topic, please visit the official page: Air Sampling Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com