

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Reinsurance Market 2026: 8.2% CAGR Trajectory and the Real Shifts Reshaping Industry Growth

Reinsurance Market: Strategic Shifts and Commercial Opportunities in a Transforming Landscape
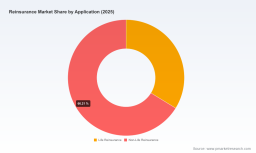
The global reinsurance market has entered a phase of structural expansion, driven by a combination of hardening premiums, evolving risk profiles, and accelerating digital transformation. Following a consistent upward trajectory over the past half-decade, the market surpassed the 200-billion mark in 2024 and reached 215 billion in 2025 at the base year level. Forward projections indicate sustained momentum, with the sector expected to grow at a compound annual rate of 8.2 percent through 2032, culminating in a market size approaching 345 billion. This growth is not merely a reflection of cyclical pricing but signals deeper shifts in how risk is transferred, managed, and financed across jurisdictions and asset classes. For executives and capital allocators, the numbers suggest a market that is both scaling and fragmenting in capability, creating pockets of premium returns alongside operational complexity.
Beneath the headline figures lies a market structure that remains moderately concentrated, with the top three players accounting for roughly 29 percent of total revenue and the top five holding just over 30 percent. This distribution indicates that while scale advantages persist, the market is not dominated by a handful of incumbents to the point of stifling innovation or new capacity entry. The relatively flat concentration curve between the third and fifth positions suggests competitive intensity among mid-tier and specialized carriers, particularly in non-life and life lines where pricing, underwriting discipline, and technological stack maturity diverge. The room between the leader cluster and the long tail of participants creates strategic space for platforms, service providers, and niche reinsurers that can differentiate on speed, data integration, or regulatory navigation.
Market Dynamics and Structural Challenges
Pricing Normalization Meets Risk Complexity
The post-2020 expansion reflects a market that has moved through several pricing cycles while absorbing growing exposure to climate-related losses, cyber accumulation, and demographic-driven longevity shifts. Rather than a single shock driving growth, the current phase is characterized by broad-based premium firming, improved loss recognition, and a recalibration of capital allocation toward lines with clearer risk-return profiles. This environment rewards reinsurers and brokers that can price risk with granularity and document assumptions transparently. At the same time, it raises the bar for underwriting rigor and actuarial validation, particularly where reinsured portfolios interact with complex asset structures or long-dated liabilities.
Regulatory Tightening as a Competitive Filter
A second defining challenge is the shifting regulatory architecture, which is reshaping how cedants and reinsurers prove solvency, adequacy, and collateral efficiency. In the United States, Actuarial Guideline 55, approved by the NAIC and effective from the end of 2025, requires cedants to incorporate reinsured business alongside net retained business in asset adequacy testing for statutory reserves. In Europe and comparable markets, solvency frameworks continue to mandate stringent capital equivalence, including 100 percent solvency capital requirement coverage and own-funds thresholds that support collateral-free transactions. These rules elevate the cost of compliance but also create differentiation opportunities for carriers and platforms that can operationalize asset adequacy documentation, investment accelerators, and principles-based bond definitions with minimal friction. The net effect is a market where regulatory fluency is becoming a commercial capability rather than a back-office necessity.
Talent, Automation, and the Cost of Expertise
A third pressure point is the intensifying demand for specialized actuarial and claims expertise. Updated guidelines such as AG 55, combined with tighter supervisory expectations for third-party cloud and AI deployments, increase the operational labor required to complete filings and maintain audit-ready documentation. Teams must interpret evolving asset adequacy standards, align investment matching adjustments, and demonstrate governance over automated reinsurance workflows. Where platforms and processes remain manual or fragmented, labor costs and cycle times expand, eroding margin and slowing decision velocity. Conversely, organizations that embed automation, standardized reporting, and embedded compliance into their reinsurance operations can convert this pressure into a durability advantage.
Key Growth Drivers
Digital Platforms and Automation of the Reinsurance Lifecycle
Technology is moving from experimentation to core infrastructure. Cloud-native reinsurance administration platforms are increasingly automating cessions, recoverables, commission calculations, and claims recovery across both traditional and non-proportional structures. Modular architectures allow insurers and brokers to integrate reinsurance operations with existing policy and finance systems without rip-and-replace disruptions. The emphasis is shifting from point solutions to end-to-end lifecycle coverage that spans contract initiation, ongoing administration, and retrocession management. As these platforms mature, they reduce reconciliation errors, accelerate settlements, and provide data lineage that supports regulatory exams and actuarial review. The recent wave of platform updates and launches underscores this direction, with new releases targeting automated cessions and recoverable tracking for property and casualty insurers and brokers, and sovereign-backed initiatives launching global reinsurance platforms anchored in financial free zones with institutional partners to facilitate cross-border operations.
Regulatory Modernization Enabling More Flexible Asset Deployment
Complementary regulatory changes are expanding the toolkit for matching long-tail liabilities with suitable assets. Principles-based bond definitions and investment accelerator mechanisms introduced in late 2025 are designed to facilitate more flexible asset deployment for matching adjustments within reinsurance portfolios. Alongside solvency frameworks that support collateral-free transactions when capital and own-funds thresholds are met, these developments allow market participants to optimize asset-liability alignment while preserving liquidity and governance standards. The practical implication is that reinsurers and cedants can structure transactions with greater latitude in asset selection and duration matching, provided they can evidence adequacy and maintain robust oversight. This flexibility is particularly valuable for life and annuity lines, where asset duration and crediting strategies interact directly with reinsured liabilities.
Demand-Side Shifts Toward Resilience and Capital Efficiency
On the demand side, primary insurers and corporate buyers are increasingly treating reinsurance as a strategic lever for balance-sheet resilience rather than a pure cost of risk transfer. Harder markets and elevated catastrophe volatility have reinforced the value of capacity certainty, tailored coverage, and transparent terms. At the same time, capital market participants and institutional allocators are exploring avenues to support reinsurance operations, especially in jurisdictions that offer regulatory clarity and operational efficiency. This convergence expands the ecosystem around reinsurance, creating demand for platforms and services that can coordinate ceded and assumed contracts, streamline reporting, and support multi-jurisdiction compliance. Brokers and intermediaries benefit as well, since structured automation reduces processing overhead and improves turnaround for complex placements.
Operational Cost Structures and the Value of Integrated Workflows
Cost structures are being reshaped by the interplay of technology adoption, labor scarcity, and supervisory expectations. As AI-assisted models gain traction in underwriting support, reserving, and claims triage, regulators are increasing governance, risk management, and third-party audit requirements for cloud providers and model operators. Organizations that standardize data, document model usage, and maintain audit trails can harness automation without compromising supervisory confidence. Where workflows remain siloed, the cumulative cost of manual reconciliation, rework, and compliance documentation compresses operating leverage. The emerging competitive logic is clear: integration of policy, finance, actuarial, and reinsurance administration into coherent workflows is becoming a determinant of margin and speed, especially as filing deadlines tighten and documentation expectations rise.
Competitive Landscape and Leading Strategies
The competitive field blends global reinsurers with technology and service providers, each pursuing distinct positions along the value chain. Incumbent carriers continue to anchor the market with broad risk appetite, diversified portfolios, and established distribution relationships. Their strategic emphasis typically centers on disciplined underwriting, integrated digital client tools, and robust risk-transfer and administration capabilities across life, non-life, and specialty lines. Many have built or acquired proprietary platforms and client portals to reduce friction in the placement and servicing of reinsurance contracts, reinforcing the perception of reliability and continuity that matters in long-tail and capital-intensive transactions.
Technology and software providers are carving a parallel track focused on the operational backbone of reinsurance. SaaS reinsurance administration platforms deliver modular automation for contract initiation, claims recovery, retrocession, and full lifecycle management for both traditional and non-proportional treaties. Other providers offer cloud or on-premise insurance suites that cover premiums, loss reserves, commission calculation, claims processing, and regulatory reporting for ceded and assumed contracts. These platforms increasingly target the pain points identified earlier—manual reconciliation, fragmented reporting, and audit readiness—while enabling interoperability with core policy and financial systems. The value proposition is not solely cost reduction; it is the creation of data continuity that supports solvency and asset adequacy documentation, accelerates settlements, and gives executives a clearer view of ceded exposures and recoverables.
The market is evolving through a combination of consolidation, specialization, and new entry. Scale incumbents compete on breadth and capital strength, while specialists compete on depth in particular lines or geographies. Newer entrants and platform operators compete on speed, configurability, and the ability to plug into existing ecosystems with limited disruption. Strategic differentiation is increasingly defined by three factors: the completeness of the reinsurance administration lifecycle covered, the strength of regulatory and actuarial documentation support, and the ability to operate across jurisdictions with consistent governance. As a result, partnerships between carriers, platforms, and institutional players are becoming more common, especially where an anchor in a well-regulated financial hub can streamline cross-border capacity and operations.
PW Consulting
For decision-makers evaluating partners and vendors, the practical question is not whether a provider offers a feature list, but whether its architecture reduces the cost of compliance, improves data lineage, and supports the lines and structures that matter to the organization. Providers that combine lifecycle automation with actuarial and claims support, or that can evidence alignment with asset adequacy and solvency expectations, are better positioned to capture share in a market where documentation and control are increasingly part of the commercial conversation.
Forward Outlook: Trends and Opportunities
Automation Becomes the Baseline, Not the Differentiator
Over the next three to five years, cloud-native reinsurance administration and integrated automation will move from competitive advantage to operational baseline. Organizations that standardize cessions, recoverables, commission flows, and claims recovery within connected workflows will reduce cycle times and improve the reliability of reporting used in both internal decision-making and external reviews. The commercial opportunity lies in extending these workflows to cover specialty and non-proportional structures, retrocession, and multi-currency settlements, where manual processing has historically introduced the most friction and error. Companies that achieve this baseline earlier will free managerial attention for pricing strategy, asset-liability optimization, and client service rather than administrative remediation.
Regulatory Fluency as a Commercial Capability
Regulatory and actuarial guideline evolution will continue to influence transaction structuring and platform design. Asset adequacy documentation, investment matching adjustments, and principles-based classification will require systems that can trace assumptions, evidence testing, and maintain auditability across ceded and retained portfolios. Firms that build or adopt tooling to operationalize these requirements will gain speed and credibility in filings, while those that rely on manual processes will face rising labor costs and execution risk around deadlines. The upside is not only compliance efficiency but also the ability to structure transactions with greater flexibility in asset deployment and collateral arrangements where supervisory frameworks permit, particularly in life and asset-intensive portfolios.
Market Structure Continues to Fragment in Capability, Consolidate in Ecosystems
While revenue concentration remains moderate, capability concentration will likely increase among providers that can span administration, analytics, and regulatory support within a coherent stack. Expect continued partnership activity between incumbents, platform operators, and institutional participants, especially where a regulated hub and aligned governance can reduce cross-border friction. At the same time, specialization will persist in lines with distinct underwriting, reserving, or asset dynamics, creating room for focused carriers and boutique platforms. The strategic implication is that the most resilient participants will be those that can combine clear risk appetite with interoperable technology, disciplined documentation, and the ability to scale operations without proportional increases in manual effort.
Risks and Uncertainties to Monitor
The outlook is constructive, but not without caveats. Catastrophe volatility and the accumulation of secondary perils can re-rate pricing and capacity quickly, pressuring returns and testing reserving discipline. Regulatory interpretation can shift as supervisors deepen scrutiny of AI-assisted models and third-party cloud dependencies, potentially increasing governance costs or constraining certain automation paths until standards settle. Talent constraints in actuarial and specialized claims roles may continue to elevate operational expenses where workflows are not sufficiently automated or standardized. Finally, macro and capital market dynamics can affect asset deployment strategies and the attractiveness of collateral-free structures, influencing transaction economics in life and non-life lines alike. Participants should therefore pair growth ambitions with scenario planning, data quality, and flexible operating models.
Strategic Implications for Decision-Makers
For Executives and Strategy Teams
Prioritize integration over point fixes. Decision velocity and margin protection increasingly depend on connected workflows that span policy, finance, actuarial, and reinsurance administration. Establish clear ownership of data lineage and documentation so that asset adequacy testing, solvency reporting, and recoverable tracking can be produced consistently and on time. Evaluate partners and platforms against their ability to cover the full lifecycle, support the lines and structures most relevant to the portfolio, and demonstrate governance aligned with supervisory expectations. Where feasible, sequence adoption to first reduce the highest-friction manual processes, then extend automation to specialty and non-proportional structures and multi-currency operations.
Worldwide Real Estate Insurance Market
For Investors and Capital Allocators
Assess exposure and resilience across the value chain rather than relying on headline market size alone. Differentiate between carriers with diversified, disciplined underwriting and those more exposed to concentrated catastrophe or cyber accumulation. In technology and service providers, focus on evidence of workflow completeness, customer retention, and the ability to reduce compliance and reconciliation costs, since these qualities translate into durable operating leverage as regulatory and documentation demands rise. Consider jurisdictional and partnership dynamics that can lower cross-border friction, while monitoring the regulatory trajectory for AI and cloud governance, which may affect cost structures and deployment options in the medium term.
For Procurement and Vendor Selection Teams
FrameRFP criteria around outcomes rather than feature counts. Define requirements for automated cessions, recoverable tracking, commission handling, claims support, and audit-ready reporting, and verify how each candidate maps to existing policy and financial systems. Require demonstrations of data lineage, documentation support for asset adequacy and solvency contexts, and clear migration or interoperability plans to avoid rip-and-replace risk. Weight vendor stability, roadmap coherence, and support for multi-jurisdiction operations where relevant, and build pilot metrics around cycle-time reduction, error reduction, and documentation completeness so that adoption decisions are anchored in measurable operational improvement.
The reinsurance market is scaling within a framework of rising expectations for speed, transparency, and regulatory discipline. Those that treat technology, data, and compliance fluency as core commercial capabilities will be better positioned to absorb complexity, protect margin, and access capacity where it is most valuable. For readers seeking a deeper segmentation of regional and line-level dynamics, detailed revenue paths across the forecast horizon, and tailored recommendations calibrated to specific portfolio structures, the full research report provides the granular data and scenario analysis needed to convert these strategic signals into concrete plans.
Insurance Market
For detailed analysis of this topic, please visit the official page: Reinsurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com