

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Snow Chain Market 2026: Beyond 5.35% CAGR, Unpacking $298M Growth Drivers

Strategic Trends and Commercial Opportunities in the Snow Chain Market: A 2025 Executive Briefing
The snow chain market is navigating a period of measured expansion, shaped by evolving winter preparedness requirements, shifting product preferences, and tightening performance expectations across regions. From 2020 through 2025, the industry built a steady growth trajectory, with 2025 standing as the latest confirmed baseline. Looking ahead through the forecast horizon to 2032, market momentum is projected to continue at a compound annual growth rate of 5.35%, translating into a measured but consistent uplift in total value over the period. Rather than signaling a sudden surge, this pace reflects a maturing market where incremental innovation, regulatory alignment, and demand-side habit changes are working in tandem. For decision-makers, the implication is clear: snow chains are no longer treated as a seasonal commodity alone, but as a regulated, performance-critical component of winter mobility ecosystems.
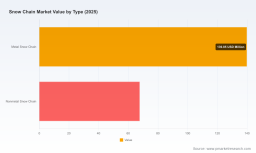
The broader market structure reflects a balanced mix of traditional and alternative traction solutions. Metal-based systems continue to command the largest share of attention, particularly where durability, load capacity, and repeated mechanical use are prioritized. Nonmetal alternatives, including textile traction devices, have carved out a meaningful position by emphasizing ease of handling, lower vehicle impact, and quick deployment. This dual-track product landscape matters because it mirrors a broader industry shift: buyers are increasingly weighing convenience and compliance alongside raw strength. At the same time, concentration remains comparatively moderate, with the top three players accounting for roughly a quarter of the market and the top five approaching just over a quarter. That fragmentation does not indicate weakness; instead, it points to a space where regional specialization, application expertise, and product positioning still create room for distinct competitive advantages.
Market Context and Core Structural Challenges
Despite the favorable growth outlook, the snow chain industry is not moving through calm waters. Executives evaluating participation, investment, or procurement strategies should pay close attention to a set of structural tensions that are reshaping how products are designed, sold, and deployed.
Polarized Demand Between Durability and Convenience
One of the persistent challenges in this market is the tension between long-established metal chain expectations and the growing appeal of lightweight, user-friendly traction alternatives. Metal chains remain the default in environments where repeated use, heavy loads, and harsh surface conditions are common. Their strength and familiarity make them the safe choice in many fleet, construction, and mountainous logistics settings. At the same time, textile and composite products are gaining credibility among passenger vehicle owners and lighter commercial users who value faster installation, reduced wear on road surfaces, and simpler storage. The challenge for manufacturers and distributors is not simply offering both categories, but aligning each with the right use case, performance claim, and pricing logic without blurring distinctions that matter to regulators and end users.
Regulation as Both Catalyst and Complexity
Winter traction requirements are undergoing visible updates in multiple jurisdictions, increasing the strategic importance of compliance-ready product portfolios. In several markets, authorities have refined expectations around when traction devices must be carried or fitted, and in some cases they have clarified preferred device types for specific conditions or vehicle classes. This is beneficial for the market as a whole because it strengthens the practical case for carrying chains or approved alternatives. Yet it also introduces complexity. Regulations can favor particular technologies in particular contexts, encourage faster product cycles, and raise the bar on documentation, testing, and quality assurance. Companies that treat compliance as an afterthought risk losing credibility with fleet buyers, dealer networks, and public-sector procurement teams.
Quality, Standards, and the Cost of Trust
A third challenge lies in the increasing expectation that traction products meet consistent international quality, safety, and environmental standards. Certified manufacturers are expected to demonstrate not only fit and function, but also controlled production practices and reliable performance under variable winter conditions. This raises the barrier for informal or loosely managed entrants and rewards players that have invested in disciplined manufacturing and testing. For the broader market, the upside is stronger buyer confidence and less price-only competition. The downside is that margins can be pressured when companies must absorb higher compliance, testing, and documentation costs while still competing in a fragmented landscape.
Key Drivers Reshaping the Snow Chain Market
The market’s trajectory is being pushed forward by several reinforcing forces. None of these drivers operates in isolation; together, they are redefining which products win, where growth concentrates, and how quickly new solutions can scale.
Technology and Product Design Innovation
Product innovation remains one of the most visible levers in the market. Easy-fit mechanisms, improved tensioning systems, more predictable fitment across tire sizes, and clearer integration with vehicle specifications are all helping reduce the friction historically associated with traction devices. In parallel, textile-based traction products have matured as practical alternatives in defined use cases, giving buyers a lighter, less intrusive option that can satisfy many everyday winter-driving needs. The strategic significance of this innovation is not limited to convenience. Better design lowers the barrier to proper use, which matters because a traction device only delivers value if it is deployed correctly and consistently. Companies that reduce installation time, improve fit confidence, and make storage and transport easier are indirectly strengthening compliance and safety outcomes.
A Regulatory Environment That Is Becoming More Explicit
Recent winter-equipment updates provide a clear example of how policy can shape demand. In France, mandatory winter equipment requirements for designated mountainous areas have been refreshed for the November 2025 to March 31, 2026 period, with metal snow chains or textile snow socks specified as acceptable options for light vehicles and vans. The same guidance also notes that metal chains are recommended over textile socks for frequent use in mountainous settings during that window. This distinction is strategically important because it signals that authorities are not treating all traction devices as interchangeable in every context. Meanwhile, in Colorado, a revised Passenger Vehicle Traction Law effective from fall 2025 requires chains or approved alternative devices for some 4WD/AWD vehicles without qualifying winter tires during severe storms. These changes reinforce a broader point: traction requirements are becoming more specific, more conditional, and more tied to real-time severity rather than generic seasonal memory. For manufacturers, that means product messaging must be precise, and portfolios must be flexible enough to address both baseline mandates and storm-triggered enforcement.
Changing User Behavior and Vehicle Mix
Demand-side behavior is shifting in ways that favor both safety and versatility. Across passenger and light commercial segments, users increasingly expect traction solutions that can be deployed without specialized effort, stored compactly, and trusted to work across a range of conditions. At the same time, vehicle fleets are not uniform; the proportion of all-wheel and four-wheel drive vehicles, varying tire sizes, and mixed light-commercial use patterns complicates one-size-fits-all product logic. Buyers are therefore looking for solutions that reduce uncertainty: clear fit guidance, application-specific recommendations, and devices that can be justified as a practical part of winter readiness rather than an emergency-only purchase. The business implication is that product leadership increasingly depends on the surrounding experience—guidance tools, compatibility clarity, and confidence in real-world performance—as much as on the chain itself.
Tire Protection Chains Market
Supply Chain Discipline and Cost Structure Pressures
Cost dynamics are also shaping strategy. Materials, production consistency, logistics, certification, and inventory planning all influence the final economics of traction products. Because snow chains are highly seasonal in many markets, inventory misalignment can create noticeable margin volatility. In addition, standards-aligned manufacturing and testing add structural cost but also create differentiation. Companies that can balance disciplined cost control with dependable quality are better positioned to serve both price-sensitive volume channels and performance-sensitive buyers. The supply chain challenge, then, is not simply to cut cost, but to manage a more complex value equation in which reliability, certification, and availability are all part of the price proposition.
Competitive Landscape and Leadership Strategies
The competitive field in this market is shaped by players with distinct regional strengths, product orientations, and customer interfaces. Rather than a single dominant template, the landscape shows several viable paths to relevance, each tied to a different interpretation of what buyers value most.
Differentiated Positioning Among Established Players
Several companies illustrate how strategic positioning can diverge even within the same category. Pewag Group has built a manufacturing footprint spanning Austria, the Czech Republic, and Pueblo, Colorado, supporting production for cars, SUVs, light trucks, heavy trucks, and utility vehicles. That broad vehicle coverage and multi-site production structure suggests an emphasis on scale, application breadth, and supply resilience across heavier-duty and utility segments. König, by contrast, has carved an identity around consumer-facing snow chains with patented easy-fit technologies and vehicle integration solutions. Its approach highlights the importance of usability and product design in the passenger and light-vehicle segments, where fit confidence and installation simplicity can be decisive purchase factors. RUD Group contributes a wider traction-device narrative, spanning snow chains, automatic traction chains, and off-road traction devices for passenger, truck, and industrial vehicles. That positioning gives the company a bridge between classic winter traction and more specialized mobility demands, which can be valuable in mixed-use and industrial contexts.
PW Consulting
Thule Group adds another angle by developing snow chains and traction devices with an emphasis on integration with vehicles and accessories, reflecting a broader mobility-and-safety ecosystem mindset. Peerless Chain Company reinforces the North American market with light truck, SUV, and passenger snow chains, including Auto-Trac automatic models and tire finder tools. The inclusion of fitment tools is notable because it lowers the friction of choosing the right device, an important commercial advantage in channels where compatibility questions often slow purchase decisions. Quality Chain Corp stands out as a major North American wholesaler and supplier for passenger cars, light trucks, and SUVs, underscoring the continued importance of distribution strength and channel reach in a market where availability during the winter window can be as important as product design. AutoSock Operations AS represents the textile traction segment, offering lightweight snow socks as an alternative traction device that meets recognized safety expectations. Its presence in the competitive landscape signals that alternative-material traction is now an established commercial category, not a niche curiosity.
How the Landscape Is Evolving
Several evolution patterns are worth watching. First, the market appears to be strengthening around players that can combine regional presence with product clarity. Companies that serve both consumers and professional buyers often need separate value propositions, because the criteria for purchase differ: everyday users prioritize ease and confidence, while fleets and commercial operators prioritize durability, compliance, and operational consistency. Second, the competitive field is likely to see continued specialization rather than only broad consolidation. The presence of strong wholesalers, integrated mobility brands, automatic-traction specialists, and textile-alternative producers indicates that customers are choosing among different solution philosophies. Third, new entrants or expanding players may gain ground by reducing friction in fitment, improving transparency around compatibility, or offering stronger warranty and support structures that make winter-readiness purchasing less risky. In a moderately concentrated market, differentiation can be achieved through experience, distribution, and application focus as much as through raw product novelty.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, the snow chain market is likely to be shaped by a small number of high-impact trends. Each carries both opportunity and risk, and the strategic value lies in identifying where a company’s capabilities can align with the direction of demand.
Traction Products as Part of a Compliance-Driven Readiness Model
Winter traction is increasingly treated as part of a broader readiness discipline rather than an optional accessory. As winter equipment expectations become more defined and more conditional, buyers in both consumer and commercial channels are likely to seek products that fit cleanly into compliance planning, fleet policies, and seasonal preparation routines. The commercial opportunity here is to build portfolios and support systems that make readiness easier to implement at scale. That can include clearer application guidance, stronger fitment tools, and product lines that map well to common regulatory scenarios. The risk is that generic or poorly positioned offerings may be squeezed out when buyers compare devices against explicit legal or policy requirements rather than convenience alone.
Continued Expansion of Alternative Traction Solutions in Defined Use Cases
Textile and other nonmetal traction alternatives are likely to continue gaining relevance in specific segments where ease of use, lower vehicle impact, and quick deployment are particularly valuable. The opportunity lies in matching these products to the right conditions and communicating their strengths without overstating their applicability. In mountainous or frequent-use contexts, the preference for metal chains in some guidance underscores the need for balanced portfolio strategy. Companies that can clearly differentiate where each technology fits—and why—will be better positioned to defend margin and customer trust. The risk is mis-positioning: if alternative traction products are sold into use cases where durability or abrasion resistance is the priority, satisfaction and reputation can erode quickly.
Standardization, Quality Assurance, and the Premium on Reliability
As expectations around quality, safety, and certification become more embedded across regions, reliability is likely to command a stronger premium. This favors manufacturers and distributors that can demonstrate consistent production, controlled quality systems, and credible performance claims. The commercial opportunity is to use quality assurance not only as a compliance expense, but as a market-facing differentiator that supports pricing, buyer confidence, and institutional sales. The uncertainty is that standards and enforcement expectations can continue to evolve, and companies that do not keep pace may face both commercial and reputational exposure.
Strategic Actions for Decision-Makers
For executives operating in or adjacent to this market, the most valuable next step is to convert high-level trends into concrete decisions about product mix, channel strategy, and compliance readiness.
Winter Tire Market
For Manufacturers and Product-Led Players
Build product architectures that separately address durability-critical, ease-of-use, and compliance-driven scenarios. A strong portfolio should make it obvious which device is intended for repeated mountain use, which is optimized for quick deployment, and which is best suited to a particular vehicle class or regulatory context. It is equally important to invest in fitment clarity and compatibility tools, because reducing selection friction can improve both conversion and proper use. Manufacturers should also treat certification and quality discipline as market-facing assets, not back-office requirements, especially when institutional buyers and larger fleets evaluate suppliers.
For Investors and Strategic Acquirers
Evaluate opportunities through the lens of channel strength, application coverage, and regional regulatory alignment rather than product category alone. A distributor with strong winter-window availability in key markets, a manufacturer with broad vehicle coverage, or a brand with a strong usability and integration story can each create defensible positions. Due diligence should pay close attention to seasonality risk, inventory planning, certification readiness, and the ability to serve both consumer and professional buyers without blurring the value proposition. Businesses that combine product credibility with dependable supply and clear positioning are likely to be more resilient than those competing primarily on price.
For Fleet Operators, Dealers, and Procurement Teams
Treat traction procurement as a readiness investment with compliance and safety implications, not merely a seasonal purchase. Selection should be informed by vehicle mix, likely operating conditions, and the specific requirements that apply in the regions where vehicles operate. Where conditions include frequent mountainous use or strict enforcement windows, it is prudent to match device type to the intended use pattern and to ensure that driver training, storage, and inspection practices support correct deployment. Procurement strategies that incorporate fitment tools, clear compatibility checks, and dependable seasonal availability can reduce operational risk more effectively than purchasing decisions based on lowest unit cost alone.
Closing Perspective
The snow chain market is entering a phase in which growth is steady, but the definition of winning is becoming more nuanced. Regulatory clarity, product innovation, application-specific demand, and quality expectations are all pushing the market toward more disciplined competition. The companies and buyers that benefit most will be those that treat traction devices as part of a broader winter-mobility strategy: the right device for the right condition, supported by clear guidance, reliable supply, and credible quality. For organizations seeking more granular segmentation, regional dynamics, and tailored strategic options, a closer look at the full research scope can help translate these market signals into precise action plans.
For detailed analysis of this topic, please visit the official page: Snow Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com