

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Chitosan Market Hits $19.15M in 2025, Set to Reach $67.66M by 2032 at 19.76% CAGR
By pmarketresearch, 2026-09-15
Navigating the Chitosan Revolution: Strategic Intelligence for 2026 and Beyond
The global chitosan market stands at a pivotal inflection point. What was once a niche biopolymer of interest primarily to academic researchers and specialized formulators has matured into a strategic commodity with cross-industry relevance. Over the past half decade, value creation has accelerated from below eight billion dollars in 2020 to nearly twenty billion dollars by 2025, reflecting a compound trajectory that places chitosan among the fastest expanding segments in the broader bio-based materials landscape. For corporate decision makers, procurement leaders, and innovation directors, this momentum is not merely a statistical curiosity. It signals shifting supply chains, evolving regulatory architectures, and the emergence of differentiated application platforms that will reward organizations equipped with precise, forward-looking intelligence.
This strategic briefing introduces our newly published Chitosan Market study, a comprehensive analytical resource designed to translate complex market dynamics into actionable decision frameworks for the 2026 planning cycle and beyond. Rather than offering static snapshots, the report constructs a living map of where value is concentrating, which application pipelines are transitioning from pilot to commercial scale, and how regulatory developments in key jurisdictions are rewriting the competitive calculus. By dissecting the structural forces that will shape the next seven years, this research empowers executives to allocate capital with greater precision, anticipate supply constraints before they materialize, and position product portfolios ahead of regulatory and consumer shifts.
The purpose of this overview is straightforward. We will outline the macro trajectory that frames the investment thesis, demystify the segmentation architecture that matters most to strategists, examine the competitive landscape through the lens of corporate positioning and recent strategic moves, and illustrate how regulatory tailwinds and raw material transitions are reshaping market access. Throughout, we maintain a deliberate focus on strategic implication over commodity data, reserving granular split-level figures for the full report. This approach ensures that decision makers encounter enough analytical depth to validate the rigor of our methodology while recognizing that precise, segment-level intelligence requires engagement with the complete publication.
The Growth Architecture: Translating Macro Momentum into Strategic Foresight
The expansion narrative underpinning the chitosan market is anchored in a sustained upward revenue curve that has outpaced many conventional biopolymer segments. Historical tracking from 2020 through 2025 reveals a market that has consistently compounded at rates reflecting both structural demand pull and incremental capacity deployment. By 2026, the top-line valuation is projected to clear the twenty-three billion dollar threshold, and the forecast horizon through 2032 points toward a market that will more than triple its current scale. A compound annual growth rate of 19.76 percent across the 2026 to 2032 window underscores a phase of accelerated commercialization rather than speculative hype.
For strategists, the critical takeaway is not the headline growth figure alone but what it implies about market maturation. At this velocity, demand is fragmenting across use cases with different risk profiles, regulatory exposures, and margin structures. Water treatment applications continue to anchor baseline procurement, while cosmetics and personal care formulations leverage chitosan's film-forming and bioactive credentials for premium positioning. Pharmaceutical and biomedical pathways are moving from controlled clinical exploration toward scaled manufacturing, and food and beverage sectors are testing clean-label and natural preservation synergies. This diversification means that aggregate growth obscures segment-level divergence in profitability, lead times, and supply chain resilience. The full report disentangles these dynamics, offering operational templates that differentiate between volume-driven commoditization and value-driven specialization.
Chitosan Market
The forecast period also invites scrutiny of inflection points that could compress or extend the growth trajectory. Capacity expansions, substitution risks from alternative biopolymers, and fluctuations in feedstock availability all feed into scenario planning. Our modeling framework integrates historical elasticity patterns with forward-looking supply logic, allowing decision makers to stress-test investment assumptions under multiple demand and cost environments. This is precisely the kind of structural insight that generic market summaries cannot provide, and it forms the analytical backbone of the complete study.
Segmentation as a Strategic Compass: Where Value Is Truly Concentrated
In high-growth biopolymer markets, segmentation is rarely a passive classification exercise. It is a diagnostic tool that reveals where margins are defended, where innovation is accelerating, and where competitive intensity is reshaping pricing power. The chitosan market divides across source origins, application domains, and geographic footprints, but the real strategic question is how these dimensions interact to create defensible positions for individual firms and categories.
Source dynamics illustrate this complexity. Traditional crustacean-derived pathways remain dominant, with shrimp-processing byproducts supplying a substantial share of the feedstock base and crab-derived streams adding differentiated grade characteristics. Yet the source mix is undergoing quiet but meaningful re-architecture. Insect-derived production, particularly through black soldier fly feedstock systems, is scaling as a sustainable alternative that decouples supply from marine capture volatility and appeals to organizations prioritizing traceability and circular sourcing narratives. The full report evaluates the cost curves, scalability constraints, and regulatory acceptability of these alternative pathways, enabling sourcing strategists to map resilience against conventional marine dependency.
On the application side, the distribution of demand reflects a market in transition. Environmental applications, particularly water treatment, continue to command meaningful volume, but higher-value segments are growing their share of strategic attention. Cosmetic formulators are embedding chitosan into skincare architectures that emphasize barrier support and natural derivation. Pharmaceutical and biomedical developers are exploring drug delivery matrices, wound care platforms, and targeted therapeutic carriers. Food and beverage innovators are experimenting with preservation, clarification, and clean-label functionality. Each application pathway carries distinct qualification requirements, supplier qualification timelines, and margin expectations. Rather than presenting static split-level percentages that flatten these nuances, the report provides functional roadmaps that connect grade specifications, regulatory status, and commercialization readiness for each application cluster.
Geographic dispersion further complicates segmentation. Regional markets differ not only in absolute scale but in regulatory posture, processing infrastructure, and end-user procurement culture. Some regions are anchored by mature industrial ecosystems with established export channels, while others are emerging as demand centers fueled by localized formulation capacity and domestic sourcing incentives. By mapping regional dynamics through the lens of entry barriers, logistics friction, and partner availability, the study equips expansion planners with a structured view of where near-term traction is most achievable and where longer lead times are probable.
Competitive Dynamics: Positioning, Differentiation, and the 2025-2026 Strategic Chessboard
No market advancing at this pace can be understood without a clear view of the firms actively shaping it. The chitosan competitive landscape is characterized by a blend of established specialty producers, regionally anchored manufacturers, and emerging innovators pushing grade specialization and sustainable sourcing narratives. Concentration metrics indicate that a relatively small cluster of leading participants commands a meaningful share of total market value, with the top three firms holding roughly 42 percent and the top five collectively approaching 48 percent. This structure suggests that while scale players exert pricing gravity, there remains substantial room for differentiation by grade purity, application expertise, and supply reliability.
Worldwide Chitosan for Water and Waste Treatment Market
Several organizations exemplify the strategic postures now defining the sector. Primex EHF operates at industrial scale with a focus on high-purity pharmaceutical, food, and agricultural grades derived from crustacean shells, positioning itself as a supply reliability partner across multi-sector demand. Heppe Medical Chitosan GmbH emphasizes customized purity and formulation support for cosmetic, pharmaceutical, and medical applications, illustrating how technical service can function as a moat in grade-sensitive markets. KitoZyme S.A. has built a reputation around high-molecular-weight fungal and crustacean-derived chitosan for biomedical and industrial use, while simultaneously expanding its portfolio toward clean-label and sustainability-oriented applications. Advanced Biopolymers AS leverages its NovaMatrix brand architecture across wound care, drug delivery, and food-related use cases, demonstrating the commercial value of brand association in functionally complex categories.
Regional scalability is another recurring theme. BIO21 Co., Ltd. reflects Asia-Pacific manufacturing depth serving agriculture, food, and pharmaceutical end markets, while T.C. Bio Corporation and Zhejiang Golden-Shell Pharmaceutical Co., Ltd. represent China-based production capacity that supports both pharmaceutical-grade and industrial-grade export channels. Taizhou City Fengrun Biochemical Co., Ltd. specializes in high-quality chitosan targeted at cosmetics, food, and agriculture, underscoring the ongoing segmentation of Chinese supply around grade credibility. In North America, ChitoLytic, Inc. and Tidal Vision highlight a growing domestic emphasis on medical, food, agricultural, and industrial grades, with Tidal Vision particularly active in bios stimulant and crop defense solutions. Entoplast introduces an alternative sourcing narrative through insect-derived chitin and chitosan, and Chitinor AS reinforces the appeal of Arctic-sourced pharmaceutical and food-grade material. These profiles are not merely company summaries; they are archetypes that reveal how firms are choosing to compete on scale, purity, sustainability, or application specificity.
Recent developments in 2025 and 2026 make these strategic choices especially visible. Tidal Vision advanced its regenerative agriculture agenda with the Canadian launch of chitosan-based seed treatment and bio-stimulant products, reinforcing a positioning at the intersection of crop performance and sustainable input substitution. Iterro Life Sciences introduced a commercially available chitosan formulation designed for inhaled drug delivery, a milestone that signals how biomedical applications can move from laboratory promise to market-access reality. KitoZyme expanded its clean-label and sustainable application range, aligning product architecture with consumer-facing sustainability expectations. Golden-Shell Pharmaceutical pursued distribution partnerships aimed at broadening availability in emerging markets, a move that illustrates how established producers are extending reach without necessarily building new manufacturing footprints. On the regulatory front, the USDA Agricultural Marketing Service advanced a May 2026 NOSB Subcommittee Proposal and Technical Report evaluating chitosan as a nonsynthetic substance for inclusion on the National List for organic crop production as a pesticide, with a full vote anticipated in spring 2026. Simultaneously, EFSA-related reviews have kept chitosan and chitosan hydrochloride under assessment as basic plant protection substances in the EU, with renewal pathways under ongoing evaluation. These developments are not peripheral noise. They are strategic signals that can alter demand timing, qualification requirements, and competitive access across multiple application segments.
Regulatory Tailwinds, Raw Material Realities, and Strategic Implications for 2026
Regulatory architecture is increasingly a determinant of market velocity rather than a compliance afterthought. In the chitosan space, the classification debates unfolding in North America and Europe carry direct consequences for application eligibility, labeling strategy, and the speed with which new use cases can scale. The possibility that chitosan could secure a nonsynthetic classification under organic crop production frameworks in the United States would materially broaden its addressable base among organic growers and input formulators seeking compliant alternatives to synthetic pesticides. The EU context, with its focus on basic substance approval and periodic review cycles, introduces a parallel layer of procedural complexity that can affect product development timelines and market entry sequencing. Our report maps these regulatory threads against application roadmaps so that teams can anticipate qualification steps, budget for approval lead times, and design portfolio strategies that are robust to procedural uncertainty.
Raw material dynamics are equally consequential. Because chitosan is predominantly extracted from marine shellfish exoskeletons as a byproduct of seafood processing, its supply logic is intertwined with crustacean aquaculture output and capture fisheries volumes. This linkage creates both opportunities and vulnerabilities. On one hand, integrated byproduct utilization can strengthen cost efficiency and circular sourcing narratives. On the other, feedstock availability can fluctuate with harvest cycles, processing throughput, and regional supply chain disruptions. The expanding role of insect-derived chitin and chitosan, enabled by black soldier fly feedstock processes, is reshaping the strategic conversation around supply diversification. For firms seeking to reduce exposure to marine feedstock variability or to meet stakeholder expectations around alternative sourcing, this pathway is moving from conceptual interest to commercially relevant option. The full report assesses the scalability, cost dynamics, and certification considerations that will determine how quickly these alternative streams can complement or substitute for traditional marine inputs.
Taken together, the regulatory and raw material environments point to a market where strategic advantage will accrue to organizations that integrate compliance foresight with supply chain architecture. Companies that treat these factors as separate workstreams risk missing the interaction effects that shape real-world commercialization. For example, a change in organic certification status can alter downstream demand timing; a shift in feedstock availability can affect grade consistency or pricing stability; a new regional approval can unlock a previously constrained application but only if the right grade purity and documentation are in place. The research study is built to connect these dots, translating qualitative developments into decision-relevant frameworks rather than leaving them as isolated news items.
What the Full Study Delivers: Operational Intelligence for Executive Decision Making
The complete Chitosan Market research is designed as an executable intelligence platform rather than a static market description. It brings together historical performance tracking, forecast modeling, segmentation logic, competitive profiling, and regulatory mapping in a structure that supports both strategic planning and operational execution. Readers will find detailed analysis of demand trajectories across application domains, source-related supply considerations, and regional market characteristics that matter for expansion, sourcing, and partnership decisions. The report also provides structured evaluations of leading companies, recent product launches, distribution and partnership activity, and regulatory developments that are actively reshaping market access.
Beyond aggregate narrative, the study is built to support scenario-based thinking. Decision makers can use its frameworks to assess how changes in feedstock availability, regulatory classification, or application adoption speed could recalibrate growth expectations and competitive positioning. The inclusion of concentration analysis, recent developments, and company-level profiles allows stakeholders to benchmark their own strategies against the prevailing modes of competition, whether those modes emphasize industrial scale, grade specialization, sustainability positioning, or application-specific formulation capability. For teams evaluating market entry, capacity investment, supplier qualification, or portfolio expansion, the report offers a structured reference point that reduces reliance on fragmented assumptions.
Mapping the Road Ahead: Why This Research Matters for 2026 Strategy
The chitosan market is entering a phase where growth is increasingly tied to application credibility, regulatory alignment, and supply chain differentiation rather than to broad category momentum alone. That shift favors organizations that can read the market not just as a revenue curve but as a system of interacting demand drivers, sourcing constraints, compliance pathways, and competitive maneuvers. The compound trajectory projected through 2032 suggests opportunity, but sustained advantage will depend on the quality of strategic interpretation applied to that opportunity.
This strategic briefing has outlined the macro direction, the segmentation logic that matters, the competitive archetypes now in play, and the regulatory and raw material developments that will influence market access in the near term. It has also signaled the depth of operational content available in the full study, from forecast modeling to company-level positioning analysis and application-specific commercialization roadmaps. For executives preparing for 2026 and beyond, the central question is not whether chitosan represents a growing market, but how to engage with it in a way that aligns sourcing, product strategy, regulatory posture, and partnership choices with where value is genuinely concentrating. The complete report is designed to answer that question with the precision required for investment-grade decision making.
To access the full segmentation detail, competitive profiling, forecast scenarios, and regulatory mapping that support these strategic conclusions, we invite you to explore the complete Chitosan Market research on our platform. The publication provides the granular intelligence, functional roadmaps, and decision frameworks that turn high-level market momentum into concrete action plans.
For detailed analysis of this topic, please visit the official page: Chitosan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Thermal Barrier Coatings Market: Strategic Intelligence for 2026 and Beyond
The global industrial landscape is undergoing a profound transformation driven by the dual imperatives of energy efficiency and emissions reduction. At the heart of this shift lies the Thermal Barrier Coatings (TBC) market, a critical enabler for high-temperature applications across aerospace, power generation, and industrial sectors. As organizations prepare their strategic roadmaps for 2026 and the ensuing forecast period through 2032, understanding the nuanced dynamics of this market is no longer optional—it is a prerequisite for sustainable growth and competitive advantage.
Our latest comprehensive market research report on the Thermal Barrier Coatings industry offers a deep dive into the operational, financial, and technological currents shaping this sector. This article serves as an executive preview, highlighting the strategic value of the analysis and the critical decision-making frameworks contained within the full document.
Market Trajectory and Macro-Economic Context
The Thermal Barrier Coatings market has demonstrated resilient growth over the past half-decade, recovering from historical fluctuations to establish a robust upward trajectory. Based on extensive data aggregation and analysis, the market generated substantial revenue in the base year of 2025, building upon a consistent compound annual growth rate observed from the historical period of 2020 to 2025.
Looking forward, the forecast period spanning 2026 to 2032 projects a steady expansion. Our analysis indicates a forecasted CAGR of 5.1 percent over this horizon. This growth is not merely a function of volume but is deeply tied to the technological intensification of key end-use industries. The market valuation is expected to reach significant milestones by 2032, reflecting the cumulative impact of regulatory pressures, material innovation, and capital expenditure in high-temperature engineering sectors.
Investors and strategic planners must recognize that this growth curve is not linear. It is punctuated by shifts in raw material procurement, geopolitical influences on supply chains, and the pacing of regulatory implementation. Our report dissects these variables to provide a clear view of potential headwinds and tailwinds that will define market performance in the coming years.
Regulatory and Environmental Drivers
One of the most potent forces accelerating the adoption of thermal barrier coatings is the tightening regulatory environment surrounding emissions and energy efficiency. Governments worldwide are introducing increasingly stringent emission norms for engines and industrial combustion systems. These regulations are not isolated policies but part of a broader global commitment to reduce greenhouse gas emissions.
In this context, TBCs play a pivotal role. By enabling higher operating temperatures and improved thermal efficiency, these coatings allow combustion systems to burn fuel more efficiently while reducing harmful output. Our research highlights that the implementation of regulations aimed at decarbonization is likely to propel demand significantly. Furthermore, sector analysis indicates that governments are allocating substantial portions of industrial budgets toward energy efficiency improvements, directly supporting the infrastructure required for TBC adoption.
However, the regulatory landscape is a double-edged sword. While performance standards drive demand, environmental regulations regarding manufacturing processes pose challenges. The production of some thermal barrier coatings involves hazardous waste that requires safe disposal, adding compliance costs and operational complexity for manufacturers. Our report provides a balanced assessment of how leading firms are navigating these compliance hurdles while capitalizing on the demand side of the regulatory equation.
Competitive Landscape and Consolidation
The Thermal Barrier Coatings market is characterized by a moderately concentrated competitive structure. Analysis of market concentration reveals that a small group of key players holds a significant share of the revenue, underscoring the high barriers to entry associated with specialized coating technologies and certified supply chains. This concentration suggests that strategic partnerships, vertical integration, and technological moats are critical strategies for maintaining market position.
Thermal Barrier Coatings (TBC) Market
The ecosystem comprises a mix of global surface technology providers, specialized powder manufacturers, and regional service applicators. Leading entities such as Praxair Surface Technologies and Oerlikon Metco dominate significant portions of the value chain, offering vertical integration from specialty powders to thermal spray coating services. Their capabilities in aerospace and gas turbine applications set the benchmark for quality and performance. Similarly, organizations like Bodycote plc and Honeywell International Inc. leverage extensive facility networks and integrated powder production to serve diverse industrial needs.
Regional players and niche service providers also play a vital role, particularly in maintenance, repair, and overhaul (MRO) segments. Companies like Chromalloy Gas Turbine LLC and Sulzer Ltd. focus on specific application verticals such as aero engine MRO and civil engine services, utilizing advanced techniques like APS and HVOF. Meanwhile, material suppliers such as H.C. Starck provide the foundational high-purity ceramic powders essential for coating performance.
Recent industry developments underscore the trend toward digitalization and collaboration. For instance, recent partnerships have focused on integrating smart factory technologies and digital processes to enhance TBC production efficiency. These moves signal a shift where data analytics and IoT-enabled performance models are becoming as valuable as the physical coatings themselves. Our report details these competitive maneuvers, offering insights into how firms are differentiating themselves in a crowded marketplace.
Segmentation Insights and Strategic Focus
Understanding where value is created is essential for resource allocation. The market is broadly segmented by type and application, each with distinct growth drivers and cost structures. Ceramic-based solutions continue to hold a predominant position due to their superior thermal properties, particularly in high-stress environments like gas turbines. Metallic coatings and other types serve specific niche requirements where ductility or specific thermal expansion matches are prioritized.
In terms of application, the aerospace sector remains a primary revenue driver, fueled by the need for engine durability and fuel efficiency in both commercial and military aviation. Power generation and automotive sectors also contribute significantly, driven by the push for cleaner combustion and waste heat recovery systems. However, the dynamics vary by region, with mature economies focusing on retrofitting and MRO, while emerging markets may see growth in new capacity installation.
The full report provides a granular breakdown of these segments, analyzing volume trends, pricing dynamics, and the specific technological preferences within each category. This level of detail is crucial for companies deciding whether to expand their product portfolio, target new verticals, or consolidate their presence in core markets.
Challenges and Risk Factors
Despite the positive outlook, the path forward is not without obstacles. High procurement costs associated with thermal barrier coatings remain a significant constraint. The reliance on advanced ceramic compounds and mixed metal alloys means that raw material price volatility can directly impact margins and project feasibility. Our analysis examines how supply chain resilience and material science innovations are being deployed to mitigate these cost pressures.
Additionally, the technical complexity of application processes requires specialized expertise and certified facilities. Ensuring consistent coating quality and adhesion across large-scale industrial components demands rigorous quality control. Firms that fail to maintain certification standards or invest in workforce training risk losing contracts to more capable competitors.
The full intelligence package within our report quantifies these risks and offers mitigation strategies, allowing leadership teams to stress-test their strategies against potential market shocks.
Worldwide Long-lasting Thermal Insulation and Cooling Coating Market
Conclusion: The Value of Comprehensive Intelligence
In a market defined by technical complexity and regulatory flux, informed decision-making is the ultimate competitive differentiator. The Thermal Barrier Coatings Market report is designed to equip stakeholders with the actionable intelligence needed to navigate this landscape. From macro-economic forecasts to micro-level competitive profiling, every section is crafted to support strategic planning for 2026 and beyond.
We invite industry leaders, investors, and policy makers to delve deeper into the findings. The complete analysis offers the specific data points, regional breakdowns, and proprietary insights necessary to capitalize on the opportunities within this evolving sector. Accessing the full report will provide the clarity needed to turn market dynamics into strategic advantage.
For detailed analysis of this topic, please visit the official page: Thermal Barrier Coatings (TBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wedding Dress Market Hits $186M in 2025, Projected 6.08% CAGR Through 2032
By pmarketresearch, 2026-09-15
Executive Overview: Strategic Imperatives in the Global Wedding Dress Market
The wedding dress market stands at a pivotal juncture in 2026. As consumer preferences shift towards personalization, sustainability, and experiential value, industry stakeholders must navigate a landscape defined by both resilient growth and intensifying competition. This comprehensive market research publication by PW Consulting offers a granular examination of the sector, designed to equip executives, investors, and strategic planners with the intelligence necessary to capitalize on emerging opportunities. The insights presented herein are not merely statistical aggregates; they represent a roadmap for navigating the complexities of supply chain dynamics, regional demand fluctuations, and competitive differentiation in the coming years.
Our analysis covers the historical trajectory from 2020 through 2025, providing a robust baseline against which future projections are measured. The forecast period extends to 2032, allowing for long-term strategic planning. A central finding of this study is the projected Compound Annual Growth Rate (CAGR) of 6.08% during the forecast period. This indicates a sustained upward momentum, suggesting that the market is not only recovering from previous global disruptions but is also expanding beyond pre-pandemic benchmarks. The total market revenue is anticipated to reach significant milestones, surpassing the 280 million USD mark by the end of the forecast horizon, up from a base year value of 186.0 million USD in 2025. Such growth underscores the enduring cultural and economic significance of bridal wear, despite shifting demographics and economic pressures in various regions.
Market Trajectory and Growth Drivers
Understanding the velocity of market expansion is critical for capacity planning and investment allocation. The data indicates a consistent year-over-year increase in revenue, reflecting a market that is maturing yet still ripe for innovation. From a historical perspective, the sector demonstrated remarkable resilience, growing from 120.0 million USD in 2020 to 164.65 million USD by 2024. This recovery phase was characterized by a return to traditional ceremonies and a renewed appetite for conspicuous consumption in the bridal sector. As we move into 2026, the market size is projected to approximate 200.02 million USD, signaling a stabilization at higher valuation tiers.
Wedding Ring Market
The drivers behind this growth are multifaceted. Demographic shifts in key aging populations are being counterbalanced by rising marriage rates in emerging economies. Furthermore, the psychological shift towards "once-in-a-lifetime" spending, even amidst inflationary environments, supports the premiumization trend observed in recent quarters. However, growth is not uniform across all vectors. The industry is witnessing a bifurcation where mass-market availability competes with high-end bespoke services. Stakeholders must understand where their value proposition lies within this spectrum to optimize margin profiles. Our report delves into the specific catalysts fueling this expansion, including the rise of destination weddings, the influence of digitalmarketing on bridal retail, and the evolving lifecycle of wedding-related expenditures.
Structural Segmentation and Consumer Behavior
The architecture of the wedding dress market is defined by distinct segmentation channels that dictate go-to-market strategies. The report provides a detailed breakdown of the market by type, application, and region, offering clarity on where demand is concentrate d and how consumer behaviors diverge.
In terms of product type, the market is primarily split between off-the-rack solutions and customized offerings. While standardized inventory provides speed and accessibility, the customized segment represents a high-value opportunity for brands capable of delivering exclusivity. The data suggests a healthy equilibrium between these two streams, with each serving different consumer psychographics. Off-the-rack purchases appeal to cost-conscious and time-sensitive buyers, while customized gowns cater to those seeking unique design elements and a tailored fit. Understanding the margin implications and inventory risks associated with each type is essential for operational efficiency.
The application landscape further nuances this picture. Personal purchases remain the dominant force, driven by the bride's direct investment in her ceremony attire. However, the rental market constitutes a significant portion of revenue, reflecting a growing consciousness around sustainability and cost efficiency. Additionally, photographic studios represent a niche but steady demand channel, where dresses are purchased or rented specifically for imagery rather than ceremony use. Our analysis explores the elasticity of demand across these applications, helping businesses identify which customer segments offer the highest lifetime value and lowest churn risk.
Regional Dynamics and Global Supply Chains
Geography plays a decisive role in market performance. The report maps revenue distribution across major global regions, highlighting the disparities in market maturity and growth potential. North America continues to represent a substantial portion of global revenue, underpinned by a robust culture of elaborate wedding ceremonies and high disposable income levels. Europe follows as a mature market with strong historical ties to bridal fashion, characterized by a preference for luxury and heritage brands.
Wedding Dress Market
The Asia Pacific region presents a compelling growth story, driven by rising middle-class populations and the adoption of Western wedding traditions alongside local customs. Latin America and the Middle East and Africa regions, while currently smaller in total volume, offer high growth potential as economic conditions stabilize and the wedding industry professionalizes. For manufacturers and retailers, understanding these regional nuances is vital. Logistics costs, tariff structures, and local consumer preferences vary significantly. A strategy that works in North America may not translate directly to Eastern Europe or Southeast Asia. Our geographic analysis provides the context needed to tailor distribution networks and marketing messages to local realities without needing to rely on generic global assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment in the wedding dress market is fragmented yet features strong brand identities. Our research profiles a diverse array of key companies that define the current industry standards. These entities range from boutique American designers focusing on specific aesthetic niches to large-scale manufacturers based in Europe and Asia optimized for volume and wholesale distribution.
In the United States, the market is characterized by a strong presence of designer brands that emphasize American design and manufacturing. Companies such as Alyssa Kristin and Katherine Tash highlight the value proposition of domestic production, appealing to consumers who prioritize supply chain transparency and quality control. Similarly, brands like Anne Barge and Sareh Nouri focus on luxury bridal gowns, often produced in-house to maintain strict quality standards and design exclusivity. The high-end segment is further populated by established names like Vera Wang Bride and Morilee New York, which leverage iconic status to command premium pricing. Contemporary options are also well-represented by players like Justin Alexander and CINQ, who target the mid-to-high-end market with modern designs that resonate with younger demographics.
The competitive field extends beyond domestic boundaries. In Europe, Poland-based Pollardi Fashion Group stands out as one of the largest factories for wedding and evening dresses, indicating a strong manufacturing backbone in the region. Italy's Ricca Sposa maintains a position as a luxury bridal brand with significant wholesale presence, recently reinforcing its market visibility through participation in major industry events such as Barcelona Bridal Fashion Week in April 2026. In Asia, manufacturers like TEG (TEG Made) in China and Suzhou Leader Apparel Co., Ltd. provide premium bridalwear manufacturing services, catering to both branded labels and private label opportunities. Turkish manufacturer Metropol Wedding Dress and Chinese wholesaler BETANCY further illustrate the global supply chain's reliance on specialized manufacturing hubs capable of handling custom and wholesale volumes efficiently.
Recent developments highlight the proactive nature of these competitors. In 2026, several key players have intensified their presence at major trade shows and fashion weeks. Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, signaling a continued commitment to seasonal innovation. Allure Bridals held designer events including Once Upon a Dress in May 2026, reinforcing its brand engagement strategy. These activities are not merely promotional; they are strategic moves to secure buyer relationships and dictate trend directions. Our report analyzes how these competitive tactics influence market share and brand equity, providing a framework for assessing rival strategies.
Industry Context and Recent Developments
The operational context of the wedding dress market in 2026 is shaped by a combination of supply chain recalibration and consumer sentiment shifts. The industry is moving towards greater transparency and sustainability, a trend reflected in the product offerings of brands like LEIN, which focuses on sustainable and modern wedding dresses. This shift is not superficial; it impacts material sourcing, production timelines, and end-of-life considerations for garments. Companies that fail to adapt to these ethical expectations risk alienation from a growing segment of conscientious consumers.
Furthermore, the frequency of industry gatherings and collection launches remains high. The participation of companies like Ricca Sposa and Kaya Wedding in European and Barcelona bridal events during April 2026 underscores the importance of physical presence in building B2B and B2C relationships. These events serve as bellwethers for upcoming trends and color palettes. For market entrants or existing players looking to pivot, monitoring these calendars is essential. The data compiled in this study includes timelines of such key events and product launches, allowing strategists to align their own release cycles with market peaks.
Strategic Value of This Research
Access to granular data is the differentiator between reactive management and proactive strategy. This report is structured to provide actionable intelligence rather than abstract observations. It empowers stakeholders to identify white space opportunities, assess competitor vulnerabilities, and optimize pricing strategies. By integrating historical data with forward-looking projections, the document serves as a foundational tool for budgeting, hiring, and expansion planning.
The depth of segmentation analysis allows for precise targeting. Whether a company is looking to expand its rental inventory, invest in customized manufacturing capabilities, or enter a new geographic region, the data supports evidence-based decision-making. The competitive profiling extends beyond basic company descriptions to include an assessment of their offerings and recent strategic moves, enabling a clearer picture of the battlefield. Understanding the concentration of market power, reflected in the competitive metrics, helps in gauging the barrier to entry and the potential for consolidation.
Conclusion and Next Steps
The wedding dress market in 2026 offers a complex array of opportunities for those equipped with the right intelligence. Growth is sustained, but the path to capturing value requires a nuanced understanding of segmentation, regional dynamics, and competitive behavior. PW Consulting's detailed market research provides the comprehensive view necessary to navigate this environment successfully.
For executives and strategists who require the full depth of this analysis, including detailed segmentation splits, specific regional revenue figures, and exhaustive competitor matrices, we invite you to access the complete report. The executive summary provided here illustrates the scope and strategic relevance of the findings, but the full document contains the specific data points required to finalize investment cases and operational plans. Engage with the full dataset to transform industry insights into tangible business outcomes.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Electric Scooters Market Hits $38.23B in 2025, Forecasts 9.81% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Horizons for the Electric Scooter Market: Navigating Growth Through 2032
The urban mobility landscape is undergoing a seismic shift, driven by the dual imperatives of decarbonization and last-mile efficiency. Electric scooters, once viewed as niche recreational devices, have matured into integral components of the global transportation ecosystem. For stakeholders operating within this dynamic sector, understanding the trajectory of market expansion is not merely an exercise in forecasting it is a prerequisite for strategic positioning. Our latest comprehensive market research on the Electric Scooter Market offers a granular examination of the forces shaping industry outcomes from 2026 through 2032, providing executives, investors, and policymakers with the intelligence needed to navigate an increasingly complex competitive environment.
Electric Scooters Market
This analysis is built upon a rigorous evaluation of historical performance spanning 2020 to 2025, extending forward through a seven-year forecast period. The data reveals a market characterized by robust structural momentum, with a compound annual growth rate of 9.81 percent projected across the evaluation window. This sustained upward trajectory reflects deepening consumer adoption, expanding commercial deployment, and the convergence of supportive regulatory frameworks with technological maturation. Yet beneath these headline figures lies a far more intricate reality, one defined by regional asymmetries, product segmentation shifts, and intensifying competitive pressures that demand nuanced strategic responses.
Market Trajectory and Core Dynamics
The electric scooter sector has demonstrated remarkable resilience and expansion potential over the past half-decade. Revenue valuations have progressed from a baseline of 24.32 billion USD in 2020, climbing through successive growth phases to reach 38.23 billion USD by 2025. This historical arc establishes a credible foundation for near-term projections, with valuations anticipated to breach 41.58 billion USD in 2026 and continue their ascent toward 73.5 billion USD by 2032. Such growth is neither accidental nor uniform. It emerges from the interplay of urbanization pressures, infrastructural investments, evolving consumer preferences, and the strategic maneuvering of manufacturers seeking to capture share within an increasingly crowded arena.
Several macro force are propelling this expansion. Urban congestion in megacities has accelerated demand for compact, zero-emission alternatives to traditional motorized transport. Municipalities worldwide are integrating micromobility into broader transit networks, recognizing the role that electric scooters play in bridging gaps between mass transit hubs and final destinations. Simultaneously, advancements in battery chemistry, motor efficiency, and connected vehicle technologies have elevated product reliability and user experience, addressing earlier adoption barriers related to range anxiety and maintenance complexity.
However, growth is not without friction. Regulatory interventions have introduced new layers of complexity for market participants. Trade policy adjustments, including the imposition of significant tariffs on electric scooters imported from China, have reshaped supply chain considerations and prompted manufacturers to reevaluate sourcing strategies and regional production footprints. Concurrently, evolving standards governing lithium-ion battery transport, storage, and recycling impose compliance obligations that influence product design, logistics, and total cost structures. These dynamics underscore the necessity of proactive regulatory intelligence as a core competency for organizations operating in this space.
Segmentation Architectures and Demand Drivers
A superficial glance at aggregate market figures obscures the divergent growth patterns unfolding across product categories, end-use verticals, and geographic corridors. Understanding these sub-market dynamics is essential for allocating capital efficiently, tailoring product roadmaps, and identifying white-space opportunities that remain underserved by current competitive offerings.
Product architecture continues to bifurcate between foldable and non-foldable designs, each addressing distinct user requirements and deployment contexts. Foldable configurations prioritize portability and multi-modal integration, appealing to commuters who combine scooter usage with public transit. Non-foldable variants, by contrast, emphasize structural robustness, payload capacity, and extended range, catering to applications where stability and durability outweigh portability concerns. The relative performance of these segments reflects broader shifts in consumer lifestyle patterns and commercial fleet requirements, with implications for manufacturing specialization and inventory strategy.
Application-wise, the market divides between personal use and commercial deployment, each following distinct adoption curves and value propositions. Personal use remains anchored in consumer preference for convenient, low-cost, environmentally conscious mobility solutions. Commercial applications, spanning last-mile delivery fleets, shared micromobility programs operated by municipal authorities or private operators, and corporate campus transportation, introduce additional dimensions of scale, utilization efficiency, and total cost of ownership. The interplay between these application verticals shapes demand volatility, pricing architecture, and the extent to which manufacturers can pursue differentiated value chains.
Geographically, market performance varies substantially, reflecting differences in urban density, regulatory environments, infrastructure maturity, and cultural acceptance of micromobility. Certain regions exhibit accelerated penetration rates driven by aggressive public-sector support and dense urban form, while others progress more incrementally as infrastructure catch-up and consumer education remain ongoing processes. These spatial divergences create heterogeneous opportunity landscapes, requiring market entrants and incumbents alike to calibrate their regional strategies with precision rather than relying on one-size-fits-all expansion models.
Competitive Landscape: Navigating an Increasingly Crowded Field
The electric scooter market is defined by a concentration of established players alongside a steady influx of new entrants, each leveraging distinct technological capabilities, brand positioning, and operational models to capture share. Our research maps this competitive terrain in detail, examining the strategic postures of leading manufacturers and shared mobility operators whose actions collectively shape market direction.
Among the prominent hardware manufacturers, several Chinese-based companies have built formidable portfolios emphasizing range, connectivity, and performance versatility. Segway-Ninebot continues to expand its E-series and Max series offerings, with recent product introductions at CES 2026 highlighting updated battery technologies and cross-platform integration between e-bikes and e-scooters. NIU International has reinforced its position through the KQi series and lightweight variants that blend integrated connectivity with extended range options tailored for urban environments. Yadea Technology Group broadens its footprint by spanning electric two-wheeler scooters and motorcycles, leveraging advanced battery and motor systems that serve both personal and commercial end markets. Kaabo has carved a niche in the heavy-duty off-road segment, deploying high-capacity batteries and high-output motors that appeal to enthusiasts and specialized commercial users alike.
The Indian market has emerged as a particularly dynamic theater of innovation and scale. TVS Motor Company has continued to refine its Orbiter and Star Series e-scooters, with the 2026 release of the TVS X model introducing ABS options and updated powertrain configurations aimed at mainstream commuting segments. Ather Energy has pursued a differentiated strategy centered on AI-optimized performance, swappable battery architectures, and telematics integration, positioning its Rizta and 450X models as technology-forward solutions for urban and last-mile transport. Ola Electric has scaled rapidly with its S1 Pro and S1 X scooters, emphasizing high-efficiency motors and fast-charging infrastructure designed to support both personal ownership and fleet applications. These Indian players benefit from a confluence of domestic demand, manufacturing scale, and aggressive product iteration that collectively intensifies competitive pressure across the broader market.
In North America, a diverse set of manufacturers and operators addresses varying consumer and institutional requirements. Apollo Scooters and Gotrax serve commuter segments with solid-tire designs, extended battery life, and foldable configurations that balance affordability with reliability. Navee and VMAX have targeted higher-performance use cases, emphasizing 48V systems, hub-motor configurations, and range specifications that support daily transport and off-road capabilities. InMotion focuses on rugged terrain and payload capacity through high-peak-power models. LexGo has introduced dual-motor options that extend range and performance envelopes for urban and highway commuting contexts. These regional players operate within a regulatory environment shaped by evolving customs policies and battery transport standards, making supply chain agility and compliance readiness critical differentiators.
The shared mobility segment introduces an additional competitive dimension, with operators such as Lime, Bird, Spin, Veo, and Gogoro deploying dockless or fleet-based models tailored to citywide micromobility programs and municipal partnerships. These companies emphasize utilization efficiency, battery-swapping ecosystems, and customized fleet solutions that align with urban transportation authority requirements. Their competitive calculus differs from hardware manufacturers, prioritizing operational economics, regulatory relationships, and user acquisition over unit sales volume.
Market concentration data indicates that a relatively small number of firms command a substantial share of aggregate revenue, with CR3 and CR5 metrics reflecting meaningful consolidation at the top of the competitive pyramid. This concentration does not eliminate opportunities for specialized entrants, particularly those that can differentiate through technology, regional focus, or niche application expertise, but it does raise the stakes for market participants seeking to achieve scale and defend margins.
Regulatory and Supply-Side Currents
Strategic decision-making in the electric scooter market must account for a broad array of externalities that influence costs, product design, market access, and competitive dynamics. Regulatory frameworks are evolving rapidly across jurisdictions, and the implications extend far beyond compliance checklists.
Trade policy has emerged as a particularly salient factor. Recent tariff measures imposed on electric scooters imported from China, coupled with duties on lithium-ion battery components, have compelled manufacturers and distributors to reassess sourcing strategies, pricing architecture, and regional assembly considerations. Organizations that have developed flexible supply chain models, localized production capabilities, or diversified sourcing portfolios are better positioned to absorb policy-driven cost pressures while maintaining competitive pricing.
Battery-related regulations introduce additional complexity. Updated guidance on lithium battery marking, watt-hour rating requirements, and quantity limits for batteries packed with equipment impose new documentation and packaging obligations that influence logistics, warehousing, and cross-border movement. In parallel, recycling mandates in certain jurisdictions require elevated material recovery rates for battery components used in shared fleets, affecting total lifecycle costs and incentivizing investments in closed-loop material management.
Raw material dynamics further complicate the supply-side picture. Surging export volumes and values for lithium batteries reflect robust global demand for energy storage and electrified mobility, but they also introduce volatility considerations related to commodity pricing, capacity allocation, and geopolitical factors. Manufacturers that have secured long-term supply agreements, invested in battery technology differentiation, or developed partnerships with experienced component suppliers gain relative advantage in navigating these fluctuations.
Trip data collection and urban mobility monitoring efforts by transportation authorities provide increasingly granular visibility into usage patterns, trip lengths, and modal substitution effects. Access to such data, whether through public reporting or proprietary partnerships, enables operators and manufacturers to refine product specifications, optimize fleet deployment, and tailor marketing strategies to evidence-based usage insights rather than assumption-driven planning.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
This market research report is designed to translate complex market signals into structured, actionable intelligence. Beyond high-level sizing and growth projections, the analysis provides a detailed operational framework that supports strategic planning across multiple functional domains.
The report examines historical performance and forward-looking forecasts across the full evaluation period, grounding projections in transparent methodology while identifying inflection points, risk factors, and catalyst events that could alter trajectory. Segmentation analysis disaggregates demand by product architecture and application vertical, revealing where growth is accelerating, where saturation may emerge, and where unmet needs create openings for informed market entry. Geographic analysis maps regional performance differentials without reducing them to simplistic rankings, instead exploring the structural drivers that underpin divergent outcomes and the strategic implications for market access, partnership selection, and capacity deployment.
Hoverboard Scooters Market
Competitive profiling extends beyond descriptive summaries to assess strategic positioning, product portfolio coherence, recent launch activity, and the manner in which leading firms are responding to regulatory and supply-side pressures. Recent developments, including product introductions at major trade exhibitions, model refreshes targeting specific performance or range thresholds, and the expansion of model lineups by emerging brands, are contextualized within broader competitive dynamics to illustrate how incumbents and challengers are contesting market share.
Regulatory and supply-chain analysis is integrated throughout rather than treated as a standalone appendix, ensuring that decision-makers understand how policy developments, battery standards, recycling mandates, and trade measures interact with pricing, product design, and market entry timing. This integrated approach enables organizations to evaluate not only what the market is likely to do, but also where constraints and enablers will shape the feasible set of strategic choices.
For corporate strategists, the research supports scenarios around capacity investment, product portfolio optimization, and geographic prioritization. For investors, it provides a framework for assessing market attractiveness, competitive durability, and the risk-adjusted return profiles associated with different segments and regions. For policy-oriented readers, it illuminates the relationship between regulatory design, infrastructure development, and market outcomes, offering evidence that can inform program design and stakeholder coordination.
Conclusion: Prioritizing Precision in a High-Growth Market
The electric scooter market presents a compelling growth narrative, but growth alone does not guarantee competitive success. Organizations that thrive in this environment will be those that combine macro-level appreciation of market momentum with micro-level understanding of segmentation dynamics, competitive behavior, regulatory exposure, and supply-chain resilience. Aggregate figures provide necessary context, but they do not substitute for the granular intelligence required to allocate resources efficiently, position products effectively, and anticipate shifts before they become industry consensus.
This report offers that depth. It is structured to equip decision-makers with a comprehensive view of where the market stands, how it is evolving, and what strategic options are most likely to yield durable advantage through 2032. To access the full dataset, detailed segmentation breakdowns, regional performance analysis, competitive benchmarking, and the complete set of forecasts underpinning this analysis, we invite you to explore the full report on our platform. The complete intelligence package provides the precision necessary to convert market opportunity into executable strategy.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Photomask Market to Hit $5.9B by 2032 with 5.8% CAGR
By pmarketresearch, 2026-09-15
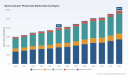
Navigating the Next Frontier: Strategic Insights into the Semiconductor Photomask Market (2026-2032)
The semiconductor photomask market stands at a critical inflection point. As the foundational templates for lithography—the process that transfers circuit designs onto silicon wafers—photomasks are the unsung enablers of every advanced chip, from high-performance computing to next-generation displays. In 2025, the global photomask market reached an estimated $4,010 million, reflecting a steady upward trajectory from the $3,000 million recorded in 2020. Looking ahead, our latest research pegs the industry to surpass $5.9 billion by 2032, growing at a compound annual growth rate of 5.8 percent across the forecast period. These figures do more than chart revenue; they map the architectural backbone of a technology ecosystem under intense geopolitical, technological, and supply chain pressure.
For corporate strategists, investment committees, and procurement leaders, understanding why this market is expanding—and where the friction points lie—is no longer optional. This article serves as a strategic preview of our comprehensive Semiconductor Photomask Market research, outlining the analytical framework, competitive intelligence, and operational playbooks embedded in the full report. We invite you to explore how deep segmentation, scenario modeling, and regulatory mapping can transform high-level market awareness into actionable 2026 decision-making.
The Macro Trajectory: A Decade of Compound Growth Amid Structural Shifts
The historical data from 2020 through 2025 reveals a market that has proven remarkably resilient despite global chip shortages, capacity bottlenecks, and shifting demand cycles. Annual revenues climbed from $3,000 million in 2020 to $3,454.85 million in 2022, then accelerated further to $3,606.03 million in 2023 and $3,729.34 million in 2024. The $4,010 million baseline in 2025 underscores a structural acceleration rather than a cyclical rebound. Forecasts extend this momentum through 2032, projecting steady year-over-year gains that place the market well above $5,500 million by the end of the decade.
A 5.8 percent CAGR may appear measured against the explosive growth of some AI-driven semiconductor segments, but in the photomask world, it reflects something more profound: sustained capital expenditure in advanced logic and memory fabs, the proliferation of high-resolution display manufacturing, and the gradual migration of mature-node production into newer geographies. Our report dissects this trajectory across multiple dimensions, revealing where growth is concentrated, which application verticals are outpacing the baseline, and how product mix evolution is reshaping vendor economics. The narrative is not monolithic; it is a mosaic of converging demand signals that require precise navigation.
Navigating Regulatory Currents and Supply Chain Realities
No strategic assessment of the photomask industry in 2026 is complete without addressing the regulatory and supply chain environment. The landscape has grown increasingly complex, with policy interventions and material constraints actively reshaping cost structures, lead times, and geographic sourcing strategies.
On the regulatory front, the United States has intensified its focus on semiconductor supply chain security. A February 2025 executive order imposed a 25 percent tariff on semiconductors originating from China, a move that rippled through the broader electronics manufacturing ecosystem. By January 2026, the U.S. Commerce Department escalated its scrutiny with a proposed Section 232 investigation targeting semiconductor products, explicitly including photomask blanks. These actions occur alongside sustained dialogue between industry bodies and government agencies; for instance, the Semiconductor Industry Association submitted formal comments to the Bureau of Industry and Security in May 2025, addressing export controls and supply chain resilience.
Simultaneously, the U.S. CHIPS and Science Act has unlocked more than $52 billion in federal grants and tax incentives since its inception, catalyzing new fabrication capacity and, by extension, demand for high-quality photomask supply. These incentives are not distributed evenly across the value chain; they favor regions and technologies aligned with national security and advanced manufacturing priorities.
Beyond policy, operational realities are testing manufacturers. Supply chain constraints on high-purity quartz substrates and specialty materials were reported by 27 percent of manufacturers, introducing variability in lead times and cost predictability. Such constraints are not merely tactical inconveniences; they influence capacity planning, vendor selection, and the geographic distribution of production assets. Our report maps these dynamics in granular detail, offering a framework for assessing regulatory exposure, material dependency, and the strategic value of nearshoring or dual-sourcing arrangements.
Photomask Market
Competitive Architecture: Leaders, Moves, and Market Concentration
The photomask industry is characterized by a concentrated yet dynamic competitive structure. Our analysis indicates that the top three players collectively command approximately 45 percent of global revenue, while the top five entities account for roughly 60 percent. This concentration reflects the high barriers to entry associated with advanced lithography mask fabrication, stringent quality requirements, and the capital intensity of maintaining cutting-edge process capabilities. Yet within this consolidated landscape, strategic moves, geographic expansions, and technological investments are continuously reshaping the competitive equilibrium.
Among the most prominent players, Photronics Inc., headquartered in Brookfield, Connecticut, operates as a merchant leader providing integrated circuit and flat-panel display photomasks across eleven global facilities spanning North America, Asia, and Europe. In May 2026, the company reported second-quarter fiscal 2026 results that highlighted ongoing investments in U.S. and Korean facilities aimed at expanding advanced photomask capacity. This dual-region strategy underscores a broader industry trend: balancing proximity to leading-edge logic and memory clusters with the operational resilience offered by geographically distributed manufacturing footprints.
In Japan, Tekscend Photomask Corp.—rebranded from Toppan Photomask and based in Tokyo—has emerged as a global provider of semiconductor photomasks and related microfabrication products, maintaining facilities across Japan, the United States, Europe, and Asia. Tekscend's recent activity illustrates an aggressive capacity expansion posture. In October 2025, the company held a groundbreaking ceremony for a new photomask manufacturing facility in Singapore, designed to supply advanced precision photomasks to high-growth nodes. Just months later, in January 2026, Tekscend received a $15.2 million grant from the Texas government to expand its Round Rock facility by over 40 percent and create 50 new jobs. These parallel investments signal a deliberate strategy to position capacity closer to both North American and Asia-Pacific demand centers while capitalizing on regional incentive structures.
Dai Nippon Printing Co., Ltd., also headquartered in Tokyo, has focused its innovation pipeline on photomasks for advanced extreme ultraviolet (EUV) lithography nodes, including 3nm and 2nm process technologies. As EUV continues to define the frontier of logic scaling, suppliers capable of delivering masks with the requisite pattern fidelity, defect control, and material performance gain strategic leverage in the value chain. Hoya Corporation, another Tokyo-based leader, dominates the supply of EUV mask blanks and photomask blanks, occupying a critical upstream position that influences the entire mask fabrication ecosystem. Broadly, Hoya's position reflects the reality that blank quality and availability are gating factors for downstream mask makers, linking material science directly to lithography yield.
Rounding out the competitive set, SK-Electronics Co., Ltd., based in Seongnam, South Korea, stands as a major supplier of semiconductor photomasks and mask blanks, reinforcing the importance of Korean manufacturing ecosystems in the global photomask supply chain. Collectively, these players demonstrate that competitive advantage in this market is not simply a function of scale; it is increasingly defined by technological readiness for next-generation nodes, geographic alignment with fab expansion, and the ability to navigate regulatory and material constraints without compromising delivery.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
Our Semiconductor Photomask Market research is structured to move beyond high-level market sizing and into the operational and strategic details that decision-makers require. The report integrates historical performance data, forward-looking forecasts, and a multi-dimensional segmentation framework that allows readers to isolate growth drivers, assess risk exposures, and benchmark competitive positioning. Below is a preview of the core components embedded in the full analysis.
Segmentation by Region: Geographic Demand and Incentive Landscapes
The regional breakdown of market activity provides essential context for capacity siting, sourcing strategies, and competitive targeting. Northern America represents the largest revenue concentration, followed by Asia Pacific, which captures the second-largest share of global activity. Europe, Latin America, and the Middle East and Africa collectively account for the remaining portion, with distinct growth profiles and policy environments. Rather than presenting static percentage allocations, the report examines how regional demand patterns intersect with fab investment cycles, incentive programs such as the CHIPS Act, and the geographic placement of mask fabrication and blank supply assets. This lens helps strategists identify where demand is likely to outpace local supply and where partnership or capacity expansion opportunities may emerge.
Segmentation by Type: Reticle, Master, and Supporting Products
The product mix dimension is central to understanding vendor economics and technology roadmaps. Reticle-type photomasks command the highest revenue share, reflecting their critical role in high-volume manufacturing of integrated circuits. Master masks and other product categories contribute meaningful revenue streams, often serving specialized applications or acting as enabling inputs for next-generation processes. The report analyzes how the relative weight of each product category is evolving as node scaling, multi-patterning requirements, and display manufacturing demands shift the demand mix. This analysis is particularly valuable for suppliers evaluating portfolio prioritization and for buyers assessing long-term supply reliability across mask types.
Segmentation by Application: End-Market Demand Drivers
Demand for photomasks is ultimately anchored in the end markets they enable. Display manufacturing represents the largest application vertical, driven by the ongoing transition to high-resolution panels and advanced organic light-emitting diode technologies. Discrete components and optical devices form the next tier of demand, each with distinct technology roadmaps and procurement cycles. Microelectromechanical systems, while smaller in aggregate revenue, represent a high-precision segment where mask quality directly affects device performance. The full report examines how these application segments are expected to grow over the forecast period, what differentiates their pricing and specification dynamics, and how shifts in consumer electronics, automotive, and industrial demand translate into photomask order books.
Competitive Profiling and Tactical Intelligence
Beyond company-level profiles, the report synthesizes recent developments, facility investments, and strategic announcements to build a living map of competitive intent. Coverage includes expansion grants, new facility groundbreakings, equipment installation milestones, and financial reporting highlights that reveal where leading players are allocating capital. For example, the report contextualizes Tekscend Photomask's dual expansion in Texas and Singapore alongside Photronics' investments in U.S. and Korean facilities, using these moves to illuminate broader themes such as regional incentive capture, capacity localization, and node-specific capability building. This competitive intelligence is designed to support supplier selection, partnership evaluation, and strategic positioning exercises.
Translating Intelligence into 2026 Action Plans
Market research delivers value only when it is operationalized. Our report is built with that principle in mind, offering analytical structures that can be integrated directly into corporate strategy workflows. For capacity planners and procurement leaders, the segmentation frameworks provide a basis for demand forecasting, supplier diversification, and lead-time risk management—particularly important given the reported material constraints and the evolving regulatory environment. For investors and corporate development teams, the competitive profiling and growth trajectory analysis offer a foundation for evaluating market entry feasibility, partnership structures, and the strategic implications of concentration dynamics.
For executives monitoring geopolitical risk, the report's integration of policy actions—from tariff impositions and Section 232 investigations to export control discussions and incentive program impacts—creates a scenario-ready view of how regulatory shifts could affect cost structures, sourcing options, and regional competitiveness. This is not a static snapshot; it is a structured assessment that can be calibrated as policy trajectories and material supply conditions evolve.
Why the Full Intelligence Package Matters
The preview provided here captures the analytical architecture and strategic relevance of our Semiconductor Photomask Market research, but the complete report contains the detailed segmentation data, company-level profiling, scenario analysis, and forward-looking forecasts that enable precise decision-making. The macro numbers—$4,010 million in 2025, a 5.8 percent CAGR, and a projected $5,919 million market size by 2032—set the stage. The real strategic advantage lies in understanding where growth concentrates, how competitive moves reshape supply dynamics, and which regulatory and material risks demand proactive mitigation.
Semiconductor Photomask Market
To access the complete segmentation breakdowns, in-depth company profiles, regulatory impact assessments, and forecast models that power these insights, we invite you to explore the full research on our website. The report is designed for leaders who need more than a market overview—they need a decision-grade intelligence framework aligned with the realities of 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Semiconductor Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pad Printing Supplies Market to Hit $267.3M by 2032 with 5.65% CAGR
By pmarketresearch, 2026-09-15
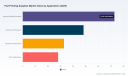
Strategic Intelligence for the Pad Printing Supplies Market: A 2032 Outlook
For procurement leaders, R&D directors, and competitive intelligence teams operating in industrial decoration and precision marking, the Pad Printing Supplies Market represents a microcosm of broader manufacturing shifts.
Over the past half-decade, the industry has navigated raw material volatility, tightening chemical regulations, and accelerating demand for eco-compliant consumables. The newly released Pad Printing Supplies Market research report distills these dynamics into a decision-grade framework, offering enterprise stakeholders a clear line of sight from historical performance through 2032. This overview previews the analytical architecture of the study and explains why its insights are indispensable for 2026 strategy formation.
The report is built on a rigorous methodological foundation that tracks revenue movement from 2020 through the base year of 2025. Historical data captures the market at roughly US$148.75 million in 2020, progressing through a series of incremental expansions to reach US$182.0 million by 2025. This trajectory reflects the sector's resilience against supply chain disruptions and its steady adoption in high-mix, low-volume production environments. Looking ahead, the forecast horizon extends to 2032, projecting the total market to surpass US$267 million over the period. The implied compound annual growth rate of 5.65 percent provides a reliable benchmark for investment pacing, capacity planning, and product roadmapping. Rather than presenting isolated figures, the study embeds these numbers within demand-side drivers, regulatory headwinds, and regional supply chain reconfigurations.
A defining feature of the 2026–2032 outlook is the tension between end-use momentum and material compliance. Pad printing has long been favored for its ability to reproduce fine detail on irregularly shaped substrates, but recent years have elevated the stakes for ink chemistry, pad durability, and cliché precision. Manufacturers serving consumer goods, hard goods, and identification applications increasingly require consumables that satisfy a mosaic of regulatory frameworks without sacrificing adhesion or line quality. The research report maps how these requirements reshape procurement criteria, how suppliers are re-engineering solvent and UV-based chemistries, and where end-users are willing to pay a premium for certified, low-VOC, and phthalate-free formulations. By examining the intersection of technical performance and compliance cost, the study provides a practical lens for evaluating total cost of ownership rather than sticker price alone.
Decoding the Market Structure: Concentration, Type, and Application Pressures
Market structure analysis is central to any credible strategic assessment, and this report approaches the Pad Printing Supplies Market with particular attention to competitive density and segmentation behavior. The sector exhibits moderate concentration at the top tier, with the leading three players accounting for approximately 32.4 percent of aggregate revenue and the top five reaching roughly 47.6 percent. Such figures signal a landscape where scale, distribution footprint, and technical service capabilities provide durable advantages, yet where specialized regional players and product-focused specialists retain meaningful share through customization and rapid turnaround.
Within this framework, the analysis examines how supply portfolios split across ink technologies and auxiliary materials. Solvent-based chemistries continue to hold a prominent position, reflecting entrenched manufacturing workflows and cost-performance expectations in established production lines. At the same time, UV-curable systems are steadily gaining relevance as throughput requirements intensify and cure-on-demand workflows reduce energy and solvent management burdens in controlled factory environments. Ceramic formulations and other specialized ink categories occupy a smaller but strategically significant role, particularly where marking durability, thermal exposure, and surface compatibility are decisive. The report evaluates how these type-level dynamics influence supplier negotiations, inventory strategies, and substitution risks across different production contexts.
On the application side, the research dissects the demand architecture across major end-use categories. Glass and plastic products represent a substantial portion of the addressable market, consistent with the versatility of pad printing on non-flat surfaces and the enduring need for labeling, logo replication, and identification across consumer and industrial goods. Ceramic and porcelain applications form another significant pillar, driven by tableware, sanitaryware, and decorative goods manufacturers that demand inks capable of bonding to glazed and unglazed surfaces under varied curing conditions. Electronic components constitute an increasingly important niche, where miniature print fidelity, material compatibility, and traceability requirements push suppliers toward tighter process control and more specialized consumables. A broader set of remaining applications rounds out the demand matrix, illustrating how pad printing continues to migrate into adjacent use cases. The study deliberately avoids one-dimensional allocation tables, instead framing each application segment through operational requirements, regulatory exposure, and growth sensitivity to macroeconomic demand cycles.
Regional Divergence and Supply Chain Realities
Geographic context is indispensable for understanding where growth is being generated and how supply chains are adapting. The report profiles the Pad Printing Supplies Market across five major regional clusters: North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents a distinct combination of manufacturing density, regulatory posture, distributor infrastructure, and end-user purchasing behavior.
North America reflects a mature demand environment supported by a broad base of industrial decorators, packaging specialists, and contract manufacturers who prioritize reliability, service responsiveness, and compliance documentation. European operations are shaped by stringent chemical legislation, high labor costs, and an industry that increasingly rewards sustainable formulators and suppliers with traceable quality systems. Asia Pacific combines the most expansive manufacturing backdrop with rapidly evolving automation adoption, making it a region where volume, localization, and price competitiveness intersect with rising quality expectations. Latin America and the Mideast and Africa represent smaller yet strategically relevant markets, where import dependency, freight variability, and selective industrial growth patterns influence both supplier entry decisions and procurement timing.
Pad Printing Supplies Market
Worldwide Specialty Ink Market
Rather than reducing these dynamics to static share figures, the study assesses how regional differences alter lead-time risk, inventory buffering, formulation requirements, and aftermarket service expectations. The result is a practical decision tool for companies evaluating distribution expansion, localized stocking, or cross-border sourcing adjustments as the forecast period unfolds.
Competitive Landscape: Eight Companies Setting Different Standards
No market assessment is complete without a grounded view of the competitors actually shaping supply. The Pad Printing Supplies Market is populated by firms that compete on different axes: comprehensive consumables portfolios, machine and tooling integration, eco-certification leadership, and regional distribution scale. The research report profiles eight companies that exemplify these strategic postures and influence buying expectations across multiple segments.
TAMPOPRINT AG, headquartered in Germany, structures its offering around a complete pad printing consumables line, including inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production. This breadth positions the company as a one-stop resource for operations that prefer consolidated specification and reduced vendor fragmentation. INX International, based in the United States, emphasizes performance and regulatory alignment through its INXPad T200 solvent-based and UV pad printing inks. Its eco-formulations are designed to be free from phthalates and BPA, targeting packaging and product decoration environments where compliance documentation carries commercial weight. Marabu Druckfarben, also German, maintains a wide range of solvent-based and UV-curable pad printing inks focused on industrial decoration, marking, and identification, appealing to users with high repeatability requirements across varied substrate types.
Teca-Print USA, operating from the United States, concentrates on consumables supported by custom-mixed inks, printing pads, cliché plates, and full automation support, making it relevant for shops moving from manual to semi-automated workflows. Inkcups Now Corporation, likewise U.S.-based, has built visibility around ink cups, ceramic rings, and eco-responsible ink systems, including its SB Eco Series certified under GOTS and compliant with REACH and RoHS. Printex USA rounds out the equipment-plus-consumables profile by offering custom pad printing machines, tooling, fixtures, and consumables tailored for high-volume automated applications. ITW Trans Tech provides a full range of pad printing machines, fixtures, inks, pads, and printing plates, reinforced by what is described as the largest North American ink warehouse, a structural advantage for customers sensitive to replenishment speed. Boston Industrial Solutions differentiates through in-house silicone pads, inks, plates, fixtures, and accessories, allowing tighter control over the physical interface between pad, ink film, and substrate.
Regulatory Change as a Demand-Shaping Force
Regulatory and certification developments are no longer peripheral concerns in this market; they actively redirect procurement decisions and product roadmaps. A March 2025 milestone underscores this shift, when seven inks in the SB Eco Series achieved GOTS certification, reinforcing the broader movement toward formulations free from naphtha, PAH, and cyclohexanone while satisfying REACH, RoHS, and EN 71-3. This trajectory matters because it alters the qualification threshold for suppliers serving consumer-facing and regulated product categories.
A September 2025 product launch further illustrates how performance and compliance are being engineered together. The introduction of INXPad T200 solvent-based pad printing inks at K 2025 highlighted a sustainable system intended to enable recycling of recovered packaging materials while delivering high durability for toys, electronics, automotive, and promotional items. Equally important, these inks are described as free from phthalates and BPA and suitable for printing onto the non-food contact side of packaging, with compliance spanning REACH, RoHS, the Swiss Ordinance, the Toy Safety Directive, the GADSL list, and the EuPIA Exclusion Policy. Marabu has similarly aligned its pad printing inks with REACH and RoHS requirements, while broader industry references point to ISO 9001 and ISO 14001 certified ink lines with medical-grade biocompatibility testing, as well as eco-certified consumables validated under Eco-Passport, CLP/GHS, EN 71-3, REACH, and RoHS. These developments are not isolated; they signal that chemical stewardship, traceability, and certification readiness are increasingly part of the baseline commercial evaluation.
Inside the Research: What Decision-Makers Can Use Immediately
The strategic value of this report lies in its operational specificity. It is designed not only to explain market direction but to support concrete choices in sourcing, forecasting, and competitive positioning. Readers can expect a structured analysis that moves from macro trajectory to actionable segmentation intelligence, while preserving the analytical discipline needed to avoid overgeneralizing across diverse end-use contexts.
Key components include:
- A historical-to-forecast revenue assessment that benchmarks the current cycle and clarifies the pace of expansion through 2032.
- Systematic coverage of type-level dynamics across solvent-based, UV-curable, ceramic, and other ink portfolios, framed by performance trade-offs and regulatory exposure.
- Application-level evaluation across glass and plastic products, ceramic and porcelain, electronic components, and other use cases, emphasizing operational requirements and demand sensitivity.
- Regional analysis that links localized manufacturing conditions, distribution logistics, and compliance expectations to procurement strategy.
- Competitive profiling of major suppliers with attention to product breadth, automation support, eco-certification, and service infrastructure.
- Structured tracking of recent developments, certifications, and regulatory alignments that are reshaping qualification criteria for consumables.
- Decision-oriented synthesis for capacity planning, vendor consolidation, formulation selection, and market-entry prioritization.
By balancing breadth with depth, the study avoids the common pitfall of presenting segmentation data in isolation. Instead, it connects type, application, and regional behavior to real procurement pressures, allowing users to interpret numbers within the operational context that actually drives purchasing decisions.
Why 2026 Demands a Sharper Market View
The 2026 decision environment will be defined by a combination of demand stability, formulation evolution, and compliance-driven qualification. With the total market projected to reach approximately US$198.38 million in 2026 and continue expanding toward US$267.3 million by 2032, the size of the opportunity is clear. The more difficult question for enterprise teams is where growth will accrue, which product categories will face substitution pressure, and how quickly regulatory expectations will alter approved-supplier lists. A 5.65 percent CAGR is not merely a headline statistic; it is a planning parameter that helps set expectations for revenue expansion, inventory investment, and R&D prioritization across the forecast window.
At the same time, market concentration around the top three and top five players indicates that scale and service reliability still matter. Enterprises that depend on just-in-time replenishment, tight color matching, or specialized pad and cliché performance will need to assess not only what suppliers offer today but how those suppliers are adapting to sustainability, documentation, and automation demands. The report's competitive and regulatory analysis is intended to support those evaluations with current evidence rather than assumptions.
From Insight to Action: Accessing the Full Intelligence
Pad printing may be a specialized process, but its consumables market reflects the same strategic truth facing most industrial supply sectors: performance, compliance, and supply continuity now intersect in ways that reward early, evidence-based positioning. The Pad Printing Supplies Market research report is designed to give executives, procurement teams, and market strategists that evidentiary base. It consolidates historical trajectory, forward-looking growth modeling, competitive profiling, and regulatory developments into a single analytical structure tailored to practical use.
To move from directional understanding to fully segmented, decision-grade intelligence, the complete dataset and detailed analytical breakdown are available through the published report. The full market size progression, segmentation coverage, regional interpretation, and company-level assessments provide the granularity needed for budgeting, sourcing strategy, and competitive response planning. For teams preparing 2026 initiatives, the report offers both the context to interpret market movement and the structured evidence to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gel Batteries Market Hits $2.49B in 2025, Poised for 7.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in Gel Batteries: Navigating Growth Through 2032
The global energy storage landscape is undergoing a profound transformation, driven by the urgent need for reliable, safe, and cost-effective backup solutions. Within this shifting paradigm, the Gel Batteries Market stands out as a critical segment, offering distinct advantages in deep-cycle endurance and maintenance-free operation. As we move beyond 2025, understanding the trajectory of this market is not merely an academic exercise but a strategic necessity for stakeholders across telecommunications, renewable energy, and industrial sectors. PW Consulting's latest market research provides a comprehensive roadmap for navigating this complex environment, equipping decision-makers with the intelligence required to capitalize on emerging opportunities through 2032.
A Decade of Growth: Macro Trends and Financial Trajectories
The historical performance of the gel battery sector underscores its resilience and expanding relevance. From a baseline of 1.0 billion USD in 2020, the market has demonstrated consistent upward momentum, reaching 2.49 billion USD by 2025. This growth reflects a broader industrial shift toward valve-regulated lead-acid (VRLA) technologies that mitigate the risks associated with liquid electrolytes, such as leakage and corrosion. The stability of this expansion is projected to continue, with revenues anticipated to climb to 2.7 billion USD in 2026 before accelerating toward 4.04 billion USD by 2032.
Gel Batteries Market
This trajectory is underpinned by a compound annual growth rate (CAGR) of 7.2 percent during the forecast period of 2026 to 2032. For strategic planners, this figure is more than a statistic; it represents a robust avenue for capital allocation and product development. The sustained growth indicates that gel technology is not being rendered obsolete by newer chemistries but is instead finding specialized niches where reliability outweighs the premium cost sometimes associated with lithium alternatives. Our report delves into the drivers sustaining this CAGR, analyzing how regulatory pressures and infrastructure upgrades contribute to steady demand across key verticals.
Segmentation Dynamics: Type and Application Insights
Understanding where value is generated within the market is crucial for targeted strategy. The market is primarily divided by type into stationary and motive power segments. The stationary segment larger share in 2025, driven by the relentless rollout of telecommunications infrastructure and renewable energy storage systems. Telecom operators rely heavily on gel batteries for base station backup due to their tolerance for varying temperatures and extended shelf life. Similarly, the renewable energy sector utilizes gel batteries to stabilize output from solar and wind installations, ensuring power availability during intermittent generation periods.
The application landscape further nuances this demand. Telecommunications and renewable energy storage represent significant pillars of consumption, absorbing substantial portions of production capacity. However, the others category remains a diverse and vital component, encompassing industrial machinery and specialized marine applications. Our analysis dissects these segments to identify which sub-verticals are experiencing the fastest adoption rates. While specific regional percentages are reserved for the full report to protect client confidentiality and encourage deeper engagement, the qualitative trend is clear: stationary applications are the primary engine of growth, supported by grid modernization efforts globally.
Regional Perspectives and Demand Hotspots
Geographically, the market exhibits varied maturity levels and growth potentials. Asia Pacific represents a significant volume driver, fueled by rapid industrialization and substantial investments in grid storage capabilities. North America and Europe continue to be mature markets where replacement cycles and sustainability regulations drive steady demand. Meanwhile, emerging regions in Latin America and the Middle East and Africa offer nascent but high-potential opportunities as infrastructure development accelerates.
Our research provides a granular view of these regional dynamics without limiting the scope to static market shares. Instead, we focus on the underlying economic and policy factors influencing regional adoption. For instance, government policy reports from 2025 indicate that carbon tax policies and emission reduction goals are driving industry-wide adoption of VRLA gel technology in multiple regions. This regulatory tailwind is particularly potent in Europe and parts of Asia, where compliance costs for less efficient technologies are rising. Understanding these regional policy landscapes is essential for companies planning supply chain logistics and market entry strategies.
Competitive Landscape: Key Players and Strategic Moves
The market concentration is moderate, with the top three companies holding approximately 48 percent of the market share and the top five controlling around 62 percent. This structure suggests a competitive environment where established giants coexist with specialized manufacturers capable of innovating quickly. Several key companies define the current landscape, each leveraging unique technological strengths.
Exide Technologies, headquartered in India, has long been a cornerstone of the market. Their focus on patented gel dryfit VRLA technology positions them strongly for deep-cycle applications including marine, equipment, and renewable energy storage. In February 2025, Exide Technologies announced a 100 million USD investment to expand gel battery manufacturing capacity, a direct response to demand surges from renewable energy and telecom sectors. This capital expenditure signals a strong commitment to capturing the forecasted growth in the 2026 to 2032 period.
Trojan Battery Company, based in the United States, maintains a strong foothold with deep-cycle gel batteries tailored for solar, marine, and off-grid renewable energy systems. Their product philosophy emphasizes longevity and reliability in remote settings, aligning with the needs of the expanding microgrid market. Similarly, East Penn Manufacturing offers the Deka Ready Power gel battery line, catering to both motive power and renewable applications, ensuring versatility across industrial and energy storage use cases.
In the industrial and telecom spheres, GS Yuasa Corporation of Japan provides gel lead-acid batteries optimized for industrial, renewable, and telecom energy storage. Their reputation for quality in extreme conditions makes them a preferred partner for critical infrastructure. Amara Raja Batteries, also based in India, contributes significantly with gel batteries for industrial and renewable energy storage solutions, leveraging local manufacturing capabilities to serve regional demand efficiently.
European influence remains strong through entities like Sonnenschein Batteries, which operates under the Exide Group umbrella. In January 2025, Sonnenschein Batteries unveiled a new high-capacity gel battery specifically for grid storage and renewable integration projects. This product launch highlights the industry trend toward higher capacity units capable of supporting utility-scale applications. Further west, Banner Batteries from Austria continues to supply gel batteries for industrial and renewable energy uses, maintaining high standards for European market compliance. Enersys, another United States-based player, focuses on gel battery technology for motive and stationary energy storage applications, bridging the gap between material handling equipment and fixed storage solutions.
Recent Developments and Innovation Trajectories
Innovation within the sector is not limited to established names. Recent developments indicate a broadening of technical capabilities. In February 2025, Narada Power opened a new R&D center in Shanghai dedicated to next-generation gel battery chemistry and manufacturing processes. This move underscores the importance of Asian R&D hubs in advancing global technology standards. Furthermore, in March 2025, Hoppecke Batteries launched a modular gel battery system for commercial EV fleets offering enhanced safety and lifecycle performance. This development illustrates the convergence of gel battery technology with electrification trends in transportation, expanding the potential addressable market beyond traditional stationary uses.
Regulatory Frameworks and Industry Dynamics
Navigating the regulatory environment is as critical as managing technology roadmaps. Battery Council International convened the first-ever meeting of its Sodium Battery Industry Group on May 4 2026 to advance standards for energy storage technologies including advanced lead-acid variants. While focused on sodium, this regulatory push signals a broader scrutiny and standardization effort across energy storage chemistries, which indirectly benefits established gel technologies by clarifying compliance pathways.
Sector Analysis indicates targeted renewable energy subsidies and grid code updates continue to support deployment of gel battery systems in utility-scale storage applications. These financial incentives lower the barrier to entry for large-scale projects, making gel batteries a financially viable option for utility planners. However, compliance is mandatory. ISO 9001 and ISO 14001 certifications are mandated for all gel battery production facilities to ensure quality and environmental compliance. Manufacturers failing to meet these standards face exclusion from supply chains in regulated markets.
Supply chain stability also hinges on critical mineral management. Lead remains the core critical mineral in gel batteries with ongoing mining and recycling efforts by major producers supporting supply chain stability. Investors and procurement officers must monitor these supply dynamics closely, as fluctuations in lead availability can impact production costs and margins. Our report evaluates these supply chain risks in detail, offering strategies for mitigating material volatility.
Tubular GEL Battery Market
Strategic Value of the PW Consulting Report
For executives and strategists, accessing detailed market intelligence is the first step toward informed decision-making. This report goes beyond surface-level data to provide actionable insights. It examines the intersection of policy, technology, and demand to forecast how the market will evolve. Readers will gain clarity on which applications are poised for expansion and where competitive intensity might compress margins.
The analysis of market concentration helps identify consolidation opportunities. With the top five players controlling over 60 percent of the market, there is a clear hierarchy. However, the presence of agile R&D centers and new product launches suggests that niche players can carve out profitable segments. Understanding where these opportunities lie requires the depth of analysis provided in our full study. We explore how companies like Exide and Trojan are adjusting their portfolios to meet the demands of 2026 and beyond, offering case studies on successful capacity expansions and product innovations.
Furthermore, the report addresses the risks associated with regulatory changes. As ISO mandates tighten and carbon policies evolve, manufacturers must adapt their processes. Our findings outline the compliance requirements necessary to maintain market access. For investors, this due diligence is invaluable in assessing the viability of potential partners or acquisition targets.
Conclusion: Positioning for the 2032 Horizon
The Gel Batteries Market is on a steady path of expansion, driven by the inherent advantages of the technology and supportive macroeconomic trends. The projected growth from 2.7 billion USD in 2026 to over 4 billion USD by 2032 offers substantial room for strategic maneuvering. However, realizing value in this market requires more than optimism; it demands precise intelligence on segmentation, competition, and regulatory shifts.
PW Consulting's comprehensive market research serves as an essential tool for navigating this landscape. By synthesizing historical data, forecasting future trends, and analyzing the moves of key competitors, we provide a foundation for robust strategic planning. Whether you are looking to invest in manufacturing capacity, enter new geographic regions, or develop next-generation storage solutions, the insights contained in this report are designed to guide your approach. The full depth of segmentation data, regional breakdowns, and competitive profiling is available through our complete study, ensuring you have the specific intelligence needed to lead in this evolving sector.
For detailed analysis of this topic, please visit the official page: Gel Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Forging Presses Market Hits USD 208.45M in 2025, Poised for 4.3% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Forging Presses Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation, driven by the dual imperatives of industrial decarbonization and the relentless demand for high-strength, precision-engineered components. At the heart of this evolution lies the forging presses market, a critical machinery segment that underpins automotive lightweighting, aerospace structural integrity, and heavy industrial capacity. As we move into 2026, enterprise leaders and capital equipment strategists require more than fragmented data points. They need a cohesive, forward-looking intelligence framework that maps market trajectories, competitive maneuvering, and technological inflection points. Our newly released Forging Presses Market research report delivers precisely that: a comprehensive, decision-ready blueprint designed to align capital allocation, R&D prioritization, and Supply Chain positioning with the realities of the coming decade.
Market Architecture and the 2026 Growth Trajectory
Understanding the forging presses market requires a clear view of its structural evolution over the past half-decade. The sector has demonstrated consistent expansion, with total market revenue climbing steadily from 2020 through 2025 as global industrialization, infrastructure investment, and advanced manufacturing adoption compounded demand. This historical momentum has established a robust foundation for the current forecast window, which extends through 2032. The baseline year of 2025 reflects a mature yet dynamically expanding market, and the trajectory projected for 2026 indicates a meaningful inflection in capital equipment orders, technological upgrades, and regional capacity realignment.
Forging Presses Market
Our analysis projects a compound annual growth rate of 4.3 percent across the forecast horizon. While this figure may appear moderate at first glance, it obscures a far more important narrative: growth is not uniformly distributed. It is concentrated in specific technology pathways, application verticals, and geographic corridors where regulatory pressure, energy economics, and labor constraints are simultaneously reshaping procurement behavior. The 2026 market milestone represents more than a numerical checkpoint. It signals a transition phase where legacy mechanical systems are being strategically supplemented or replaced by hydraulic and servo-driven platforms that offer precision, energy recovery, and automation compatibility. For executives evaluating capacity expansion, modernization cycles, or cross-border equipment sourcing, understanding the timing and sequencing of this transition is essential. The research unpacks the underlying drivers of this growth curve, mapping how macroeconomic indicators, raw Material cost structures, and plant-level efficiency mandates converge to influence purchasing decisions at the operational level.
Segmentation Dynamics: Where Value Is Being Created
A superficial reading of market size inevitably leads to misallocated resources. The Forging Presses Market is characterized by distinct segmentation layers, each with its own technology adoption cycles, end-user procurement logic, and competitive intensity. Mechanical forging systems continue to hold substantial share, particularly in high-volume production environments where throughput consistency and established maintenance ecosystems remain advantageous. Yet the hydraulic segment is capturing disproportionate attention from capital manufacturers and end-user engineering teams. This shift is not merely a preference for newer technology. It reflects a structural realignment toward applications demanding complex part geometries, variable tonnage control, and integration with downstream automated handling systems.
Application-side dynamics further illustrate where strategic focus is accumulating. Automotive manufacturing remains a primary demand engine, driven by the ongoing transition toward lighter structural components, electrification-compatible housing designs, and closed-die precision requirements. Aerospace demand sustains a parallel growth vector, with stringent material certification standards and fatigue-critical component specifications pushing forging specifications toward higher tonnage capabilities and tighter tolerance tolerances. Beyond these dominant verticals, hardware tools, general machinery, and specialized industrial applications contribute to a diversified demand base that buffers the market against cyclical downturns in any single sector. Regional demand patterns similarly reveal nuanced deployment strategies, with established industrial corridors sustaining steady replacement and upgrade cycles while emerging manufacturing hubs accelerate new capacity installations. Our report dissects these segmentation layers without reducing them to isolated percentages, instead presenting them as interacting forces that dictate pricing power, lead-time expectations, and technology roadmapping for equipment suppliers and buyers alike.
Competitive Landscape and Strategic Positioning
The forging presses market is defined by a concentrated yet highly differentiated competitive field. Leading manufacturers are no longer competing solely on tonnage ratings or unit pricing. They are competing on system integration, energy performance, automation readiness, and aftermarket service ecosystems. Our competitive analysis maps the strategic profiles of the sector's most influential players, tracing how each organization is positioning itself across mechanical, hydraulic, and hybrid technology pathways.
Cold Forging Machine Market
North American manufacturers maintain a strong footprint by emphasizing custom engineering, application-specific configurations, and responsive service networks. Companies such as Beckwood Press Company and Ajax-Ceco Machinery have built enduring reputations around hydraulic solutions tailored to both open-die and closed-die operations, with capacity ranges that address mid-to-large industrial requirements. Verson, operating within the broader SMS Group portfolio, provides a diversified offering spanning mechanical, hydraulic, and servo configurations, enabling end-users to align press specifications with variable production targets. Stamtec and C.W. Bear Company reinforce the segment's breadth by supplying mechanical, cold, and warm-hot forging solutions alongside supporting metal forming equipment. Distributors and component specialists such as L.T. Rogers Company and C.E. Johns & Co. play essential roles in sustaining ecosystem resilience, ensuring that legacy installations can be upgraded, maintained, and retrofitted as technology standards advance. National Forging Company and The Precision Hydraulic Press Co. further illustrate the market's dual identity as both an equipment manufacturing space and an operational service environment, while Hydro Punch Press Inc. and Sintokogio America Inc. address specialized forming and heavy industrial requirements. Jier Machine Tool and Macrodyne round out the competitive field with large-capacity hydraulic and servo solutions, the latter extending its reach into ultra-high-tonnage applications that serve extreme industrial demands.
International players are equally reshaping market expectations. Schuler Group has emerged as a global reference point for hydraulic and hybrid press architectures, leveraging advanced energy recovery systems and precision control frameworks to meet stringent European and global efficiency benchmarks. AIDA Engineering and Komatsu Industries contribute high-volume mechanical and servo capabilities that align with disciplined production cadence requirements, while SMS Group continues to expand its automation-integrated hydraulic press offerings for both open-die and closed-die environments. Fagor Arrasate reinforces the European supply base with forming machine expertise that complements broader press ecosystems. The result is a competitive landscape where differentiation is increasingly measured by engineering flexibility, environmental compliance, and lifecycle economics rather than hardware specifications alone.
Innovation Vectors and Recent Developments
Technology momentum in the forging presses market is accelerating, and recent developments provide a clear window into the direction of industry evolution. In July 2025, Maxiforja Group initiated production on the world's largest forging press delivered by ANDRITZ Schuler, incorporating a Kinetic Energy Recovering System that exemplifies the sector's move toward energy-conscious heavy manufacturing. Shortly thereafter, in October 2025, Schuler AG completed the delivery of its first full hybrid hydraulic-electric 4000-ton press to Audi Neckarsulm, achieving a 28 percent reduction in energy consumption. These milestones are not isolated engineering accomplishments. They demonstrate a broader industry pivot where energy recovery, hybrid actuation, and digital control integration are becoming procurement prerequisites rather than optional enhancements.
Also in October 2025, SMS Group successfully commissioned a fully automatic closed-die forging press at TZCO Chain Manufacturing in China, achieving throughput rates of up to 30 strokes per minute. This deployment underscores the growing importance of automation integration in high-cadence production environments, where labor constraints and consistency requirements are pushing manufacturers toward fully automated press lines. More recently, in May 2026, Macrodyne participated in the Forging Industry Technical Conference, signaling continued engagement with end-users, engineering teams, and technology partners around next-generation hydraulic and servo press architectures. These developments collectively illustrate an industry that is simultaneously scaling capacity and compressing energy intensity, a duality that directly informs equipment selection criteria and capital planning timelines.
Structural Forces Reshaping Procurement and Investment
Beyond corporate announcements and tonnage milestones, several structural forces are redefining how forging presses are specified, purchased, and operated. Carbon steel continues to account for a significant share of raw material utilization within the forging sector, driven by its favorable balance of cost-effectiveness and mechanical strength. This material dependency influences not only component design but also press tonnage selection, die durability expectations, and maintenance scheduling. Equipment strategies that ignore material-specific forming behavior risk suboptimal lifecycle economics and increased downtime.
Regulatory and energy efficiency mandates are exerting equally powerful pressure. Industry guidance now expects forging press technologies to deliver energy consumption reductions in the range of 22 to 35 percent compared to conventional systems. This benchmark is reshaping vendor evaluation frameworks, as procurement teams increasingly factor operational energy costs, recovery capabilities, and control system efficiency into total cost of ownership calculations. Simultaneously, persistent labor shortages across forging operations are accelerating investment in automation, digital control systems, and semi-autonomous press lines. Plant operators are no longer treating automation as a future-state aspiration. They are implementing it as a near-term operational necessity to mitigate personnel constraints, stabilize production cadence, and reduce variability in part quality. These dynamics converge to create a market environment where equipment decisions must account for energy performance, labor economics, and material behavior in an integrated manner. Our report provides the analytical scaffolding required to evaluate these forces systematically, allowing decision-makers to anticipate procurement timing, technology adoption windows, and competitive response patterns.
What This Research Delivers for 2026 Decision-Making
The Forging Presses Market research is structured to translate complex market data into actionable strategic guidance. Rather than presenting static tables in isolation, the report integrates market sizing, segmentation logic, competitive profiling, and macro-industrial context into a unified decision framework. Readers will find detailed assessments of mechanical and hydraulic technology pathways, including adoption drivers, performance trade-offs, and lifecycle cost implications. The application-side analysis connects end-user requirements in automotive, aerospace, hardware tools, general machinery, and other industrial sectors to specific press configurations and procurement behavior. Regional market dynamics are examined through the lens of capacity deployment, demand maturity, and technology diffusion patterns, providing context for sourcing strategies and market-entry considerations.
The competitive analysis extends beyond company summaries to evaluate strategic positioning, technology emphasis, and ecosystem influence. Recent developments are contextualized within broader industry trends, enabling readers to distinguish between discrete events and structural shifts. Market concentration metrics are incorporated to illuminate the balance between established incumbents and specialized challengers, while raw material dependence, energy mandates, and labor dynamics are woven into the discussion of procurement and investment timing. Altogether, the report equips capital equipment manufacturers, end-user engineering teams, investors, and supply chain strategists with the insight needed to align product roadmaps, capacity planning, and vendor evaluation with the market's actual trajectory.
Accessing the Full Intelligence Framework
The forging presses market is entering a phase where strategic advantage will belong to organizations that can read technological signals, interpret demand shifts, and time capital decisions accordingly. This research is designed to provide that capability. It offers the depth required to support rigorous internal analysis and the structural clarity necessary to translate findings into operational planning. For leaders seeking comprehensive segmentation data, detailed company profiles, full forecast breakdowns, and integrated scenario analysis, the complete report is available for review. Access the full publication to equip your 2026 and beyond strategy with decision-grade market intelligence.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com