

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gel Batteries Market Hits $2.49B in 2025, Poised for 7.2% CAGR Through 2032

Strategic Imperatives in Gel Batteries: Navigating Growth Through 2032
The global energy storage landscape is undergoing a profound transformation, driven by the urgent need for reliable, safe, and cost-effective backup solutions. Within this shifting paradigm, the Gel Batteries Market stands out as a critical segment, offering distinct advantages in deep-cycle endurance and maintenance-free operation. As we move beyond 2025, understanding the trajectory of this market is not merely an academic exercise but a strategic necessity for stakeholders across telecommunications, renewable energy, and industrial sectors. PW Consulting's latest market research provides a comprehensive roadmap for navigating this complex environment, equipping decision-makers with the intelligence required to capitalize on emerging opportunities through 2032.
A Decade of Growth: Macro Trends and Financial Trajectories
The historical performance of the gel battery sector underscores its resilience and expanding relevance. From a baseline of 1.0 billion USD in 2020, the market has demonstrated consistent upward momentum, reaching 2.49 billion USD by 2025. This growth reflects a broader industrial shift toward valve-regulated lead-acid (VRLA) technologies that mitigate the risks associated with liquid electrolytes, such as leakage and corrosion. The stability of this expansion is projected to continue, with revenues anticipated to climb to 2.7 billion USD in 2026 before accelerating toward 4.04 billion USD by 2032.
Gel Batteries Market
This trajectory is underpinned by a compound annual growth rate (CAGR) of 7.2 percent during the forecast period of 2026 to 2032. For strategic planners, this figure is more than a statistic; it represents a robust avenue for capital allocation and product development. The sustained growth indicates that gel technology is not being rendered obsolete by newer chemistries but is instead finding specialized niches where reliability outweighs the premium cost sometimes associated with lithium alternatives. Our report delves into the drivers sustaining this CAGR, analyzing how regulatory pressures and infrastructure upgrades contribute to steady demand across key verticals.
Segmentation Dynamics: Type and Application Insights
Understanding where value is generated within the market is crucial for targeted strategy. The market is primarily divided by type into stationary and motive power segments. The stationary segment larger share in 2025, driven by the relentless rollout of telecommunications infrastructure and renewable energy storage systems. Telecom operators rely heavily on gel batteries for base station backup due to their tolerance for varying temperatures and extended shelf life. Similarly, the renewable energy sector utilizes gel batteries to stabilize output from solar and wind installations, ensuring power availability during intermittent generation periods.
The application landscape further nuances this demand. Telecommunications and renewable energy storage represent significant pillars of consumption, absorbing substantial portions of production capacity. However, the others category remains a diverse and vital component, encompassing industrial machinery and specialized marine applications. Our analysis dissects these segments to identify which sub-verticals are experiencing the fastest adoption rates. While specific regional percentages are reserved for the full report to protect client confidentiality and encourage deeper engagement, the qualitative trend is clear: stationary applications are the primary engine of growth, supported by grid modernization efforts globally.
Regional Perspectives and Demand Hotspots
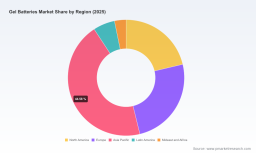
Geographically, the market exhibits varied maturity levels and growth potentials. Asia Pacific represents a significant volume driver, fueled by rapid industrialization and substantial investments in grid storage capabilities. North America and Europe continue to be mature markets where replacement cycles and sustainability regulations drive steady demand. Meanwhile, emerging regions in Latin America and the Middle East and Africa offer nascent but high-potential opportunities as infrastructure development accelerates.
Our research provides a granular view of these regional dynamics without limiting the scope to static market shares. Instead, we focus on the underlying economic and policy factors influencing regional adoption. For instance, government policy reports from 2025 indicate that carbon tax policies and emission reduction goals are driving industry-wide adoption of VRLA gel technology in multiple regions. This regulatory tailwind is particularly potent in Europe and parts of Asia, where compliance costs for less efficient technologies are rising. Understanding these regional policy landscapes is essential for companies planning supply chain logistics and market entry strategies.
Competitive Landscape: Key Players and Strategic Moves
The market concentration is moderate, with the top three companies holding approximately 48 percent of the market share and the top five controlling around 62 percent. This structure suggests a competitive environment where established giants coexist with specialized manufacturers capable of innovating quickly. Several key companies define the current landscape, each leveraging unique technological strengths.
Exide Technologies, headquartered in India, has long been a cornerstone of the market. Their focus on patented gel dryfit VRLA technology positions them strongly for deep-cycle applications including marine, equipment, and renewable energy storage. In February 2025, Exide Technologies announced a 100 million USD investment to expand gel battery manufacturing capacity, a direct response to demand surges from renewable energy and telecom sectors. This capital expenditure signals a strong commitment to capturing the forecasted growth in the 2026 to 2032 period.
Trojan Battery Company, based in the United States, maintains a strong foothold with deep-cycle gel batteries tailored for solar, marine, and off-grid renewable energy systems. Their product philosophy emphasizes longevity and reliability in remote settings, aligning with the needs of the expanding microgrid market. Similarly, East Penn Manufacturing offers the Deka Ready Power gel battery line, catering to both motive power and renewable applications, ensuring versatility across industrial and energy storage use cases.
In the industrial and telecom spheres, GS Yuasa Corporation of Japan provides gel lead-acid batteries optimized for industrial, renewable, and telecom energy storage. Their reputation for quality in extreme conditions makes them a preferred partner for critical infrastructure. Amara Raja Batteries, also based in India, contributes significantly with gel batteries for industrial and renewable energy storage solutions, leveraging local manufacturing capabilities to serve regional demand efficiently.
European influence remains strong through entities like Sonnenschein Batteries, which operates under the Exide Group umbrella. In January 2025, Sonnenschein Batteries unveiled a new high-capacity gel battery specifically for grid storage and renewable integration projects. This product launch highlights the industry trend toward higher capacity units capable of supporting utility-scale applications. Further west, Banner Batteries from Austria continues to supply gel batteries for industrial and renewable energy uses, maintaining high standards for European market compliance. Enersys, another United States-based player, focuses on gel battery technology for motive and stationary energy storage applications, bridging the gap between material handling equipment and fixed storage solutions.
Recent Developments and Innovation Trajectories
Innovation within the sector is not limited to established names. Recent developments indicate a broadening of technical capabilities. In February 2025, Narada Power opened a new R&D center in Shanghai dedicated to next-generation gel battery chemistry and manufacturing processes. This move underscores the importance of Asian R&D hubs in advancing global technology standards. Furthermore, in March 2025, Hoppecke Batteries launched a modular gel battery system for commercial EV fleets offering enhanced safety and lifecycle performance. This development illustrates the convergence of gel battery technology with electrification trends in transportation, expanding the potential addressable market beyond traditional stationary uses.
Regulatory Frameworks and Industry Dynamics
Navigating the regulatory environment is as critical as managing technology roadmaps. Battery Council International convened the first-ever meeting of its Sodium Battery Industry Group on May 4 2026 to advance standards for energy storage technologies including advanced lead-acid variants. While focused on sodium, this regulatory push signals a broader scrutiny and standardization effort across energy storage chemistries, which indirectly benefits established gel technologies by clarifying compliance pathways.
Sector Analysis indicates targeted renewable energy subsidies and grid code updates continue to support deployment of gel battery systems in utility-scale storage applications. These financial incentives lower the barrier to entry for large-scale projects, making gel batteries a financially viable option for utility planners. However, compliance is mandatory. ISO 9001 and ISO 14001 certifications are mandated for all gel battery production facilities to ensure quality and environmental compliance. Manufacturers failing to meet these standards face exclusion from supply chains in regulated markets.
Supply chain stability also hinges on critical mineral management. Lead remains the core critical mineral in gel batteries with ongoing mining and recycling efforts by major producers supporting supply chain stability. Investors and procurement officers must monitor these supply dynamics closely, as fluctuations in lead availability can impact production costs and margins. Our report evaluates these supply chain risks in detail, offering strategies for mitigating material volatility.
Tubular GEL Battery Market
Strategic Value of the PW Consulting Report
For executives and strategists, accessing detailed market intelligence is the first step toward informed decision-making. This report goes beyond surface-level data to provide actionable insights. It examines the intersection of policy, technology, and demand to forecast how the market will evolve. Readers will gain clarity on which applications are poised for expansion and where competitive intensity might compress margins.
The analysis of market concentration helps identify consolidation opportunities. With the top five players controlling over 60 percent of the market, there is a clear hierarchy. However, the presence of agile R&D centers and new product launches suggests that niche players can carve out profitable segments. Understanding where these opportunities lie requires the depth of analysis provided in our full study. We explore how companies like Exide and Trojan are adjusting their portfolios to meet the demands of 2026 and beyond, offering case studies on successful capacity expansions and product innovations.
Furthermore, the report addresses the risks associated with regulatory changes. As ISO mandates tighten and carbon policies evolve, manufacturers must adapt their processes. Our findings outline the compliance requirements necessary to maintain market access. For investors, this due diligence is invaluable in assessing the viability of potential partners or acquisition targets.
Conclusion: Positioning for the 2032 Horizon
The Gel Batteries Market is on a steady path of expansion, driven by the inherent advantages of the technology and supportive macroeconomic trends. The projected growth from 2.7 billion USD in 2026 to over 4 billion USD by 2032 offers substantial room for strategic maneuvering. However, realizing value in this market requires more than optimism; it demands precise intelligence on segmentation, competition, and regulatory shifts.
PW Consulting's comprehensive market research serves as an essential tool for navigating this landscape. By synthesizing historical data, forecasting future trends, and analyzing the moves of key competitors, we provide a foundation for robust strategic planning. Whether you are looking to invest in manufacturing capacity, enter new geographic regions, or develop next-generation storage solutions, the insights contained in this report are designed to guide your approach. The full depth of segmentation data, regional breakdowns, and competitive profiling is available through our complete study, ensuring you have the specific intelligence needed to lead in this evolving sector.
For detailed analysis of this topic, please visit the official page: Gel Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com