

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wedding Dress Market Hits $186M in 2025, Projected 6.08% CAGR Through 2032

Executive Overview: Strategic Imperatives in the Global Wedding Dress Market
The wedding dress market stands at a pivotal juncture in 2026. As consumer preferences shift towards personalization, sustainability, and experiential value, industry stakeholders must navigate a landscape defined by both resilient growth and intensifying competition. This comprehensive market research publication by PW Consulting offers a granular examination of the sector, designed to equip executives, investors, and strategic planners with the intelligence necessary to capitalize on emerging opportunities. The insights presented herein are not merely statistical aggregates; they represent a roadmap for navigating the complexities of supply chain dynamics, regional demand fluctuations, and competitive differentiation in the coming years.
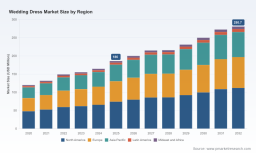
Our analysis covers the historical trajectory from 2020 through 2025, providing a robust baseline against which future projections are measured. The forecast period extends to 2032, allowing for long-term strategic planning. A central finding of this study is the projected Compound Annual Growth Rate (CAGR) of 6.08% during the forecast period. This indicates a sustained upward momentum, suggesting that the market is not only recovering from previous global disruptions but is also expanding beyond pre-pandemic benchmarks. The total market revenue is anticipated to reach significant milestones, surpassing the 280 million USD mark by the end of the forecast horizon, up from a base year value of 186.0 million USD in 2025. Such growth underscores the enduring cultural and economic significance of bridal wear, despite shifting demographics and economic pressures in various regions.
Market Trajectory and Growth Drivers
Understanding the velocity of market expansion is critical for capacity planning and investment allocation. The data indicates a consistent year-over-year increase in revenue, reflecting a market that is maturing yet still ripe for innovation. From a historical perspective, the sector demonstrated remarkable resilience, growing from 120.0 million USD in 2020 to 164.65 million USD by 2024. This recovery phase was characterized by a return to traditional ceremonies and a renewed appetite for conspicuous consumption in the bridal sector. As we move into 2026, the market size is projected to approximate 200.02 million USD, signaling a stabilization at higher valuation tiers.
Wedding Ring Market
The drivers behind this growth are multifaceted. Demographic shifts in key aging populations are being counterbalanced by rising marriage rates in emerging economies. Furthermore, the psychological shift towards "once-in-a-lifetime" spending, even amidst inflationary environments, supports the premiumization trend observed in recent quarters. However, growth is not uniform across all vectors. The industry is witnessing a bifurcation where mass-market availability competes with high-end bespoke services. Stakeholders must understand where their value proposition lies within this spectrum to optimize margin profiles. Our report delves into the specific catalysts fueling this expansion, including the rise of destination weddings, the influence of digitalmarketing on bridal retail, and the evolving lifecycle of wedding-related expenditures.
Structural Segmentation and Consumer Behavior
The architecture of the wedding dress market is defined by distinct segmentation channels that dictate go-to-market strategies. The report provides a detailed breakdown of the market by type, application, and region, offering clarity on where demand is concentrate d and how consumer behaviors diverge.
In terms of product type, the market is primarily split between off-the-rack solutions and customized offerings. While standardized inventory provides speed and accessibility, the customized segment represents a high-value opportunity for brands capable of delivering exclusivity. The data suggests a healthy equilibrium between these two streams, with each serving different consumer psychographics. Off-the-rack purchases appeal to cost-conscious and time-sensitive buyers, while customized gowns cater to those seeking unique design elements and a tailored fit. Understanding the margin implications and inventory risks associated with each type is essential for operational efficiency.
The application landscape further nuances this picture. Personal purchases remain the dominant force, driven by the bride's direct investment in her ceremony attire. However, the rental market constitutes a significant portion of revenue, reflecting a growing consciousness around sustainability and cost efficiency. Additionally, photographic studios represent a niche but steady demand channel, where dresses are purchased or rented specifically for imagery rather than ceremony use. Our analysis explores the elasticity of demand across these applications, helping businesses identify which customer segments offer the highest lifetime value and lowest churn risk.
Regional Dynamics and Global Supply Chains
Geography plays a decisive role in market performance. The report maps revenue distribution across major global regions, highlighting the disparities in market maturity and growth potential. North America continues to represent a substantial portion of global revenue, underpinned by a robust culture of elaborate wedding ceremonies and high disposable income levels. Europe follows as a mature market with strong historical ties to bridal fashion, characterized by a preference for luxury and heritage brands.
Wedding Dress Market
The Asia Pacific region presents a compelling growth story, driven by rising middle-class populations and the adoption of Western wedding traditions alongside local customs. Latin America and the Middle East and Africa regions, while currently smaller in total volume, offer high growth potential as economic conditions stabilize and the wedding industry professionalizes. For manufacturers and retailers, understanding these regional nuances is vital. Logistics costs, tariff structures, and local consumer preferences vary significantly. A strategy that works in North America may not translate directly to Eastern Europe or Southeast Asia. Our geographic analysis provides the context needed to tailor distribution networks and marketing messages to local realities without needing to rely on generic global assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment in the wedding dress market is fragmented yet features strong brand identities. Our research profiles a diverse array of key companies that define the current industry standards. These entities range from boutique American designers focusing on specific aesthetic niches to large-scale manufacturers based in Europe and Asia optimized for volume and wholesale distribution.
In the United States, the market is characterized by a strong presence of designer brands that emphasize American design and manufacturing. Companies such as Alyssa Kristin and Katherine Tash highlight the value proposition of domestic production, appealing to consumers who prioritize supply chain transparency and quality control. Similarly, brands like Anne Barge and Sareh Nouri focus on luxury bridal gowns, often produced in-house to maintain strict quality standards and design exclusivity. The high-end segment is further populated by established names like Vera Wang Bride and Morilee New York, which leverage iconic status to command premium pricing. Contemporary options are also well-represented by players like Justin Alexander and CINQ, who target the mid-to-high-end market with modern designs that resonate with younger demographics.
The competitive field extends beyond domestic boundaries. In Europe, Poland-based Pollardi Fashion Group stands out as one of the largest factories for wedding and evening dresses, indicating a strong manufacturing backbone in the region. Italy's Ricca Sposa maintains a position as a luxury bridal brand with significant wholesale presence, recently reinforcing its market visibility through participation in major industry events such as Barcelona Bridal Fashion Week in April 2026. In Asia, manufacturers like TEG (TEG Made) in China and Suzhou Leader Apparel Co., Ltd. provide premium bridalwear manufacturing services, catering to both branded labels and private label opportunities. Turkish manufacturer Metropol Wedding Dress and Chinese wholesaler BETANCY further illustrate the global supply chain's reliance on specialized manufacturing hubs capable of handling custom and wholesale volumes efficiently.
Recent developments highlight the proactive nature of these competitors. In 2026, several key players have intensified their presence at major trade shows and fashion weeks. Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, signaling a continued commitment to seasonal innovation. Allure Bridals held designer events including Once Upon a Dress in May 2026, reinforcing its brand engagement strategy. These activities are not merely promotional; they are strategic moves to secure buyer relationships and dictate trend directions. Our report analyzes how these competitive tactics influence market share and brand equity, providing a framework for assessing rival strategies.
Industry Context and Recent Developments
The operational context of the wedding dress market in 2026 is shaped by a combination of supply chain recalibration and consumer sentiment shifts. The industry is moving towards greater transparency and sustainability, a trend reflected in the product offerings of brands like LEIN, which focuses on sustainable and modern wedding dresses. This shift is not superficial; it impacts material sourcing, production timelines, and end-of-life considerations for garments. Companies that fail to adapt to these ethical expectations risk alienation from a growing segment of conscientious consumers.
Furthermore, the frequency of industry gatherings and collection launches remains high. The participation of companies like Ricca Sposa and Kaya Wedding in European and Barcelona bridal events during April 2026 underscores the importance of physical presence in building B2B and B2C relationships. These events serve as bellwethers for upcoming trends and color palettes. For market entrants or existing players looking to pivot, monitoring these calendars is essential. The data compiled in this study includes timelines of such key events and product launches, allowing strategists to align their own release cycles with market peaks.
Strategic Value of This Research
Access to granular data is the differentiator between reactive management and proactive strategy. This report is structured to provide actionable intelligence rather than abstract observations. It empowers stakeholders to identify white space opportunities, assess competitor vulnerabilities, and optimize pricing strategies. By integrating historical data with forward-looking projections, the document serves as a foundational tool for budgeting, hiring, and expansion planning.
The depth of segmentation analysis allows for precise targeting. Whether a company is looking to expand its rental inventory, invest in customized manufacturing capabilities, or enter a new geographic region, the data supports evidence-based decision-making. The competitive profiling extends beyond basic company descriptions to include an assessment of their offerings and recent strategic moves, enabling a clearer picture of the battlefield. Understanding the concentration of market power, reflected in the competitive metrics, helps in gauging the barrier to entry and the potential for consolidation.
Conclusion and Next Steps
The wedding dress market in 2026 offers a complex array of opportunities for those equipped with the right intelligence. Growth is sustained, but the path to capturing value requires a nuanced understanding of segmentation, regional dynamics, and competitive behavior. PW Consulting's detailed market research provides the comprehensive view necessary to navigate this environment successfully.
For executives and strategists who require the full depth of this analysis, including detailed segmentation splits, specific regional revenue figures, and exhaustive competitor matrices, we invite you to access the complete report. The executive summary provided here illustrates the scope and strategic relevance of the findings, but the full document contains the specific data points required to finalize investment cases and operational plans. Engage with the full dataset to transform industry insights into tangible business outcomes.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com