

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Wind Turbine Blade Market Hits $29.34B in 2025, Projected 6.53% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Wind Turbine Blade Market: Strategic Imperatives for 2026 and Beyond
The global energy transition is no longer a speculative narrative; it is a capital-intensive reality reshaping infrastructure portfolios worldwide. At the heart of this transformation lies the wind turbine blade, a critical component that dictates efficiency, longevity, and ultimately the levelized cost of energy. As we move through 2026, industry stakeholders face a complex matrix of technological innovation, regulatory pressure, and shifting geographic demand. This article serves as an executive overview of our latest comprehensive market research, designed to equip strategic decision-makers with the intelligence required to navigate this evolving landscape.
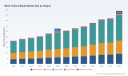
Our analysis indicates that the market has sustained a robust growth trajectory over the past half-decade. Valued at approximately 21.38 billion USD in 2020, the sector expanded steadily to reach 29.34 billion USD by 2025. This historical performance underscores the resilience of wind energy investments despite macroeconomic fluctuations. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market expected to surpass 45 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate that reflects sustained demand for both onshore and offshore capacity, driven by national renewable targets and corporate procurement strategies.
However, top-line figures only tell part of the story. The strategic value for enterprise leaders in 2026 lies in understanding the underlying dynamics propelling this growth. Our report dissects the market into critical dimensions, offering a granular view of where value is being created and where risks are consolidating. For instance, the shift towards larger rotor diameters and higher capacity turbines is altering material requirements and supply chain logistics. Similarly, the geographic redistribution of manufacturing hubs is responding to trade policies and localization mandates. Decision-makers must recognize that the market is not monolithic; it is a collection of distinct segments, each with its own profit pools and competitive intensities.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated turbine manufacturers and specialized blade suppliers. Our research identifies key players who are defining the standards for performance and sustainability. Companies such as LM Wind Power and Siemens Gamesa Renewable Energy remain pivotal, leveraging vertical integration and technological proprietary advantages to maintain market share. Vestas Wind Systems A/S continues to strengthen its position through strategic acquisitions, such as the recent expansion of its European manufacturing footprint, signaling a commitment to supply chain security and regional capacity.
Independent manufacturers like TPI Composites Inc. play a crucial role in the ecosystem, supporting multiple original equipment manufacturers across global facilities. Their ability to scale production, evidenced by significant production milestones reached in early 2025, highlights the importance of flexible manufacturing capabilities. Meanwhile, regional players in Asia and Europe, including Nordex SE, Enercon GmbH, and specialized Chinese manufacturers, are increasingly influential in shaping local market dynamics. The report provides detailed profiles of these entities, analyzing their strategic moves, capacity expansions, and partnership networks.
Market concentration remains a key metric for assessing competitive risk. The data suggests a moderately concentrated landscape where a handful of firms control a significant portion of revenue. Understanding the balance between integrated OEMs and independent suppliers is essential for procurement strategies and partnership evaluations. Our analysis explores how these relationships are evolving, particularly in the context of technology licensing and manufacturing alliances.
Technology and Sustainability: The New Battleground
Sustainability is transitioning from a corporate social responsibility initiative to a core operational requirement. The European wind industry has implemented a self-imposed landfill ban on decommissioned wind turbine blades effective January 2026. This regulatory milestone mandates that 100% of blades must be reused, recovered, or recycled. This shift places immense pressure on material science and end-of-life management strategies. Vestas has been proactive in this arena, aiming for full blade circularity by 2030 through initiatives like the CETEC project, which focuses on chemical disassembly processes for epoxy-infused blades.
Technological innovation is also accelerating in manufacturing processes. Advances such as additive manufacturing for blade molds, demonstrated through collaborations between industry leaders and national laboratories, are reducing production times and enabling more complex geometries. These developments offer potential efficiencies in cost and lead time, which are critical for meeting the aggressive installation targets set by governments globally. Siemens Gamesa's introduction of new offshore platforms exemplifies the push towards larger, more efficient turbines that can capitalize on offshore wind resources.
The report delves deep into these technological trajectories, evaluating their commercial viability and impact on cost structures. We assess the readiness levels of various recycling technologies and the potential for material redesign. For investors and product planners, understanding the timeline for these technologies to reach commercial scale is vital for long-term asset planning.
Market Dynamics and Regulatory Environment
The regulatory landscape is becoming increasingly complex, influencing both market entry and operational compliance. Beyond the European landfill ban, there are growing calls for Europe-wide regulations affecting large composite nacelle components. These regulations aim to standardize disposal practices and encourage circular economy principles across the industry. Companies operating in or exporting to these regions must align their product lifecycles with these emerging standards to avoid compliance risks and reputational damage.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Supply chain resilience is another critical dynamic. Geopolitical tensions and trade policies are prompting a reassessment of manufacturing locations. The data shows significant variation in regional market sizes, with Asia Pacific representing a substantial portion of global revenue, followed by Europe and North America. Each region presents unique challenges regarding logistics, labor costs, and local content requirements. Our study provides a comparative analysis of these regions, helping stakeholders optimize their geographic footprint without exposing sensitive strategic details prematurely.
Furthermore, the interaction between policy incentives and market demand creates volatility that requires agile strategic planning. Government subsidies, tax credits, and renewable portfolio standards vary significantly by jurisdiction. The report maps these policy frameworks against market growth projections to identify high-potential markets and potential bottlenecks.
What This Report Delivers for Your Organization
This market research is not merely a data compilation; it is a strategic toolkit designed for C-suite executives, investment managers, and product strategists. The full report offers detailed segmentation analysis across multiple dimensions, allowing you to isolate specific growth vectors relevant to your business unit. We provide historical data series that establish a reliable baseline for forecasting, alongside forward-looking estimates that account for scenario variations.
Readers will gain access to comprehensive profiles of key market participants, including their strategic focus, recent developments, and competitive positioning. This intelligence is crucial for benchmarking, merger and acquisition due diligence, and partnership identification. The analysis of recent industry events, such as major production milestones and facility acquisitions, provides context for understanding current market momentum.
Importantly, the report addresses the operational implications of sustainability mandates. We evaluate the cost implications of recycling technologies and the potential for new revenue streams from blade repurposing. This perspective is essential for companies looking to turn regulatory compliance into a competitive advantage. The insights provided are intended to support capital allocation decisions, R&D prioritization, and supply chain optimization.
Conclusion: The Path Forward
As the wind turbine blade market matures, the window for strategic advantage narrows. Success in 2026 and beyond will depend on the ability to anticipate technological shifts, navigate regulatory complexities, and optimize global operations. The data indicates a clear upward trend in market value, but realizing this potential requires nuanced understanding and precise execution.
Wind Turbine Blade Market
Our full market research report provides the depth and granularity needed to make informed decisions. It moves beyond general trends to offer specific, actionable intelligence tailored to the needs of industry leaders. We invite you to access the complete study to unlock the detailed segmentation data, comprehensive competitor analysis, and strategic recommendations that will define your approach in this critical sector. The insights contained within are designed to empower your organization to lead rather than follow in the renewable energy transition.
For detailed analysis of this topic, please visit the official page: Wind Turbine Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precision Gear Market Reaches $1.14B in 2025, Booms at 6.5% CAGR to $1.77B by 2032
By pmarketresearch, 2026-09-15
Precision at Scale: Navigating the High Precision Planetary Gear Reducers Market Through 2032
Executive Overview: A Market at the Intersection of Precision and Scale
The high precision planetary gear reducers market stands at a critical inflection point where mechanical engineering excellence meets accelerating industrial automation. As manufacturing ecosystems grow increasingly demanding in terms of torque density, positioning accuracy, and operational reliability, precision reducers have transitioned from peripheral components to mission-critical enablers of next-generation motion systems. This strategic intelligence briefing distills the core findings of our latest High Precision Planetary Gear Reducers Market research, offering decision-makers a structured foundation for capacity planning, technology roadmapping, and competitive positioning through 2032.
The market has demonstrated consistent expansion over the past half-decade, with assessed baseline valuations climbing from approximately 832 million USD in 2020 to a projected threshold near 1.14 billion USD in 2025. Forward-looking assessments indicate sustained momentum, with the market expected to reach roughly 1.2 billion USD in 2026 and continue its upward trajectory toward approximately 1.77 billion USD by 2032. The compound annual growth rate across the forecast horizon is estimated at 6.5 percent, reflecting a mature yet highly dynamic landscape where incremental efficiency gains, application diversification, and regional deployment shifts collectively shape demand curves. These figures represent aggregate market direction rather than isolated performance snapshots, underscoring the importance of segment-level intelligence for precise investment allocation.
Strategic Drivers Reshaping Demand Architecture
The underlying demand architecture for high precision planetary gear reducers is being reconfigured by three interlocking forces: automation intensity, precision tolerance escalation, and system integration complexity. Industrial motion control is no longer defined solely by load capacity; contemporary applications require reducers that maintain rigorous backlash thresholds, exhibit predictable thermal behavior under sustained duty cycles, and integrate seamlessly with servo architectures and digital control ecosystems. As servo-enabled automation platforms accelerate their penetration across discrete and process manufacturing, precision gear reduction has become a foundational requirement rather than an optional upgrade.
Parallel to this, the proliferation of advanced manufacturing infrastructure continues to elevate the baseline for mechanical accuracy. Updated transmission precision guidelines, including the 2024 revision of ISO 6336-1, now emphasize more stringent dynamic testing under thermal equilibrium conditions, establishing new benchmarks for validation, quality assurance, and supplier qualification. In this environment, organizations that rely on component-level uncertainty face heightened exposure to integration risk, warranty exposure, and production downtime. Understanding where precision requirements are tightening, and which engineering pathways are proving most scalable, is essential for supply chain resilience and product roadmap alignment.
Robot Joint Precision Reducers Market
Regional Demand Emergence and Competitive Reconfiguration
Demand dispersion across geographic markets is not uniform, nor is it static. Maturity, industrial mix, and capital investment cycles produce distinct regional demand signatures that influence volume absorption, pricing tolerance, and supplier localization strategies. Our analysis indicates that Asia Pacific currently anchors the largest share of market valuation, reflecting the scale of advanced manufacturing deployment, robotics integration, and industrial equipment production across the region. North America and Europe continue to represent structurally important markets, driven by high-value automation modernization, precision engineering ecosystems, and localized service expectations that reward reliability, responsiveness, and engineering support depth.
At the same time, Latin America and the Middle East and Africa are emerging as incremental growth theaters where industrial modernization programs, infrastructure investment, and re-shoring considerations are gradually expanding addressable demand. The strategic implication for global suppliers is not simply to chase aggregate volume, but to calibrate regional go-to-market models according to local application profiles, lead-time sensitivity, and after-sales service expectations. In practice, this requires differentiated assembly footprints, inventory positioning, and engineering localization strategies rather than a one-size-fits-all export approach.
Recent operational developments already illustrate how leading players are adapting to these regional realities. SEW-EURODRIVE, for example, has moved to establish local assembly capabilities for its P2.e planetary gear units in South Carolina, compressing lead times for cataloged ratios to as little as six weeks. Such localization actions are not merely logistical adjustments; they represent strategic commitments to service velocity, regional demand capture, and supply chain risk diversification. Meanwhile, Shanghai SGR Heavy Industry Machinery Co., Ltd. has used major industry exhibitions to showcase its N-series planetary gear reducers, emphasizing alloy steel formulations, multi-planetary load distribution design, and targeted applications in new energy yaw and pitch control systems. These releases reflect broader market trends in which precision transmission components are increasingly tied to new energy infrastructure, heavy automation, and specialized motion platforms.
Technology Roadmapping and Application Complexity
Within the broader market, product differentiation is increasingly defined by precision class, gearing architecture, and suitability for specific motion profiles. Right angle and linear planetary gear reducer families both command substantial market relevance, but their value propositions diverge across application scenarios. Right angle configurations remain critical where spatial constraints and shaft orientation requirements dictate compact torque transfer, while linear planetary designs are increasingly favored in precision actuation and positioning workflows that demand repeatable motion accuracy and predictable load distribution.
Industry stakeholders must also recognize that application diversity is not merely a segmentation detail; it is a strategic signal. Robotics remains one of the most prominent demand centers, where high precision planetary gear reducers enable torque control, joint accuracy, and compact packaging for increasingly capable manipulator systems. Industrial manufacturing continues to drive broad-based demand through CNC machine tools, packaging equipment, conveyors, and material handling automation. Semiconductor equipment represents a more specialized but strategically important application corridor, where ultra-clean environment compatibility, rigidity, and micron-level positioning control can determine end-equipment performance. Additional application domains further extend the addressable base, spanning medical device manufacturing, specialized automation platforms, and precision test and measurement systems.
The strategic insight for procurement, R&D, and product management teams lies in mapping these application requirements to the correct precision tier and mechanical configuration. Over-specifying where tolerance requirements are moderate erodes margin, while under-specifying in high-precision workflows creates integration fragility. Our research examines how leading engineering teams are aligning specification decisions with real duty cycles, thermal load scenarios, and lifecycle cost models rather than nominal catalog values alone.
High Precision Planetary Gear Reducers Market
Competitive Intensity and the Imperative of Differentiation
The competitive landscape for high precision planetary gear reducers is shaped by a concentrated but heterogeneous set of manufacturers, each pursuing distinct differentiation pathways. Europe remains home to several influential engineering-led suppliers, including Neugart GmbH, Wittenstein SE, SEW-EURODRIVE, and Stober Antriebstechnik GmbH, all of which emphasize low-backlash performance, high rigidity, and application-tailored design philosophies. NEUGART's Economy and Precision Line series, for instance, reflect a dual-track strategy that serves both cost-sensitive motion control deployments and applications requiring elevated precision. WITTENSTEIN's portfolio, spanning low-backlash servo gearboxes and hygienic-design variants, illustrates the market's need for specialized configurations in demanding operating environments. SEW-EURODRIVE continues to extend its industrial and servo offerings with high-torque planetary gear units, reinforcing its positioning in heavy-duty automation contexts.
In the Americas and Asia, competitive dynamics are increasingly defined by integration capability, servo application specialization, and scale-driven precision manufacturing. Apex Dynamics Inc. has built a reputation around helical gearing approaches that deliver low backlash and high torque in servo applications, while Harmonic Drive LLC has advanced zero-backlash performance concepts that align closely with robotics and precision actuation requirements. Sumitomo Heavy Industries and Nidec-Shimpo contribute complementary strengths in integrated drive technologies and compact motion control, respectively. In China, the competitive field includes Shanghai SGR Heavy Industry Machinery Co., Ltd., Hubei Planetary Gearboxes Co., Ltd., and Ningbo ZhongDa Leader Intelligent Transmission Co., Ltd., each targeting precision automation, industrial robotics, and intelligent transmission system development through localized engineering resources and expanding manufacturing capabilities. ZF Friedrichshafen AG, meanwhile, applies transmission heritage to precision planetary gear reducers across automotive and industrial contexts, highlighting the cross-pollination of engineering competencies across end markets.
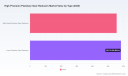
Market structure analysis indicates that the top three players account for approximately 25 percent of assessed market value, while the top five collectively represent roughly 35 percent. This level of moderate concentration suggests a market in which scale incumbents hold meaningful advantage, but where specialized differentiation, application expertise, and regional responsiveness still create viable pathways for competitive success. The practical implication is that competitive strategy cannot rely on volume positioning alone. Suppliers must simultaneously invest in precision consistency, engineering support, lead-time reliability, and application-specific validation to protect share and expand margin.
Regulatory and Standards Evolution as Strategic Context
Standards evolution and measurement rigor are becoming more consequential for commercial competitiveness. ISO 6336-1:2024 updates have introduced more demanding dynamic testing expectations under thermal equilibrium, directly affecting how manufacturers validate gear quality and how system integrators assess supplier reliability. In parallel, broader industry signals reinforce the scale of precision motion demand. Global industrial robot installations reached 590,000 units in 2023, and more than 62 percent of those installations incorporated high precision planetary gear reducers for torque control and precise motion. Servo-based automation adoption grew by 13.4 percent in 2024 according to VDMA reporting, while machine tool export performance in Japan exceeded 10.7 billion USD in 2023, signaling sustained global investment in precision manufacturing infrastructure.
For corporate strategists, these dynamics carry two implications. First, compliance and validation capability are increasingly part of commercial differentiation; suppliers that can demonstrate test rigor, thermal stability, and documented quality systems are better positioned in qualification processes. Second, macro demand indicators provide directional confirmation that precision transmission remains embedded in broader automation expansion, reinforcing the case for long-cycle planning rather than short-term transactional positioning.
What the Research Delivers for Strategic Planning
This High Precision Planetary Gear Reducers Market report is designed to support actionable decision-making across strategy, product management, sales planning, and supply chain leadership. Beyond aggregate market sizing and forecast trajectories, the study provides structured analysis that allows organizations to benchmark their strategic assumptions, refine segment targeting, and anticipate demand shifts with greater confidence.
The report examines market segmentation from multiple operational angles, giving readers clarity on how demand is distributed across type and application categories, where growth is most concentrated, and which structural factors are likely to influence share movement over time. It also provides regional analysis that contextualizes demand intensity, local manufacturing dynamics, and localization implications for suppliers seeking to optimize service models and inventory positioning. Competitively, the research profiles the strategic posture, engineering focus, and recent moves of leading participants, helping readers interpret not just who is active in the market, but how rivals are positioning themselves for sustained relevance.
In addition, the analysis incorporates recent corporate developments and industry context that shape near-term market behavior. Trade show activity, local manufacturing expansions, standards revisions, and robotics and automation demand indicators are integrated into the narrative to help stakeholders connect strategic planning with on-the-ground developments. The objective is to provide a usable intelligence base for capacity planning, market entry evaluation, supplier selection, pricing strategy, and product roadmap alignment.
Recommended Strategic Actions for 2026 and Beyond
As organizations move from market awareness to action, several strategic priorities emerge. First, firms should strengthen precision validation and thermal-performance documentation to align with evolving standards expectations and integrator qualification requirements. Second, regional service models should be revisited in light of lead-time sensitivity and localized assembly trends, particularly where rapid delivery and application support are becoming competitive differentiators. Third, application-specific engineering engagement should be deepened, because value capture increasingly depends on matching reducer configuration to actual duty cycles, not catalog optimization alone.
Fourth, competitive positioning should account for moderate market concentration by balancing scale efficiency with differentiated expertise in key application areas such as robotics, industrial manufacturing, and precision equipment. Fifth, organizations should use forecast visibility through 2032 to inform investment pacing, ensuring that capacity, R&D, and go-to-market resources are aligned with the demand curve rather than reacting to it after the fact. In a market expanding toward a projected valuation approaching 1.77 billion USD by the end of the forecast period, disciplined strategic planning will separate durable participants from transient competitors.
Closing Perspective
The high precision planetary gear reducers market is not simply expanding; it is maturing into a more technically demanding, regionally nuanced, and competitively layered environment. Sustained growth at a 6.5 percent compound annual rate through 2032 signals continued relevance, but it also raises the bar for precision, reliability, localization, and engineering support. Organizations that treat precision reducers as strategic enablers rather than commodity components will be better positioned to capture value, reduce integration risk, and build durable supplier relationships across the automation ecosystem.
This intelligence briefing offers a high-level view of the terrain, but the full report provides the granular segmentation, regional valuations, application-level breakdowns, competitive benchmarking, and forecast scenarios necessary for precise strategic execution. For leadership teams seeking to translate market direction into operational decisions, the complete analysis can be accessed through the source report page, where the full dataset, detailed segmentation insights, and company-level assessments are available for review.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nitrogen Gas Springs Market to Grow 5.7% CAGR, Reaching $657.3M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in a Pressurized Market: The 2026 Nitrogen Gas Springs Industry Outlook
The industrial tooling landscape is undergoing a period of significant recalibration. As manufacturers navigate post-pandemic supply chain realities, shifting regulatory frameworks, and the relentless push toward Industry 4.0 integration, the nitrogen gas spring market has emerged as a critical focal point for operational efficiency and capital allocation. At PW Consulting, we recognize that understanding this market requires more than surface-level trend tracking. It demands a granular, forward-looking analysis that translates macroeconomic signals into actionable strategic directives.
Nitrogen Gas Springs Market
Our latest comprehensive market research publication, launched to support enterprise decision-making throughout 2026 and beyond, delivers precisely that capability. This article serves as a strategic primer, outlining the analytical architecture, competitive intelligence framework, and operational dynamics that define the study. We will examine why this research represents a critical asset for procurement leaders, strategic planners, and market expansion teams operating in the precision tooling sector. For executives who require the complete quantitative matrices, regional breakdowns, and deep-scenario modeling, the full report is available for immediate access through our research portal.
The Grand Trajectory: Mapping the 2026–2032 Forecast Horizon
The nitrogen gas springs market has demonstrated remarkable resilience and structural growth over the past half-decade. Drawing upon a rigorous historical dataset spanning 2020 through 2025, our analysis captures the full arc of market evolution—from the contraction pressures observed in 2021, through the steady recovery and expansion that defined the mid-to-late 2020s. By the close of the base year, the market had firmly established a momentum baseline that positions it for sustained appreciation across the forecast horizon.
Our forward-looking projections extend through 2032, charting a clear upward trajectory that underscores the sector's fundamental attractiveness. The compound annual growth rate anchored at 5.7 percent reflects a mature yet dynamically expanding ecosystem, driven by incremental adoption in precision stamping, injection molding, and advanced industrial machinery. Importantly, this growth narrative is not merely a linear extrapolation. It is the product of layered scenario modeling that accounts for technological adoption curves, capital expenditure cycles in end-user industries, and the gradual normalization of raw material supply chains.
Revenue figures, denominated in USD millions, illustrate a market that has consistently scaled beyond the 400 million threshold in recent years and is positioned to surpass critical psychological and operational milestones in the coming years. The projection curve reveals acceleration points that coincide with broader industrial modernization waves, particularly in regions where automation investment is reaching inflection. For strategic planners, these trajectory markers provide essential baseline parameters for capacity planning, supplier negotiations, and long-term inventory strategy. The complete temporal decomposition, including year-by-year variance intervals and sensitivity ranges, is fully detailed within the report's forecasting modules.
Architecture of the Analysis: What the Report Delivers
PW Consulting's market study is structured to function as an operational decision-support system rather than a static reference document. Every section has been engineered to address the concrete questions that arise during quarterly strategic reviews, M&A screening, and portfolio optimization exercises. The report's architecture encompasses several core pillars designed to give readers immediate tactical utility.
Granular Segment Mapping and Cross-Functional Overlay
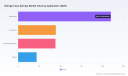
The analysis disaggregates the market across multiple structural dimensions, allowing stakeholders to isolate performance drivers and identify high-yield opportunity corridors. Type-based segmentation traces the evolution of standard, compact, super compact, and micro nitrogen gas spring categories, examining how force ranges, footprint constraints, and application specificity are reshaping purchasing criteria. Application-level analysis evaluates demand concentration across automotive, aerospace, industrial machinery, and specialty sectors, highlighting where production volume aligns with margin expansion potential.
Regional demand architecture is similarly decomposed, mapping consumption intensity, growth velocity, and supply chain proximity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. By avoiding simplistic aggregation, the report enables readers to assess regional attractiveness through a multi-factor lens that weighs industrial base maturity, regulatory exposure, logistics complexity, and competitive saturation. All quantitative splits, share distributions, and absolute valuation figures for each segment and sub-segment are exclusively available in the full data appendix.
Gas Spring Market
Competitive Intelligence and Strategic Positioning Frameworks
The competitive landscape section moves beyond roster enumeration to deliver actionable profiling of the market's leading participants. Each profiled enterprise is evaluated across capability depth, geographic footprint, product architecture, innovation cadence, and commercial positioning. The analysis situates players within a broader competitive topology, identifying where scale advantages, technological differentiation, or distribution reach create defensible market positions.
Among the organizations subjected to this detailed scrutiny are DADCO Inc., Special Springs s.r.l., Hyson Products Inc., Pascal Engineering Corporation, KALLER, Bordignon S.r.l., Isotech Inc., Gemini Gas Springs Inc., AZOLGAS, and FIBRO GmbH. The report examines how each entity constructs its value proposition, responds to segment-specific demands, and navigates the tension between standardized catalog offerings and custom engineering engagements. For readers evaluating partnership opportunities, benchmarking their own positioning, or assessing acquisition targets, this competitive mapping provides an essential reference framework. The full profile set, complete with capability matrices and strategic assessment summaries, is contained in the proprietary competitive intelligence section of the report.
Competitive Landscape and Innovation Vectors
The nitrogen gas springs market is characterized by a moderately concentrated structure, with the top three participants collectively commanding a significant share of total revenue and the top five firms consolidating an even larger portion of industry output. This concentration pattern reflects the capital intensity of manufacturing, the importance of certification compliance, and the value that end-users place on supply reliability and technical support. At the same time, the presence of specialized domestic producers and niche innovators ensures that competitive pressure remains dynamic across both premium and cost-sensitive segments.
Innovation in this market is increasingly oriented toward digitalization, safety enhancement, and environmental resilience. DADCO Inc. garnered attention in early 2025 with the introduction of an IoT-enabled nitrogen gas spring series featuring integrated pressure and temperature monitoring, explicitly designed to support Industry 4.0 die tooling architectures. This move signals a broader industry shift where gas springs are no longer viewed merely as passive mechanical components but as intelligent nodes within connected manufacturing systems. The ability to monitor performance in real time, predict maintenance intervals, and optimize press cycles represents a tangible value-add that forward-looking OEMs are beginning to mandate.
On the safety and durability frontier, Special Springs s.r.l. advanced its product portfolio through multiple strategic updates throughout 2025. The launch of the Skudo-Flex accessory addressed cylinder longevity and operational safety in heavy-duty stamping environments, while the subsequent release of a new US Series catalog and an enhanced reducer component expanded the firm's capacity to perform in contaminated operating conditions. The company also rolled out a Fair Kit initiative to strengthen its trade exhibition presence, reinforcing its commitment to direct market engagement and customer education. These initiatives illustrate how sustained R&D investment, catalog expansion, and targeted commercial activation converge to build competitive moats.
Other market participants continue to differentiate through complementary vectors. Hyson Products Inc. maintains a full-line approach encompassing high-force configurations, slow-return variants, and contamination-resistant models tailored to metal stamping dies and injection molds. Pascal Engineering Corporation emphasizes precision and safety in mini and standard gas springs for stamping and molding applications, serving manufacturers who prioritize component quality as a productivity multiplier. KALLER has carved out a distinct position with high-temperature variants engineered to withstand operating conditions up to 250°C, addressing the demands of hot stamping processes. Bordignon S.r.l. leverages decades of heritage—dating back to 1958—to compete on longevity, reliability, and incremental innovation in stamping and forming applications. Isotech Inc. and Gemini Gas Springs Inc. extend the competitive field with steel and stainless steel offerings and in-house manufactured lift supports that meet stringent industrial standards, respectively. Meanwhile, AZOLGAS provides extensive catalog breadth for metal stamping and multi-technology industrial use, and FIBRO GmbH supports time-sensitive procurement with an expansive standard catalog and central European warehousing that enables same-day delivery.
Together, these players illustrate a market where competitive advantage is derived from a blend of engineering rigor, application-specific customization, digital readiness, and supply chain responsiveness. For enterprises evaluating supplier selection or attempting to anticipate competitor moves, the report's competitive analysis section decodes these positioning strategies in detail.
Structural Dynamics and the Operating Environment
No market analysis is complete without a rigorous examination of the external forces that shape supply, demand, and compliance risk. The nitrogen gas springs sector operates within a regulatory and materials environment that directly influences product specifications, production economics, and market access.
Regulatory Architecture and Standards Compliance
The standards landscape for nitrogen gas springs is defined by a cohesive set of international and regional requirements that establish baseline expectations for safety, performance, and interchangeability. ISO 11901-5:2021 specifies that nitrogen is the exclusive gas permitted for charging gas springs in stamping die applications, mandating commercial-grade nitrogen in purity class 5.0. This standard, alongside the broader ISO 11901 framework governing dimensions, forces, and safety instructions for press tools and dies, creates a harmonized technical baseline that manufacturers must satisfy to operate in global markets.
In the European context, compliance with the Pressure Equipment Directive (PED 2014/68/EU) remains mandatory for nitrogen gas springs deployed in machinery and tooling applications. Additionally, mounting dimensions and interchangeability specifications are shaped by VDI 3003 and CNOMO standards, which define mechanical interfaces critical to industrial stamping operations. These regulatory and standards-driven requirements function as both a barrier to entry and a quality signal, reinforcing the market position of firms that have invested in certified production processes and comprehensive documentation capabilities. The report's dynamics section examines how compliance costs, certification timelines, and standards evolution influence competitive accessibility and regional market entry strategies.
Raw Material Volatility and Cost Transmission
The economics of nitrogen gas spring manufacturing are materially influenced by steel price dynamics. Supply chain disruptions, geopolitical tensions, and demand-side fluctuations continue to inject volatility into raw material markets, with direct consequences for production costs and margin stability. Firms that maintain diversified sourcing strategies, forward-contracting arrangements, or value-engineered material specifications are better positioned to absorb cost shocks without eroding competitiveness. The analysis explores how cost transmission mechanisms vary across product categories and customer segments, and how procurement strategy can be aligned with broader market timing to optimize input cost exposure. Detailed cost-structure benchmarks, sensitivity coefficients, and sourcing scenario evaluations are provided in the full report's operational economics modules.
Strategic Implications for 2026 Decision-Makers
Translating market intelligence into executable strategy requires connecting high-level trends to organizational capabilities and constraints. For executives operating in or adjacent to the nitrogen gas springs market, several strategic imperatives emerge from the evidence base assembled in this study.
First, the growth trajectory and segment dynamics suggest that disciplined portfolio allocation will outperform undifferentiated expansion. Firms that map their product and service offerings to the application and type segments demonstrating the strongest alignment between demand growth, margin potential, and competitive accessibility will be best positioned to capture disproportionate value. The report's segment-level decomposition provides the diagnostic foundation for such allocation decisions.
Second, the competitive landscape analysis underscores the enduring importance of differentiation in a moderately concentrated market. While scale and distribution provide baseline advantages, sustained leadership increasingly depends on targeted innovation, whether in digital monitoring capabilities, high-temperature performance, contamination resistance, or rapid fulfillment infrastructure. Companies that treat product architecture as a strategic variable rather than a static attribute will uncover opportunities to premiumize their offerings and deepen customer lock-in.
Third, regulatory and materials dynamics introduce both risk and opportunity. Companies that proactively align their engineering and compliance functions with the evolving standards environment reduce the likelihood of market access disruptions and position themselves as trusted partners to risk-averse end-users. Simultaneously, effective raw material management—through supplier diversification, inventory optimization, and design-for-cost initiatives—can transform input volatility from a margin threat into a competitive differentiator.
Finally, the industry's movement toward connected, intelligent tooling components signals that the definition of value in this market is expanding. The integration of monitoring, data capture, and predictive capabilities into nitrogen gas spring products reflects a broader shift in which suppliers are expected to contribute to their customers' operational intelligence. Organizations that anticipate this shift and invest accordingly will be better positioned to capture the next wave of demand growth.
Accessing the Full Intelligence Package
This article has outlined the scope, methodology, and strategic relevance of PW Consulting's Nitrogen Gas Springs Market research, highlighting the structural trends, competitive dynamics, and operational considerations that will shape decision-making throughout 2026 and into the 2032 forecast horizon. The narrative presented here is intentionally high-level, designed to demonstrate the analytical rigor and practical applicability of the study while preserving the proprietary depth that delivers maximum value to our clients.
The complete report contains exhaustive year-by-year market sizing, detailed segment splits, regional revenue distributions, competitive capability matrices, scenario-based forecasts, and operational benchmarking data. Every quantitative insight referenced in this overview, along with granular sub-segment performance indicators and strategic recommendation frameworks, is fully documented within the publication. For procurement executives, strategy directors, market analysts, and investment professionals who require the full evidentiary base to support capital allocation, supplier negotiation, and market entry decisions, the complete report is available for immediate access. We invite you to consult the full intelligence package to ensure your 2026 planning is grounded in the most comprehensive and strategically actionable market analysis available.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational Toys Market to Hit $48.23 Billion by 2032, 8.47% CAGR
By pmarketresearch, 2026-09-15
The Educational Toys Market: Strategic Intelligence for 2026 and Beyond
The landscape of childhood development is undergoing a profound transformation, driven by shifting pedagogical priorities, technological integration, and an increasing recognition of play as a fundamental vehicle for learning. For executives navigating the consumer goods and education sectors, the Educational Toys Market represents not merely a niche segment but a critical battleground for future growth. As we move through 2026, the decisions made today regarding product portfolios, supply chain resilience, and compliance frameworks will determine market leadership over the next decade.
PW Consulting is pleased to present our comprehensive market research report on the Educational Toys Market, designed to equip stakeholders with the actionable intelligence required to capitalize on emerging opportunities. This analysis provides a rigorous examination of market trajectories, competitive pressures, and regulatory shifts that define the current operating environment from 2026 through 2032.
Market Trajectory and Macro Dynamics
Understanding the broader economic footprint of the Educational Toys Market is the first step in strategic planning. Historical analysis reveals a sector characterized by steady, resilient expansion. Between 2020 and 2025, the market exhibited robust growth, with revenue climbing from 19.2 Billion USD to 27.24 Billion USD. This trajectory underscores the increasing willingness of parents, educators, and institutions to invest in products that blend entertainment with developmental outcomes.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. The market is expected to reach 29.13 Billion USD in 2026, accelerating towards 48.23 Billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 8.47%, signaling a healthy expansion phase that outpaces many traditional consumer discretionary categories. For strategic planners, this indicates sustained demand elasticity, provided that products align with evolving consumer expectations regarding safety, educational efficacy, and digital integration.
However, raw growth figures only tell part of the story. The structure of this growth is fragmented across diverse product types, application scenarios, and geographical regions. While aggregate numbers suggest optimism, the distribution of value across these segments reveals distinct strategic priorities. Certain application areas are already demonstrating higher revenue concentrations, suggesting where consumer spending is most heavily directed, while regional variances highlight differences in market maturity and regulatory environments. Identifying which specific categories are driving the bulk of this expansion requires a granular analysis that goes beyond top-line estimates.
Report Scope and Operational Utility
Our report is structured to move beyond theoretical market sizing and provide practical tools for business decision-making. The analysis covers a historical window from 2020 to 2025 to establish baseline trends, followed by a forecast period extending to 2032. This longitudinal view allows organizations to distinguish between temporary pandemic-era anomalies and structural shifts in purchasing behavior.
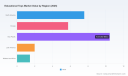
The research encompasses a detailed segmentation analysis across three primary dimensions: product types, application contexts, and regional markets. By dissecting the market along these axes, we enable clients to identify high-potential niches that may be obscured in aggregate data. The report examines the specific revenue contributions of categories ranging from motor skills and arts and crafts to STEM-focused products and role-play instruments. Similarly, the application landscape is analyzed to distinguish between early childhood development needs, formal school curriculum integration, and other usage scenarios. Regional breakdowns further clarify where growth is most pronounced, allowing for targeted geographic expansion strategies.
A critical component of this research is the evaluation of market concentration. Current metrics indicate that the top three players hold a 30.0% share of the market, while the top five control 40.0%. This level of concentration suggests a moderately consolidated landscape where dominant incumbents wield significant influence over pricing, distribution, and brand perception. However, the remaining market share is distributed among a diverse array of specialists and innovators, creating opportunities for agile entrants who can differentiate through niche expertise or technological innovation.
To ensure the highest level of strategic utility, the report incorporates profiles of key market participants. These profiles examine the specific educational offerings, product portfolios, and strategic positioning of leading companies. By understanding the strengths and focus areas of competitors such as major construction toy specialists, interactive electronics manufacturers, and STEM curriculum providers, organizations can better anticipate competitive moves and identify gaps in the market.
Educational Toys Market
Competitive Landscape: Incumbents and Innovators
The competitive dynamics of the Educational Toys Market are shaped by a mix of legacy toy giants and specialized educational technology firms. Each player brings a distinct value proposition, ranging from mass-market brand recognition to targeted pedagogical solutions.
Among the established leaders, companies like Mattel, Inc. and The LEGO Group maintain strong positions by leveraging iconic brands and extensive distribution networks. Mattel offers a wide range of educational toys including construction sets, STEM learning products, and interactive play items. The LEGO Group, including its dedicated LEGO Education division, specializes in construction-based educational toys and STEM sets designed for scientific discovery and creativity. Notably, in January 2026, LEGO Education launched new STEM sets for children aged 7 and above designed to inspire curiosity, exploration, and scientific discovery, signaling a continued commitment to the older end of the youth demographic. Ravensburger AG also contributes to this competitive sphere, offering wooden puzzles, board games, and STEM building sets for cognitive development.
Hasbro, Inc. rounds out the major incumbent group with a focus on educational games, role-playing sets, and STEM-oriented toys for skill development. These large-scale players benefit from economies of scale and brand loyalty, but they also face pressure to innovate rapidly in response to technology-driven competitors.
On the electronics and interactive learning side, VTech Holdings Ltd. and LeapFrog Enterprises, Inc. are pivotal. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development. LeapFrog develops interactive electronic learning toys and books that combine technology with early education. In May 2025, LeapFrog showcased its latest collection of educational toys, including the Strum & Count Wooden Guitar, at Toy Fair 2025, highlighting a strategy that blends traditional tactile play with musical and cognitive learning. JAKKS Pacific, Inc. further complements this segment by manufacturing educational electronic toys and interactive STEM products.
The market is also seeing significant activity from specialized innovators. Osmo, Inc. offers interactive tablet-based educational games and learning kits for ages 3-11, bridging the gap between physical manipulatives and digital interfaces. MindWare, Inc. focuses on hands-on learning tools and manipulatives for science, math, and critical thinking, appealing to parents and educators seeking rigorous cognitive development tools. Spin Master Corp. provides STEM and interactive educational toys, including licensed educational lines, while Melissa & Doug, LLC specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers, catering to the demand for screen-free, age-appropriate products. Tomy Company, Ltd. from Japan develops educational construction toys, robotics, and STEM learning products, adding a strong international dimension to the competitive field.
Recent developments underscore the pace of innovation and the need for vigilance. In October 2025, STEMPlay Labs launched Wonder Briks and PictoMath, patent-pending construction bricks and math tools for STEM play, demonstrating how new entrants are targeting specific learning outcomes with proprietary technology. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational toy lines for children ages 1-13 to align with modern developmental needs, reflecting a trend toward granular age segmentation. Conversely, regulatory scrutiny remains high. In March 2026, ZMC Group recalled multiple light-up toys due to battery ingestion hazards violating toy safety standards, a reminder of the operational risks associated with product safety compliance.
Regulatory Dynamics and Compliance Imperatives
For strategic planners, the regulatory environment is as critical as market demand. The Educational Toys Market is subject to stringent safety and quality standards that vary significantly across jurisdictions and are currently undergoing substantial updates.
In the United States, the Consumer Product Safety Commission (CPSC) has taken decisive action. On December 12, 2025, the CPSC published its final rule on Safety Standard for Toys: Requirements for Water Beads. This rule takes effect on March 12, 2026, and holds particular significance because it codifies requirements directly into 16 CFR Part 1250 rather than updating ASTM F963. This structural change implies a more rigid regulatory framework that manufacturers must integrate into their compliance systems immediately.
Across the Atlantic, the European Union has introduced the new Toy Safety Regulation 2025/2509, published on December 12, 2025. This regulation enters into force on January 1, 2026, and will apply fully on August 1, 2030. A standout feature of this regulation is the introduction of a digital product passport requirement for all toys, enhancing traceability and compliance. For companies operating in or exporting to the European market, this necessitates investment in digital infrastructure and supply chain transparency that goes beyond traditional labeling requirements. Failure to adapt to these requirements could result in significant market access barriers and reputational damage.
Educational Furniture Market
These regulatory shifts are not isolated events; they are part of a broader trend toward heightened consumer protection and ingredient transparency. Organizations must factor compliance costs, lead times, and potential reformulation needs into their product roadmaps. The interaction between rapid product innovation and rigorous safety testing creates a strategic tension that must be managed carefully to avoid recalls or market exclusion.
Strategic Imperatives for 2026 and Beyond
As the Educational Toys Market progresses through 2026, several strategic imperatives emerge for market participants. First, the divergence in growth rates across product types and applications demands a nuanced portfolio strategy. Companies cannot rely on a one-size-fits-all approach; instead, they must align product development with the specific developmental needs and purchasing behaviors of their target segments. Whether focusing on early childhood development, school curriculum integration, or other applications, the value proposition must be clearly articulated and substantiated.
Second, the competitive landscape requires continuous vigilance. The presence of both massive incumbents and agile innovators means that market share can shift quickly. Monitoring the product launches, patent activities, and strategic expansions of key players is essential for anticipating competitive pressure. The recent launch activities by LEGO Education, STEMPlay Labs, and Smart Kids Planet illustrate the diversity of innovation happening in real time, from new STEM sets for older children to patent-pending construction tools and expanded age-specific lines.
Third, regulatory compliance must be treated as a strategic capability rather than a back-office function. With the U.S. water beads rule already in effect and the EU digital product passport requirement looming, companies that proactively embed compliance into their design and manufacturing processes will gain a competitive advantage. This is particularly relevant for products involving electronics, small parts, or novel materials, where safety risks are heightened.
Finally, geographic strategy must account for regional differences in market maturity, consumer preferences, and regulatory frameworks. While some regions currently represent larger revenue pools, others may offer higher growth potential or less saturated competitive environments. Understanding the specific dynamics of North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa is crucial for optimizing market entry and expansion efforts.
Conclusion
The Educational Toys Market stands at a pivotal juncture, characterized by robust growth, intense competition, and evolving regulatory demands. The data indicates a market expanding from 27.24 Billion USD in 2025 to a projected 48.23 Billion USD by 2032, driven by a CAGR of 8.47%. However, realizing value in this environment requires more than awareness of these aggregate figures; it demands deep segmentation analysis, competitor intelligence, and a proactive approach to compliance.
PW Consulting's full market research report provides the detailed segmentation splits, regional revenue breakdowns, and granular application-level data necessary to construct a precise strategic roadmap. By accessing the complete report, organizations can uncover the specific growth velocities of individual product categories, identify the exact revenue contributions of each region, and benchmark their positioning against the detailed profiles of market leaders. We invite you to explore the full intelligence suite to ensure your 2026 decisions are grounded in comprehensive, actionable insight.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prefab Bathroom Pods Market to Hit $12.59 Billion by 2032, CAGR 9.4%
By pmarketresearch, 2026-09-15
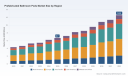
Strategic Intelligence for a Modular Future: Inside the Prefabricated Bathroom Pods Market Research 2026
The construction industry is rapidly shifting toward offsite manufacturing, and the bathroom pod segment stands at the center of this transformation. Over the past half-decade, the global market for prefabricated bathroom pods has evolved from a niche acceleration tool into a mainstream procurement strategy for developers, contractors, and facility owners. Our latest market research, covering the historical window from 2020 through 2025 and projecting forward to 2032, provides decision-makers with a structured, evidence-based view of where this sector is heading and how to position for it.
Prefabricated Security Booth Market
This article previews the strategic architecture of the study and explains why its findings matter for corporate planning in 2026. The goal is not to deliver every numerical cut in a single page, but to demonstrate the depth of the analysis, the rigor of the methodology, and the actionable frameworks embedded throughout the full report.
Market Trajectory: From Fragmented Growth to Consolidated Scale
The market has demonstrated steady, compounding expansion over the recent historical period. Revenue grew from approximately 4.32 billion USD in 2020 to 6.7 billion USD by 2025, reflecting both the increasing acceptance of modular construction and the broader push toward schedule compression, labor efficiency, and quality control. Looking ahead, the forecast period from 2026 to 2032 projects continued acceleration, with the market expected to reach 7.24 billion USD in 2026, cross the 10-billion threshold by 2030, and approach 12.59 billion USD by 2032. The compound annual growth rate anticipated across the forecast window sits at 9.4 percent, signaling a sector that is outpacing many traditional construction subsectors.
Such a trajectory cannot be understood through a single lens. Growth is being pulled by multiple overlapping forces: the urgency to reduce on-site labor dependency, the maturation of factory-controlled quality systems, and the growing mandate for repeatable, code-compliant interior units that can be delivered in volume. At the same time, the market remains structurally attractive because it rewards early positioning in manufacturing capacity, logistics networks, and regional partnership ecosystems. The research unpacks how these dynamics interact across the forecast horizon, providing executives with a defensible basis for capacity planning, M&A screening, and route-to-market decisions.
Structural Drivers Shaping the 2026 Decision Environment
Several operational and regulatory forces are now firmly embedded in the market's behavior, and the study connects them directly to commercial outcomes.
- Schedule compression and labor economics. Prefabricated bathroom pods can accelerate project timelines by 40 to 50 percent while reducing on-site workforce needs compared with traditional stick-built methods. For programs where schedule risk carries heavy financial penalties, that performance edge has moved from a bonus to a requirement.
- Code compliance as a competitive moat. Manufacturers increasingly design units that align with local building codes, including International Building Code and IRC frameworks, as well as plumbing regulations, to ensure factory readiness for final on-site inspection. The research examines how compliance readiness affects bidder qualification, procurement preference, and project risk allocation.
- Fire and loss-prevention standards. Loss Prevention Standards such as LPS 1207 now require fire-retardant coverings for temporary packaging and protective materials used during transport and storage of modular bathroom units. This detail matters for logistics planning, packaging design, and supplier qualification, and the report maps it against operational workflows.
- Material performance trade-offs. Steel-based pods continue to hold a strong position in the product mix, with industry data indicating a category share near 34.7 percent, supported by structural strength that enables faster installation and load-bearing capacity for multi-story applications. At the same time, GRP bathroom pods are emerging as a preferred option for their lightweight properties, corrosion resistance, and reduced maintenance requirements relative to traditional materials. The full analysis compares these material pathways across cost, durability, installation speed, and end-market fit.
Report Coverage: What Decision-Makers Will Find Inside
The full market research is built for practical use rather than abstract description. It is designed to support market entry assessments, product-line planning, bidding strategy, and regional expansion analysis. Below is a structured overview of what the study delivers.
Market Sizing and Forecasts
The report presents historical and forecast revenue data across the 2020 to 2032 window in USD billions, with a clearly defined base year, historical period, and forecast horizon. Rather than offering a single top-line number, the analysis separates the market into actionable segments so that executives can identify where growth is concentrated and where competitive intensity is rising.
Segmentation That Supports Planning
The study breaks the market down by region, by type, and by application. These views help teams answer questions such as which geographic markets are expanding most rapidly, how product categories are positioned against each other, and which end-use sectors are driving demand for modular bathroom units. The regional discussion covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The product-type view contrasts GRP bathroom pods, steel bathroom pods, and other variants. The application view distinguishes residential, commercial, and additional use cases. Percentages and localized revenue figures are reserved for the full report, where they can be examined alongside competitive context and demand drivers.
Competitive Landscape and Positioning
The research profiles leading manufacturers and maps how each player competes on production capacity, product design, regional reach, and vertical integration. Representative companies include Walker Modular in the United Kingdom, Offsite Solutions in the United Kingdom, Bathsystem S.p.A. in Italy, Interpod in Australia, SurePods in the United States, BAUDET in France, B&T Manufacturing in the United States, Hydrodiseño in Spain, Durapods in the United States, and Loom Crafts in India. These profiles do not stop at company descriptions; they connect manufacturing approaches, product architectures, and target sectors to the broader competitive structure of the market, including concentration indicators that show how share is distributed among top players.
Recent Developments and Strategic Signal
The study integrates recent company-level activity to show how the competitive field is moving in real time. Recent developments captured in the research include Offsite Solutions' February 2026 introduction of a next-generation steel-framed bathroom pod line with modular design elements that allow customization of layouts and finishes while preserving manufacturing efficiency. The same analysis tracks BAUDET's March 2026 project deliveries across multiple hotel modernizations and student residence projects, including work with the Louvre Hotels Group in Paris as well as student residence projects in Saint-Étienne and Caen. The report also notes broader industry events, such as Southwest Solutions Group's April 2026 participation in modular construction and restroom solutions events, showcasing code-compliant prefabricated bathroom pods for fast deployment. Together, these developments illustrate how product innovation, project wins, and industry engagement are reshaping market positioning.
Commercial and Operational Frameworks
Beyond sizing and profiling, the research provides decision frameworks for evaluating manufacturing readiness, compliance alignment, logistics complexity, and demand quality by segment. These frameworks are intended to help teams convert market intelligence into procurement choices, capacity investment plans, and partnership strategies. The full report also includes the analytical detail needed to compare product types, applications, and regions side by side without relying on generic industry narratives.
Why This Research Matters for 2026 Strategy
The 2026 decision environment calls for more than directional confidence. Organizations need to know not only that the market is expanding, but where the growth is coming from, who is capturing it, and what operational capabilities separate scalable players from the rest. The compound annual growth rate of 9.4 percent across the forecast period indicates a sector large enough to attract continued investment, yet fragmented enough that strategic positioning still matters.
For manufacturers, the research supports decisions about production capacity, material mix, customization depth, and regional expansion. For developers and contractors, it clarifies where prefabricated bathroom pods can reduce schedule risk and labor exposure, and how compliance and packaging requirements shape supplier selection. For investors and advisors, it provides the segmentation structure and competitive context needed to evaluate market entry opportunities, consolidation potential, and differentiation pathways.
Prefabricated Bathroom Pods Market
The study is also designed to help teams avoid a common trap: assuming that growth in the aggregate automatically translates into growth for every sub-segment. By separating region, type, and application, the analysis shows where demand is durable, where it is contingent on specific project types, and where competitive overlap is intensifying. That level of granularity is essential in a market where the top three players account for roughly 55 percent of revenue and the top five account for about 68 percent, implying that scale, reputation, and repeat procurement relationships carry significant weight.
What the Full Report Delivers Beyond This Preview
This article is intentionally a framework overview rather than a data dump. The complete market research goes further by providing the detailed segmentation values, regional revenue profiles, product-type comparisons, and application-level demand patterns that executives need for precise planning. It also includes the supporting analysis behind the concentration structure, the competitive profiles, and the recent development timeline.
Readers who want the full strategic picture can access the complete report on our website, where the data tables, segment commentary, company profiles, and development timelines are presented together in a format built for internal discussion and decision-making. The preview above is meant to establish the logic of the analysis and the quality of the evidence, while leaving the specific figures and segment cuts for the full publication.
Closing Perspective
Prefabricated bathroom pods are no longer an alternative construction method; they are becoming a core component of how commercial, residential, healthcare, hospitality, and institutional projects are delivered. The market's recent growth, its projected trajectory through 2032, and the operational advantages embedded in factory-built units all point to a sector that will continue to reward disciplined strategy. This research is designed to give leadership teams the clarity to act on that opportunity with confidence.
For organizations planning investments, procurement shifts, or competitive positioning in 2026, the full market research provides the segmentation detail, competitive context, and development signals needed to move from observation to execution. The complete analysis is available through our official report page, where the underlying market data, company profiles, and strategic frameworks can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Prefabricated Bathroom Pods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium-Sulfur Battery Market to Hit $262.8M by 2032, 25.7% CAGR
By pmarketresearch, 2026-09-15
The Lithium-Sulfur Imperative: Strategic Intelligence for the 2026 Market Inflection
The energy storage landscape is undergoing a structural transformation. After years of incremental improvements in lithium-ion chemistry, the industry is pivoting toward next-generation architectures that promise to decouple performance from cost. Among these, lithium-sulfur technology has moved from laboratory promise to commercial urgency. Our latest market research, spanning historical analysis from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032, captures this transition at precisely the moment when capital allocation, supply chain strategy, and product roadmaps are being locked in for the next decade.
For executives navigating 2026 investment decisions, this report is not a retrospective exercise. It is a decision-support instrument designed to separate signal from noise in a rapidly consolidating landscape where incumbents, startups, and strategic partners are simultaneously racing to scale production, secure raw material advantages, and comply with evolving regulatory frameworks. The insights within are structured to inform go-to-market timing, partnership evaluation, R&D prioritization, and risk hedging across aerospace, automotive, defense, consumer electronics, and stationary storage verticals.
Market Trajectory and the Shape of the Opportunity
The macroeconomic arc of the lithium-sulfur market tells a story of accelerating adoption. Historical revenue tracking from 2020 through 2025 reveals a compounding growth curve that has consistently outpaced earlier projections. The baseline year of 2025 closes at a meaningful inflection point, setting the stage for a forecast period in which the market is projected to expand at a compound annual growth rate of 25.7 percent through 2032. By the end of the forecast window, total market revenue is expected to reach a scale that fundamentally reshapes how investors, OEMs, and policy makers evaluate advanced battery technologies.
This trajectory is not linear extrapolation. It reflects the convergence of multiple structural drivers: the relentless pursuit of higher gravimetric energy density, the economic logic of sulfur-based cathode chemistry, and a regulatory environment that increasingly rewards domestically sourced and low-carbon battery architectures. For strategic planners, the implication is clear. The window for first-mover advantage in specific application segments is narrowing, and the cost of delayed entry is rising as manufacturing capacity begins to materialize and downstream customers start locking in multi-year supply agreements.
What This Report Delivers: An Operational Roadmap
Our research is built around actionable intelligence rather than high-level commentary. Readers will find a comprehensive breakdown of market sizing across the full forecast horizon, with revenue projections calibrated to technology readiness levels, application adoption curves, and regional manufacturing dynamics. The segmentation architecture examines the market through multiple lenses, including type differentiation that distinguishes high-energy-density configurations from lower-density variants, and a detailed application mapping that spans aerospace, automotive, consumer electronics, defense, and energy storage systems.
Beyond sizing, the report delivers a granular competitive landscape analysis. We profile the companies actively shaping the lithium-sulfur ecosystem, evaluating their technological approaches, manufacturing strategies, partnership footprints, and recent commercial moves. The analysis captures the diversity of engineering pathways currently under evaluation, from proprietary three-dimensional graphene architectures and sulfurized-carbon cathodes to nano-encapsulated sulfur formulations, polymer-host anode designs, and thin glass-protected lithium-metal anodes. This comparative framework allows decision makers to benchmark competitor positioning, anticipate consolidation patterns, and identify white spaces where differentiated offerings can command premium positioning.
The report also integrates a forward-looking view of industry dynamics. Regulatory developments, incentive structures, raw material economics, and supply chain considerations are woven into the analysis so that readers can stress-test their strategies against realistic assumptions. This includes an examination of how carbon footprint declaration requirements for industrial rechargeable batteries are reshaping procurement criteria in Europe, how investment tax credit eligibility for hybrid battery energy storage systems continues to support project economics in the United States through 2035, and how long-duration storage cost targets are creating new demand signals for advanced chemistries.
Competitive Architecture: The Battlefield of Lithium-Sulfur Innovation
The competitive field is defined by a mix of well-capitalized startups, specialized technology developers, research institutions, and strategic corporate partners. Several themes emerge from our analysis. First, the race to achieve commercially viable energy density at scale is attracting significant capital and corporate attention. Companies are pursuing divergent technical routes, each with distinct trade-offs in cycle life, manufacturability, safety, and cost structure. This fragmentation is both a risk and an opportunity: it signals that the winning architecture has not yet been universally settled, but it also means that monitoring technical differentiation is essential for partnership and investment decisions.
Lithium-Metal Secondary Battery Market
Recent corporate activity underscores the urgency. In 2025, one of the leading participants began U.S. production of battery-grade lithium-metal foil, a move that completes a localized supply chain for lithium-sulfur batteries and reduces exposure to cross-border component risks. That same company followed with a next-generation drone propulsion system built around American-made lithium-sulfur batteries, targeting national security and defense use cases, and subsequently secured more than 200 million dollars in additional equity investment to accelerate manufacturing expansion and acquisitions. In early 2026, the company entered a binding agreement to acquire a European battery recycling plant, signaling a strategic push to expand lithium-sulfur manufacturing capacity while integrating circular economy considerations into the value chain.
Automotive interest is also crystallizing. A major global automaker announced a joint development agreement with a sulfurized-carbon cathode specialist to co-develop lithium-sulfur EV battery cells with higher gravimetric energy density, an early indicator that large-volume OEMs are moving from observation to active co-engineering. Meanwhile, multiple developers are publicly targeting energy density thresholds that would meaningfully extend electric vehicle range, enable new aviation concepts including eVTOL platforms, and improve the economics of stationary storage deployments. These targets span a wide range, from cell-level configurations approaching 380 Wh/kg to advanced platforms aiming for substantially higher densities, reflecting the breadth of technical ambition in the sector.
Research institutions and government-funded programs remain critical enablers. Several organizations are advancing cycle life and energy density improvements with Department of Energy backing, while pilot production facilities are bridging the gap between laboratory breakthroughs and pilot-scale manufacturing. This ecosystem dynamic means that competitive intelligence must extend beyond commercial manufacturers to include the research and pilot infrastructure that will shape future supply options and technology licensing opportunities.
Market Dynamics: Regulation, Economics, and Supply Chain Realignment
The commercial viability of lithium-sulfur batteries is being shaped as much by policy and input economics as by technical progress. In Europe, regulatory requirements now mandate carbon footprint declarations for industrial rechargeable batteries exceeding 2 kWh capacity, a development that rewards manufacturers with transparent, low-carbon supply chains and creates a compliance differentiator for domestically sourced production. In the United States, the continuation of investment tax credit eligibility for hybrid battery energy storage systems through 2035 sustains project-level economics that favor advanced storage deployments, indirectly supporting demand for higher-performance battery chemistries in stationary applications.
Raw material economics provide another layer of strategic advantage. Sulfur cathode active material costs in lithium-sulfur batteries are reported at approximately 7 cents per kWh, roughly one-third of the equivalent input cost in conventional lithium-ion architectures. This cost asymmetry is a fundamental argument for the long-term competitiveness of the chemistry, particularly in cost-sensitive applications where energy density and material affordability must be balanced. Coupled with domestic sourcing pathways for sulfur and lithium-metal anodes that support tariff-free manufacturing, the input cost structure creates a credible route to price competitiveness as scale increases.
On the demand side, public-sector cost targets are sharpening focus. The Department of Energy's long-duration storage shot aims to reduce the levelized cost of storage to 5 cents per kWh by 2030 through advanced battery technologies, including lithium-sulfur platforms. While this target spans multiple technology pathways, it signals a clear policy direction: advanced chemistries that can deliver low levelized cost at scale will be prioritized in procurement, incentive design, and research funding. For companies and investors, aligning product roadmaps with these cost trajectories is becoming a strategic necessity rather than an optional optimization.
Decision Framework for 2026 and Beyond
As the market moves from early commercialization into a phase of capacity expansion and application-specific scaling, strategic decisions must be grounded in a clear understanding of where value will accrue. Several considerations should guide executive planning. First, the concentration of market share among leading participants remains moderate, indicating that the sector is still in a competitive formation stage rather than a mature oligopoly. This creates room for new entrants, targeted acquisitions, and differentiated positioning, but it also requires disciplined analysis of which technical and commercial pathways are most likely to achieve scale.
Second, application segmentation will not converge uniformly. Aerospace and defense use cases prioritize energy density and supply chain security, automotive applications demand cost-competitive scaling and integration with existing vehicle architectures, and stationary storage deployments weigh levelized cost, cycle life, and regulatory compliance. Our segmentation analysis helps decision makers map these differing requirements to realistic adoption timelines and revenue opportunities, avoiding the trap of treating lithium-sulfur as a single-market proposition.
Third, supply chain strategy is becoming a competitive moat. Companies that can localize critical inputs, integrate recycling capacity, and align with regulatory requirements around carbon transparency are building advantages that extend beyond cell performance. The recent moves toward domestic lithium-metal foil production, European recycling capacity acquisition, and tariff-free input sourcing illustrate how supply chain design is now inseparable from technology strategy.
Why This Research Matters Now
The 2026 to 2032 forecast window is not a distant planning exercise. It is the period during which manufacturing capacity, customer qualification cycles, regulatory compliance costs, and partnership structures will be established. Decisions made in 2026 regarding technology bets, supplier relationships, geographic focus, and application prioritization will determine competitive positioning for the remainder of the decade. Our report is designed to provide the depth, structure, and forward-looking context needed to make those decisions with confidence.
The full study goes beyond summary indicators to deliver the detailed segmentation data, company profiles, regulatory impact assessments, and scenario-based revenue projections that strategic teams require. It is built for executives who need to translate market momentum into concrete action: where to invest, whom to partner with, which applications to prioritize, and how to position against a rapidly evolving competitive set. The macro trajectory is compelling, the technical pathways are diversifying, and the regulatory and cost environment is increasingly favorable. The critical question for 2026 is no longer whether lithium-sulfur batteries will matter, but how decisively an organization will act to capture its share of the opportunity.
Lithium-Sulfur Battery Market
For detailed analysis of this topic, please visit the official page: Lithium-Sulfur Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: eNVM Market to Hit $344.8M by 2032, CAGR 11.54% Driven by Automotive
By pmarketresearch, 2026-09-15
Navigating the Embedded Non-Volatile Memory Landscape: Strategic Intelligence for 2026 and Beyond
The semiconductor industry is currently witnessing a paradigm shift in how data is stored, retained, and accessed at the edge. As artificial intelligence moves from the cloud to the device and connectivity becomes ubiquitous, the demand for resilient, high-performance memory solutions has never been more critical. Embedded Non-volatile Memory (eNVM) stands at the forefront of this transformation, serving as the foundational backbone for microcontrollers, systems-on-chips, and specialized processors. For stakeholders navigating the complex terrain of 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research report on the Embedded Non-volatile Memory Market. This document serves as a deep dive into the forces shaping the industry, offering a roadmap for decision-makers who need to align their portfolios with emerging realities. The following insights provide a preview of the strategic value contained within the full study, designed to equip you with the clarity needed to act decisively in a rapidly evolving ecosystem.
The Macro Outlook: Growth Trajectories and Valuation
The financial narrative of the eNVM sector is defined by robust expansion and sustained momentum. Based on extensive historical analysis spanning 2020 through 2025 and a detailed forecast period extending to 2032, the market demonstrates a compelling growth story. The overall market size has shown consistent appreciation over the last half-decade, reflecting the increasing integration of memory into diverse electronic systems. By 2025, the market had solidified its position as a critical component of the semiconductor value chain, with valuation trends indicating a strong upward curve.
Looking toward the forecast horizon from 2026 to 2032, the projected Compound Annual Growth Rate (CAGR) underscores the vitality of this sector. The data suggests that the market will continue to expand at a pace that outpaces many traditional semiconductor segments. This growth is not linear but is driven by specific technological inflection points and adoption waves across key industries. The revenue projections through the early 2030s indicate a market that is not only growing in value but also in strategic importance, as non-volatile storage becomes integral to the functionality of smart devices, autonomous systems, and industrial automation.
Technology Segmentation and Application Diversity
The eNVM landscape is not monolithic. It is characterized by a diverse array of technologies, each catering to specific performance, power, and cost requirements. The market is primarily segmented by technology type, with established solutions like embedded Flash and EEPROM maintaining significant footholds. However, the periphery of this segment is where the most dynamic innovation is occurring. Emerging technologies such as Resistive RAM (ReRAM), Magnetoresistive RAM (MRAM), Phase Change Memory (PCM), and Ferroelectric RAM (FRAM) are gaining traction, driven by the need for lower power consumption, higher endurance, and faster write speeds.
Each technology type solves a specific set of engineering challenges. For instance, while traditional flash remains dominant in certain cost-sensitive applications, next-generation non-volatile memories are becoming essential for high-performance computing and harsh environment operations. The report provides a granular analysis of these technology splits, examining the revenue contributions and growth vectors for each category. It explores how the shift from standard CMOS pathways to specialized fabrication processes influences the viability and adoption rates of these newer memory formats.
Beyond technology, the application landscape is a key driver of demand. The automotive sector represents a substantial portion of the market, fueled by the electrification of vehicles and the rise of advanced driver-assistance systems. Consumer electronics continue to be a steady contributor, driven by the proliferation of smart home devices and wearables. Meanwhile, the Internet of Things (IoT) and industrial sectors are emerging as critical growth engines, requiring memory solutions that can withstand extreme conditions and support edge computing capabilities. The research detailed in this report dissects these application verticals, highlighting the unique memory requirements and adoption trends within each domain.
Geographic Dynamics and Regional Influence
Geographic factors play a pivotal role in the distribution and consumption of eNVM solutions. The market is globally distributed, with significant concentration in key regions that host major semiconductor fabrication capabilities and end-market demand. Asia Pacific remains a dominant force, reflecting the region's extensive manufacturing infrastructure and large consumer base. North America and Europe follow, each with distinct market characteristics driven by local industrial policies, automotive hubs, and technological innovation centers.
Automotive Embedded Storage (eMMC and UFS) Market
Emerging regions, including Latin America and the Middle East and Africa, also contribute to the global footprint, though at different scales. The report analyzes these regional dynamics to help stakeholders understand where demand is concentrated and where supply chain vulnerabilities may exist. Understanding the geographic flow of eNVM products is essential for supply chain optimization and market entry strategies. The full study provides a detailed regional breakdown, offering insights into local market sizes and growth rates without exposing the raw segmentation data publicly, ensuring that our clients gain a competitive edge through exclusive access to precise figures.
Embedded Non-volatile Memory (eNVM) Market
Competitive Landscape and Key Industry Players
The competitive arena of the eNVM market is populated by a mix of established semiconductor giants, specialized memory manufacturers, and foundry service providers. The market concentration metrics indicate a landscape where no single entity holds absolute dominance, allowing for a dynamic environment of innovation and strategic partnerships. The CR3 and CR5 ratios suggest a moderately fragmented but highly competitive space, where differentiation is achieved through technology leadership and integration capabilities.
Samsung Electronics continues to be a formidable presence, developing and manufacturing embedded STT-MRAM and flash eNVM solutions for MCUs, SoCs, and high-performance applications. Their ability to scale advanced memory technologies positions them as a key enabler for next-generation devices. STMicroelectronics has carved a niche by integrating embedded PCM and RRAM eNVM into 18nm FD-SOI MCUs, specifically targeting automotive and industrial use cases where reliability is paramount. Similarly, Infineon Technologies provides embedded FRAM and RRAM eNVM in automotive AURIX controllers and edge ML microprocessors, reinforcing the link between memory technology and functional safety.
NXP Semiconductors delivers embedded MRAM eNVM in 16nm FinFET automotive MCUs developed with TSMC, showcasing the importance of foundry partnerships in enabling advanced node integration. Renesas Electronics offers embedded STT-MRAM and flash eNVM for industrial and IoT MCUs, addressing the needs of smart infrastructure and automation. Texas Instruments supplies embedded ferroelectric and flash eNVM in MCUs and processors, maintaining a broad portfolio that serves diverse customer bases. Microchip Technology manufactures embedded flash and NOR eNVM for embedded systems and MCUs, focusing on reliability and extensive product availability.
On the innovation frontier, companies like Weebit Nano are licensing embedded ReRAM IP for integration into foundry platforms such as 130nm BCD and 22nm nodes. Their recent activities highlight the momentum in IP licensing models. In April 2025, Weebit Nano demonstrated chips integrating embedded ReRAM in DB HiTek's 130nm BCD process for mixed-signal and high-voltage applications. Earlier in the year, they qualified ReRAM IP for Sky Water Technology's 130nm CMOS platform and secured a licensing agreement with onsemi for integration into the Treo platform targeting automotive and industrial applications. Everspin Technologies has also expanded its PERSYST MRAM portfolio with high-reliability products qualified for automotive and aerospace, including the EM064LX HR and EM128LX HR.
Foundry partners play a crucial role in this ecosystem. TSMC embeds MRAM and ReRAM eNVM directly into advanced 22nm and 12nm FinFET processes for MCUs and SoCs, enabling customers to access cutting-edge memory integration. GlobalFoundries integrates embedded MRAM and ReRAM eNVM into 12nm and 22FDX platforms for high-reliability designs, catering to sectors that demand exceptional performance under stress. These collaborations between memory IP providers, device manufacturers, and foundries are essential for overcoming the integration complexity that characterizes this market.
Industry Dynamics: Challenges and Enablers
The path to widespread eNVM adoption is not without obstacles. High manufacturing costs and complex integration processes for eNVM require specialized fabrication equipment that diverges from standard CMOS pathways. This divergence can create barriers to entry and influence cost structures for end products. Embedding eNVM into next-generation SoCs requires unique layout designs, extra IP blocks, and extended verification periods that extend development timelines. These factors necessitate careful planning and investment from companies looking to incorporate advanced memory solutions into their designs.
Regulatory and qualification standards also shape the market dynamics. Automotive and industrial eNVM products must meet AEC-Q100 Grade 1 qualification with operation from -40°C to +125°C and minimum 10-year data retention. Meeting these stringent requirements adds to the complexity and cost but is non-negotiable for safety-critical applications. Additionally, radiation-hardened embedded NVM options require specialized material platforms and testing processes to meet aerospace and high-reliability standards. These certification and qualification hurdles serve as moats for established players while creating opportunities for those who can navigate the regulatory landscape efficiently.
Geopolitical factors also influence the market. Chinese semiconductor foundries such as SMIC and UMC actively supply embedded MRAM and ReRAM eNVM to global manufacturers. This supply chain diversification has implications for risk management and sourcing strategies. Companies must balance the benefits of access to advanced technology with the need to mitigate geopolitical risks and ensure supply chain resilience. The report delves into these dynamics, providing context on how external forces impact market structure and strategic decision-making.
Strategic Value of the Full Report
While the overview above highlights the breadth of the eNVM market, the full PW Consulting report offers depths that are essential for precise strategic planning. This document is not merely a collection of data points; it is a strategic tool designed to answer the critical questions facing executives, product managers, and investors. How will the shift toward edge AI impact memory requirements? Which technology nodes will dominate the automotive sector in the next five years? Where are the highest growth opportunities for IP licensors versus device manufacturers?
The report includes detailed financial models, technology roadmaps, and competitive profiling that allow readers to benchmark their positions against industry leaders. It provides actionable insights on supply chain optimization, partnership opportunities, and R&D prioritization. For those involved in mergers and acquisitions, the market concentration data and growth trajectories offer valuable context for valuation and due diligence. For product developers, the analysis of integration complexity and qualification requirements can inform design-in decisions and time-to-market strategies.
By accessing the complete study, stakeholders can move beyond general trends to specific, data-backed conclusions. The full report contains the meticulous segmentation by type, application, and region that allows for targeted market sizing and revenue forecasting. It explores the nuances of regional policies, local manufacturing capabilities, and consumption patterns that drive global trade flows. This level of detail is crucial for avoiding generic strategies and instead implementing plans that are tailored to the specific realities of the eNVM ecosystem.
Conclusion: Positioning for the Future
The Embedded Non-volatile Memory Market is poised for significant transformation as we move through 2026 and beyond. The convergence of IoT, automotive electrification, and edge computing is creating a perfect storm of demand that rewards innovation and strategic foresight. Companies that can navigate the complexities of technology integration, manage supply chain risks, and align their offerings with the evolving needs of end markets will be best positioned to capture value in this growing sector.
PW Consulting's latest market research report on eNVM is designed to be your companion in this journey. It provides the intelligence needed to make informed decisions, mitigate risks, and identify opportunities that might otherwise remain hidden in the noise of a rapidly changing industry. We invite you to access the full report to unlock the comprehensive data and analysis that will empower your organization to lead in the era of embedded intelligence. The future of memory is being written now, and with the right insights, you can ensure your strategy is aligned with the trajectory of growth and innovation.
For detailed analysis of this topic, please visit the official page: Embedded Non-volatile Memory (eNVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Fuel Cell GDL Market Hits $2B in 2025, Surges to $4B by 2032 at 13.18% CAGR
By pmarketresearch, 2026-09-15
Navigating the Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Intelligence for 2026 and Beyond
The transition toward net-zero economies has placed hydrogen fuel cells at the center of global decarbonization strategies. Within the intricate architecture of a proton exchange membrane fuel cell, the Gas Diffusion Layer serves as a critical interface between the flow field and the catalyst layer. This thin, porous component is responsible for distributing reactant gases evenly, managing water removal, and facilitating electron transport. As the industry scales from niche applications to mass deployment, the Gas Diffusion Layer market has emerged as a high-stakes battleground for materials science, supply chain resilience, and strategic positioning.
PW Consulting's latest market research publication provides a comprehensive, data-driven analysis of this evolving landscape. Designed for executives, investors, and strategic planners, this report dissects the market dynamics, competitive structures, and technological shifts that will define the sector through 2032. The following analysis outlines the core insights and strategic value embedded within the full study, offering a clear preview of the intelligence required to navigate the complexities of 2026 and the forecast period ahead.
Market Trajectory and Growth Dynamics
The hydrogen economy is transitioning from policy-driven pilots to commercially viable deployments. This shift is reflected in the robust expansion of the Gas Diffusion Layer market. In 2025, the sector reached a valuation of approximately 2,000.0 million USD, a substantial increase driven by accelerating automotive fuel cell deployments, growing stationary power installations, and the maturation of portable power applications. Forecasts indicate that this momentum will continue, with the market projected to reach 2,271.54 million USD in 2026 and eventually surpass the 4,000.0 million USD threshold by 2032.
Worldwide Bipolar Plate Fuel Cell Market
Our analysis identifies a compound annual growth rate of 13.18 percent across the 2026 to 2032 forecast period. This trajectory is not merely a continuation of historical trends but is underpinned by structural changes in manufacturing capacity, regional demand surges, and the diversification of end-use applications. The historical segment from 2020 to 2025 demonstrates a clear acceleration, with annual revenues climbing from 700.0 million USD to over 2,000.0 million USD. This compound growth reflects the sector's maturation, moving beyond experimental prototypes into scalable production environments where reliability, cost efficiency, and supply chain stability are paramount.
Strategic Implications of Growth Patterns
The forecasted growth rate carries significant implications for procurement strategies, capacity planning, and competitive positioning. Companies that recognize the inflection point in demand will be better positioned to secure long-term supply agreements, invest in advanced manufacturing capabilities, and capitalize on regional demand shifts. The market's trajectory also highlights the increasing importance of material innovation. Traditional gas diffusion layers have relied on carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. However, academic research and industrial development are increasingly exploring fluorine-free alternatives, including interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These innovations promise to address environmental concerns, reduce reliance on fluorinated compounds, and potentially lower production costs over the long term.
Competitive Landscape and Industry Concentration
The Gas Diffusion Layer market is characterized by a moderately concentrated competitive structure. Our analysis indicates that the top three firms command a combined market share of 60.0 percent, while the top five players collectively hold 70.0 percent of the market. This concentration underscores the dominance of established materials science and carbon fiber specialists who have leveraged decades of experience in advanced composites to secure strong positions in the hydrogen fuel cell supply chain. At the same time, the remaining market share is distributed among specialized manufacturers, regional suppliers, and innovative startups that are differentiating themselves through material substitutions, performance enhancements, and targeted application segments.
Key Players and Strategic Positioning
The competitive field is led by a cohort of globally recognized companies, each bringing distinct technological capabilities and regional strengths to the table. SGL Carbon, headquartered in Germany, is a pioneer in carbon-based solutions and produces SIGRACET carbon paper and carbon cloth gas diffusion layers with microporous layer and PTFE treatments tailored for PEM hydrogen fuel cells. In a notable move toward sustainability, SGL Carbon announced a new pilot line in Germany that uses recycled carbon fibers for GDL production, aiming to reduce raw material waste by up to 40 percent. This initiative reflects a broader industry push to align manufacturing practices with circular economy principles and regulatory expectations.
Toray Industries, based in Japan, manufactures Torayca carbon paper GDL products for PEM fuel cells and water electrolyzers. The company showcased its Torayca GDL for PEM fuel cells and Torayca carbon paper for PEM water electrolyzers at the Hydrogen Technology World Expo 2025, reinforcing its commitment to serving both fuel cell and electrolysis ecosystems. Freudenberg Group, also based in Germany, provides a comprehensive range of Freudenberg fuel cell gas diffusion layers, encompassing both carbon cloth and paper types, and has built a reputation for reliability in demanding automotive and stationary applications.
AvCarb LLC, operating from the United States, offers the MGL series of carbon cloth gas diffusion layers specifically engineered for hydrogen fuel cell applications. Caplinq Corporation, another US-based supplier, provides LINQCELL carbon paper, graphitized carbon paper, and conductive plastic GDL products, catering to research, development, and commercial production needs. Technical Fibre Products Ltd, based in the United Kingdom, develops and produces carbon fiber cloth and felt gas diffusion layers, leveraging deep expertise in carbon fiber processing. Mitsubishi Chemical Corporation, headquartered in Japan, supplies GDL materials and components for hydrogen fuel cell systems, integrating material science capabilities with broader industrial chemical expertise.
Additional players further enrich the competitive landscape. Fuel Cells Etc, a US-based retailer and provider, supplies Sigracet, ELAT, and other carbon cloth and paper GDL products, serving both commercial and research markets. Mott Corporation, also based in the United States, manufactures porous GDL substrates and related fuel cell materials, focusing on engineered porosity and custom substrate solutions. GKD Gebr. Kufferath AG, headquartered in Germany, produces mesh-based gas diffusion layers for fuel cell applications, offering alternative structural approaches to gas distribution and water management.
Hydrogen Fuel Cell Gas Diffusion Layer Market
Supply Chain Dynamics and Regulatory Pressures
The market's growth is occurring against a backdrop of evolving geopolitical and regulatory dynamics. Trade constraints between the United States and China have the potential to disrupt supply chains for critical GDL components, particularly those relying on specialized precursors, manufacturing equipment, or intermediate materials sourced from Asia. These constraints necessitate a proactive approach to supply chain diversification, regional sourcing strategies, and inventory resilience. Companies that fail to anticipate these disruptions risk cost escalations, production delays, and loss of competitive advantage in key end markets.
Simultaneously, the European Union's push for green energy policies and possible trade barriers for GDL materials introduces additional complexity. Regulatory frameworks aimed at reducing carbon footprints, promoting circular economy practices, and ensuring sustainable material sourcing are reshaping procurement requirements and manufacturing standards. The environmental performance of gas diffusion layers, including the use of fluorinated agents and the recyclability of carbon fiber substrates, is increasingly scrutinized. This regulatory environment favors suppliers that can demonstrate compliance with emerging sustainability criteria, invest in cleaner production processes, and adapt to evolving trade policies.
Raw material considerations also play a pivotal role in market dynamics. Traditional GDLs are comprised of carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. While these materials have proven effective in managing water repellency and gas distribution, the industry is exploring alternatives that reduce or eliminate fluorine content. The development of fluorine-free bulk hydrophobic GDLs with interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber represents a significant technological frontier. These innovations could alter material cost structures, simplify recycling processes, and align GDL production with stricter environmental regulations.
Market Segmentation: Type, Application, and Regional Drivers
Understanding the market's structural composition is essential for identifying growth opportunities and optimizing product portfolios. The segmentation analysis reveals distinct patterns across material types, application sectors, and geographic regions, each with unique drivers and competitive dynamics.
Material Type Dynamics
The market is segmented by material type into carbon paper, carbon cloth, and other specialized variants. Carbon paper remains the dominant material category, reflecting its widespread adoption in high-volume automotive and stationary power applications where cost efficiency, mechanical stability, and consistent performance are critical. Carbon cloth offers distinct advantages in terms of flexibility, compressibility, and gas permeability, making it particularly suitable for certain portable power applications and specialized fuel cell designs. The other types segment encompasses emerging material configurations, including hybrid structures, metal-based substrates, and advanced composites that address specific performance or cost requirements. Each type presents different manufacturing challenges, supply chain considerations, and end-use suitability, requiring companies to maintain a diversified material portfolio to capture demand across multiple segments.
Application Segment Opportunities
The application landscape is divided among automotive, stationary power generation, and portable power. Automotive applications represent the largest demand driver, fueled by the continued rollout of fuel cell electric vehicles, commercial fleet deployments, and infrastructure expansion. Stationary power generation constitutes a significant and growing segment, driven by backup power systems, microgrid solutions, and industrial decarbonization initiatives where fuel cells provide reliable, low-emission electricity. Portable power applications, while smaller in absolute terms, serve niche markets such as military equipment, remote telecommunications, and specialized consumer devices, where lightweight, high-energy-density power sources are essential. Each application segment demands different performance characteristics, durability standards, and cost structures, influencing the design, material selection, and manufacturing approach for gas diffusion layers.
Regional Demand Patterns
Geographic diversification is a defining feature of the market. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each region exhibiting distinct drivers, regulatory environments, and competitive intensities. Asia Pacific stands out as a major growth engine, supported by aggressive hydrogen strategies, large-scale manufacturing investments, and rapid adoption of fuel cell technologies in both transportation and stationary power. North America and Europe continue to play pivotal roles, driven by policy incentives, stringent emissions targets, and a strong presence of technology leaders and research institutions. Latin America and the Middle East and Africa represent emerging opportunities, where hydrogen initiatives are gaining momentum and infrastructure development is gradually expanding the addressable market for fuel cell components. Companies operating in this landscape must tailor their market entry strategies, supply chain configurations, and product positioning to the specific regulatory, economic, and demand conditions of each region.
Report Scope and Operational Relevance
The PW Consulting Hydrogen Fuel Cell Gas Diffusion Layer Market report is designed to deliver actionable intelligence that supports strategic decision-making across multiple functional areas. The study provides a detailed examination of market size, growth trajectories, segmentation patterns, competitive positioning, and industry dynamics, equipping executives with the data and context needed to formulate effective strategies.
Core Analytical Components
The report encompasses a thorough assessment of historical performance and forecast projections, enabling readers to contextualize current market conditions and anticipate future developments. It includes a granular segmentation analysis that dissects demand by material type, application, and region, highlighting the relative weight and growth characteristics of each segment. Competitive analysis profiles key market participants, examining their product portfolios, technological capabilities, strategic initiatives, and market share positions. The study also evaluates recent developments and industry events that shape the competitive environment, including capacity expansions, trade show demonstrations, material innovation announcements, and regulatory changes.
Operational and Strategic Applications
For procurement and supply chain teams, the report offers insights into material availability, supplier landscape, and cost drivers, supporting sourcing decisions and risk mitigation strategies. For product development and engineering leaders, the analysis of material types, technological trends, and application requirements provides a foundation for innovation roadmaps and performance optimization. For business development and commercial teams, the segmentation and regional analysis helps identify high-growth opportunities, prioritize market entry initiatives, and tailor value propositions to specific customer segments. For executive leadership and investors, the competitive concentration analysis, growth projections, and regulatory context inform long-term positioning, portfolio allocation, and risk assessment.
The report also addresses the practical challenges of scaling production, managing raw material dependencies, and navigating trade and regulatory complexities. It highlights the importance of aligning manufacturing capabilities with demand patterns, investing in material innovation to stay ahead of regulatory shifts, and building supply chain resilience in an environment of geopolitical uncertainty. By integrating market data, competitive intelligence, and industry context, the study provides a holistic view of the factors that will influence success in the hydrogen fuel cell gas diffusion layer market through 2032.
Strategic Imperatives for 2026 and Beyond
As the market advances toward the mid-2020s, several strategic imperatives emerge for companies operating in or adjacent to the hydrogen fuel cell gas diffusion layer ecosystem. First, securing reliable access to high-quality materials and manufacturing capacity is essential. The concentration of market share among leading suppliers underscores the need for strong supplier relationships, long-term agreements, and, where feasible, vertical integration or strategic partnerships to ensure supply continuity. Second, monitoring and adapting to regulatory changes, particularly around fluorinated materials, recycling requirements, and trade policies, will be critical to maintaining compliance and competitive relevance. Third, investing in material innovation and process optimization offers a pathway to differentiation, cost reduction, and alignment with sustainability goals. Fourth, regional strategy must be nuanced, recognizing that demand drivers, regulatory environments, and competitive intensities vary significantly across geographies.
The hydrogen fuel cell gas diffusion layer market is at an inflection point. Growth is accelerating, competition is intensifying, and the technological and regulatory landscape is evolving rapidly. Companies that approach this environment with rigorous analysis, strategic foresight, and operational agility will be best positioned to capture value and drive long-term success.
This overview provides a structured preview of the insights contained within the full PW Consulting market research report. For detailed segmentation data, complete competitive profiles, quantified regional and application breakdowns, and comprehensive forecast models, we invite stakeholders to access the full study. The complete intelligence package is designed to support precise strategic planning, informed investment decisions, and confident navigation of the hydrogen fuel cell gas diffusion layer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com