

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogen Fuel Cell GDL Market Hits $2B in 2025, Surges to $4B by 2032 at 13.18% CAGR

Navigating the Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Intelligence for 2026 and Beyond
The transition toward net-zero economies has placed hydrogen fuel cells at the center of global decarbonization strategies. Within the intricate architecture of a proton exchange membrane fuel cell, the Gas Diffusion Layer serves as a critical interface between the flow field and the catalyst layer. This thin, porous component is responsible for distributing reactant gases evenly, managing water removal, and facilitating electron transport. As the industry scales from niche applications to mass deployment, the Gas Diffusion Layer market has emerged as a high-stakes battleground for materials science, supply chain resilience, and strategic positioning.
PW Consulting's latest market research publication provides a comprehensive, data-driven analysis of this evolving landscape. Designed for executives, investors, and strategic planners, this report dissects the market dynamics, competitive structures, and technological shifts that will define the sector through 2032. The following analysis outlines the core insights and strategic value embedded within the full study, offering a clear preview of the intelligence required to navigate the complexities of 2026 and the forecast period ahead.
Market Trajectory and Growth Dynamics
The hydrogen economy is transitioning from policy-driven pilots to commercially viable deployments. This shift is reflected in the robust expansion of the Gas Diffusion Layer market. In 2025, the sector reached a valuation of approximately 2,000.0 million USD, a substantial increase driven by accelerating automotive fuel cell deployments, growing stationary power installations, and the maturation of portable power applications. Forecasts indicate that this momentum will continue, with the market projected to reach 2,271.54 million USD in 2026 and eventually surpass the 4,000.0 million USD threshold by 2032.
Worldwide Bipolar Plate Fuel Cell Market
Our analysis identifies a compound annual growth rate of 13.18 percent across the 2026 to 2032 forecast period. This trajectory is not merely a continuation of historical trends but is underpinned by structural changes in manufacturing capacity, regional demand surges, and the diversification of end-use applications. The historical segment from 2020 to 2025 demonstrates a clear acceleration, with annual revenues climbing from 700.0 million USD to over 2,000.0 million USD. This compound growth reflects the sector's maturation, moving beyond experimental prototypes into scalable production environments where reliability, cost efficiency, and supply chain stability are paramount.
Strategic Implications of Growth Patterns
The forecasted growth rate carries significant implications for procurement strategies, capacity planning, and competitive positioning. Companies that recognize the inflection point in demand will be better positioned to secure long-term supply agreements, invest in advanced manufacturing capabilities, and capitalize on regional demand shifts. The market's trajectory also highlights the increasing importance of material innovation. Traditional gas diffusion layers have relied on carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. However, academic research and industrial development are increasingly exploring fluorine-free alternatives, including interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These innovations promise to address environmental concerns, reduce reliance on fluorinated compounds, and potentially lower production costs over the long term.
Competitive Landscape and Industry Concentration
The Gas Diffusion Layer market is characterized by a moderately concentrated competitive structure. Our analysis indicates that the top three firms command a combined market share of 60.0 percent, while the top five players collectively hold 70.0 percent of the market. This concentration underscores the dominance of established materials science and carbon fiber specialists who have leveraged decades of experience in advanced composites to secure strong positions in the hydrogen fuel cell supply chain. At the same time, the remaining market share is distributed among specialized manufacturers, regional suppliers, and innovative startups that are differentiating themselves through material substitutions, performance enhancements, and targeted application segments.
Key Players and Strategic Positioning
The competitive field is led by a cohort of globally recognized companies, each bringing distinct technological capabilities and regional strengths to the table. SGL Carbon, headquartered in Germany, is a pioneer in carbon-based solutions and produces SIGRACET carbon paper and carbon cloth gas diffusion layers with microporous layer and PTFE treatments tailored for PEM hydrogen fuel cells. In a notable move toward sustainability, SGL Carbon announced a new pilot line in Germany that uses recycled carbon fibers for GDL production, aiming to reduce raw material waste by up to 40 percent. This initiative reflects a broader industry push to align manufacturing practices with circular economy principles and regulatory expectations.
Toray Industries, based in Japan, manufactures Torayca carbon paper GDL products for PEM fuel cells and water electrolyzers. The company showcased its Torayca GDL for PEM fuel cells and Torayca carbon paper for PEM water electrolyzers at the Hydrogen Technology World Expo 2025, reinforcing its commitment to serving both fuel cell and electrolysis ecosystems. Freudenberg Group, also based in Germany, provides a comprehensive range of Freudenberg fuel cell gas diffusion layers, encompassing both carbon cloth and paper types, and has built a reputation for reliability in demanding automotive and stationary applications.
AvCarb LLC, operating from the United States, offers the MGL series of carbon cloth gas diffusion layers specifically engineered for hydrogen fuel cell applications. Caplinq Corporation, another US-based supplier, provides LINQCELL carbon paper, graphitized carbon paper, and conductive plastic GDL products, catering to research, development, and commercial production needs. Technical Fibre Products Ltd, based in the United Kingdom, develops and produces carbon fiber cloth and felt gas diffusion layers, leveraging deep expertise in carbon fiber processing. Mitsubishi Chemical Corporation, headquartered in Japan, supplies GDL materials and components for hydrogen fuel cell systems, integrating material science capabilities with broader industrial chemical expertise.
Additional players further enrich the competitive landscape. Fuel Cells Etc, a US-based retailer and provider, supplies Sigracet, ELAT, and other carbon cloth and paper GDL products, serving both commercial and research markets. Mott Corporation, also based in the United States, manufactures porous GDL substrates and related fuel cell materials, focusing on engineered porosity and custom substrate solutions. GKD Gebr. Kufferath AG, headquartered in Germany, produces mesh-based gas diffusion layers for fuel cell applications, offering alternative structural approaches to gas distribution and water management.
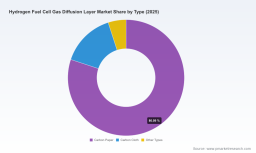
Hydrogen Fuel Cell Gas Diffusion Layer Market
Supply Chain Dynamics and Regulatory Pressures
The market's growth is occurring against a backdrop of evolving geopolitical and regulatory dynamics. Trade constraints between the United States and China have the potential to disrupt supply chains for critical GDL components, particularly those relying on specialized precursors, manufacturing equipment, or intermediate materials sourced from Asia. These constraints necessitate a proactive approach to supply chain diversification, regional sourcing strategies, and inventory resilience. Companies that fail to anticipate these disruptions risk cost escalations, production delays, and loss of competitive advantage in key end markets.
Simultaneously, the European Union's push for green energy policies and possible trade barriers for GDL materials introduces additional complexity. Regulatory frameworks aimed at reducing carbon footprints, promoting circular economy practices, and ensuring sustainable material sourcing are reshaping procurement requirements and manufacturing standards. The environmental performance of gas diffusion layers, including the use of fluorinated agents and the recyclability of carbon fiber substrates, is increasingly scrutinized. This regulatory environment favors suppliers that can demonstrate compliance with emerging sustainability criteria, invest in cleaner production processes, and adapt to evolving trade policies.
Raw material considerations also play a pivotal role in market dynamics. Traditional GDLs are comprised of carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. While these materials have proven effective in managing water repellency and gas distribution, the industry is exploring alternatives that reduce or eliminate fluorine content. The development of fluorine-free bulk hydrophobic GDLs with interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber represents a significant technological frontier. These innovations could alter material cost structures, simplify recycling processes, and align GDL production with stricter environmental regulations.
Market Segmentation: Type, Application, and Regional Drivers
Understanding the market's structural composition is essential for identifying growth opportunities and optimizing product portfolios. The segmentation analysis reveals distinct patterns across material types, application sectors, and geographic regions, each with unique drivers and competitive dynamics.
Material Type Dynamics
The market is segmented by material type into carbon paper, carbon cloth, and other specialized variants. Carbon paper remains the dominant material category, reflecting its widespread adoption in high-volume automotive and stationary power applications where cost efficiency, mechanical stability, and consistent performance are critical. Carbon cloth offers distinct advantages in terms of flexibility, compressibility, and gas permeability, making it particularly suitable for certain portable power applications and specialized fuel cell designs. The other types segment encompasses emerging material configurations, including hybrid structures, metal-based substrates, and advanced composites that address specific performance or cost requirements. Each type presents different manufacturing challenges, supply chain considerations, and end-use suitability, requiring companies to maintain a diversified material portfolio to capture demand across multiple segments.
Application Segment Opportunities
The application landscape is divided among automotive, stationary power generation, and portable power. Automotive applications represent the largest demand driver, fueled by the continued rollout of fuel cell electric vehicles, commercial fleet deployments, and infrastructure expansion. Stationary power generation constitutes a significant and growing segment, driven by backup power systems, microgrid solutions, and industrial decarbonization initiatives where fuel cells provide reliable, low-emission electricity. Portable power applications, while smaller in absolute terms, serve niche markets such as military equipment, remote telecommunications, and specialized consumer devices, where lightweight, high-energy-density power sources are essential. Each application segment demands different performance characteristics, durability standards, and cost structures, influencing the design, material selection, and manufacturing approach for gas diffusion layers.
Regional Demand Patterns
Geographic diversification is a defining feature of the market. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each region exhibiting distinct drivers, regulatory environments, and competitive intensities. Asia Pacific stands out as a major growth engine, supported by aggressive hydrogen strategies, large-scale manufacturing investments, and rapid adoption of fuel cell technologies in both transportation and stationary power. North America and Europe continue to play pivotal roles, driven by policy incentives, stringent emissions targets, and a strong presence of technology leaders and research institutions. Latin America and the Middle East and Africa represent emerging opportunities, where hydrogen initiatives are gaining momentum and infrastructure development is gradually expanding the addressable market for fuel cell components. Companies operating in this landscape must tailor their market entry strategies, supply chain configurations, and product positioning to the specific regulatory, economic, and demand conditions of each region.
Report Scope and Operational Relevance
The PW Consulting Hydrogen Fuel Cell Gas Diffusion Layer Market report is designed to deliver actionable intelligence that supports strategic decision-making across multiple functional areas. The study provides a detailed examination of market size, growth trajectories, segmentation patterns, competitive positioning, and industry dynamics, equipping executives with the data and context needed to formulate effective strategies.
Core Analytical Components
The report encompasses a thorough assessment of historical performance and forecast projections, enabling readers to contextualize current market conditions and anticipate future developments. It includes a granular segmentation analysis that dissects demand by material type, application, and region, highlighting the relative weight and growth characteristics of each segment. Competitive analysis profiles key market participants, examining their product portfolios, technological capabilities, strategic initiatives, and market share positions. The study also evaluates recent developments and industry events that shape the competitive environment, including capacity expansions, trade show demonstrations, material innovation announcements, and regulatory changes.
Operational and Strategic Applications
For procurement and supply chain teams, the report offers insights into material availability, supplier landscape, and cost drivers, supporting sourcing decisions and risk mitigation strategies. For product development and engineering leaders, the analysis of material types, technological trends, and application requirements provides a foundation for innovation roadmaps and performance optimization. For business development and commercial teams, the segmentation and regional analysis helps identify high-growth opportunities, prioritize market entry initiatives, and tailor value propositions to specific customer segments. For executive leadership and investors, the competitive concentration analysis, growth projections, and regulatory context inform long-term positioning, portfolio allocation, and risk assessment.
The report also addresses the practical challenges of scaling production, managing raw material dependencies, and navigating trade and regulatory complexities. It highlights the importance of aligning manufacturing capabilities with demand patterns, investing in material innovation to stay ahead of regulatory shifts, and building supply chain resilience in an environment of geopolitical uncertainty. By integrating market data, competitive intelligence, and industry context, the study provides a holistic view of the factors that will influence success in the hydrogen fuel cell gas diffusion layer market through 2032.
Strategic Imperatives for 2026 and Beyond
As the market advances toward the mid-2020s, several strategic imperatives emerge for companies operating in or adjacent to the hydrogen fuel cell gas diffusion layer ecosystem. First, securing reliable access to high-quality materials and manufacturing capacity is essential. The concentration of market share among leading suppliers underscores the need for strong supplier relationships, long-term agreements, and, where feasible, vertical integration or strategic partnerships to ensure supply continuity. Second, monitoring and adapting to regulatory changes, particularly around fluorinated materials, recycling requirements, and trade policies, will be critical to maintaining compliance and competitive relevance. Third, investing in material innovation and process optimization offers a pathway to differentiation, cost reduction, and alignment with sustainability goals. Fourth, regional strategy must be nuanced, recognizing that demand drivers, regulatory environments, and competitive intensities vary significantly across geographies.
The hydrogen fuel cell gas diffusion layer market is at an inflection point. Growth is accelerating, competition is intensifying, and the technological and regulatory landscape is evolving rapidly. Companies that approach this environment with rigorous analysis, strategic foresight, and operational agility will be best positioned to capture value and drive long-term success.
This overview provides a structured preview of the insights contained within the full PW Consulting market research report. For detailed segmentation data, complete competitive profiles, quantified regional and application breakdowns, and comprehensive forecast models, we invite stakeholders to access the full study. The complete intelligence package is designed to support precise strategic planning, informed investment decisions, and confident navigation of the hydrogen fuel cell gas diffusion layer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com