

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium-Sulfur Battery Market to Hit $262.8M by 2032, 25.7% CAGR

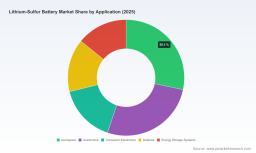
The Lithium-Sulfur Imperative: Strategic Intelligence for the 2026 Market Inflection
The energy storage landscape is undergoing a structural transformation. After years of incremental improvements in lithium-ion chemistry, the industry is pivoting toward next-generation architectures that promise to decouple performance from cost. Among these, lithium-sulfur technology has moved from laboratory promise to commercial urgency. Our latest market research, spanning historical analysis from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032, captures this transition at precisely the moment when capital allocation, supply chain strategy, and product roadmaps are being locked in for the next decade.
For executives navigating 2026 investment decisions, this report is not a retrospective exercise. It is a decision-support instrument designed to separate signal from noise in a rapidly consolidating landscape where incumbents, startups, and strategic partners are simultaneously racing to scale production, secure raw material advantages, and comply with evolving regulatory frameworks. The insights within are structured to inform go-to-market timing, partnership evaluation, R&D prioritization, and risk hedging across aerospace, automotive, defense, consumer electronics, and stationary storage verticals.
Market Trajectory and the Shape of the Opportunity
The macroeconomic arc of the lithium-sulfur market tells a story of accelerating adoption. Historical revenue tracking from 2020 through 2025 reveals a compounding growth curve that has consistently outpaced earlier projections. The baseline year of 2025 closes at a meaningful inflection point, setting the stage for a forecast period in which the market is projected to expand at a compound annual growth rate of 25.7 percent through 2032. By the end of the forecast window, total market revenue is expected to reach a scale that fundamentally reshapes how investors, OEMs, and policy makers evaluate advanced battery technologies.
This trajectory is not linear extrapolation. It reflects the convergence of multiple structural drivers: the relentless pursuit of higher gravimetric energy density, the economic logic of sulfur-based cathode chemistry, and a regulatory environment that increasingly rewards domestically sourced and low-carbon battery architectures. For strategic planners, the implication is clear. The window for first-mover advantage in specific application segments is narrowing, and the cost of delayed entry is rising as manufacturing capacity begins to materialize and downstream customers start locking in multi-year supply agreements.
What This Report Delivers: An Operational Roadmap
Our research is built around actionable intelligence rather than high-level commentary. Readers will find a comprehensive breakdown of market sizing across the full forecast horizon, with revenue projections calibrated to technology readiness levels, application adoption curves, and regional manufacturing dynamics. The segmentation architecture examines the market through multiple lenses, including type differentiation that distinguishes high-energy-density configurations from lower-density variants, and a detailed application mapping that spans aerospace, automotive, consumer electronics, defense, and energy storage systems.
Beyond sizing, the report delivers a granular competitive landscape analysis. We profile the companies actively shaping the lithium-sulfur ecosystem, evaluating their technological approaches, manufacturing strategies, partnership footprints, and recent commercial moves. The analysis captures the diversity of engineering pathways currently under evaluation, from proprietary three-dimensional graphene architectures and sulfurized-carbon cathodes to nano-encapsulated sulfur formulations, polymer-host anode designs, and thin glass-protected lithium-metal anodes. This comparative framework allows decision makers to benchmark competitor positioning, anticipate consolidation patterns, and identify white spaces where differentiated offerings can command premium positioning.
The report also integrates a forward-looking view of industry dynamics. Regulatory developments, incentive structures, raw material economics, and supply chain considerations are woven into the analysis so that readers can stress-test their strategies against realistic assumptions. This includes an examination of how carbon footprint declaration requirements for industrial rechargeable batteries are reshaping procurement criteria in Europe, how investment tax credit eligibility for hybrid battery energy storage systems continues to support project economics in the United States through 2035, and how long-duration storage cost targets are creating new demand signals for advanced chemistries.
Competitive Architecture: The Battlefield of Lithium-Sulfur Innovation
The competitive field is defined by a mix of well-capitalized startups, specialized technology developers, research institutions, and strategic corporate partners. Several themes emerge from our analysis. First, the race to achieve commercially viable energy density at scale is attracting significant capital and corporate attention. Companies are pursuing divergent technical routes, each with distinct trade-offs in cycle life, manufacturability, safety, and cost structure. This fragmentation is both a risk and an opportunity: it signals that the winning architecture has not yet been universally settled, but it also means that monitoring technical differentiation is essential for partnership and investment decisions.
Lithium-Metal Secondary Battery Market
Recent corporate activity underscores the urgency. In 2025, one of the leading participants began U.S. production of battery-grade lithium-metal foil, a move that completes a localized supply chain for lithium-sulfur batteries and reduces exposure to cross-border component risks. That same company followed with a next-generation drone propulsion system built around American-made lithium-sulfur batteries, targeting national security and defense use cases, and subsequently secured more than 200 million dollars in additional equity investment to accelerate manufacturing expansion and acquisitions. In early 2026, the company entered a binding agreement to acquire a European battery recycling plant, signaling a strategic push to expand lithium-sulfur manufacturing capacity while integrating circular economy considerations into the value chain.
Automotive interest is also crystallizing. A major global automaker announced a joint development agreement with a sulfurized-carbon cathode specialist to co-develop lithium-sulfur EV battery cells with higher gravimetric energy density, an early indicator that large-volume OEMs are moving from observation to active co-engineering. Meanwhile, multiple developers are publicly targeting energy density thresholds that would meaningfully extend electric vehicle range, enable new aviation concepts including eVTOL platforms, and improve the economics of stationary storage deployments. These targets span a wide range, from cell-level configurations approaching 380 Wh/kg to advanced platforms aiming for substantially higher densities, reflecting the breadth of technical ambition in the sector.
Research institutions and government-funded programs remain critical enablers. Several organizations are advancing cycle life and energy density improvements with Department of Energy backing, while pilot production facilities are bridging the gap between laboratory breakthroughs and pilot-scale manufacturing. This ecosystem dynamic means that competitive intelligence must extend beyond commercial manufacturers to include the research and pilot infrastructure that will shape future supply options and technology licensing opportunities.
Market Dynamics: Regulation, Economics, and Supply Chain Realignment
The commercial viability of lithium-sulfur batteries is being shaped as much by policy and input economics as by technical progress. In Europe, regulatory requirements now mandate carbon footprint declarations for industrial rechargeable batteries exceeding 2 kWh capacity, a development that rewards manufacturers with transparent, low-carbon supply chains and creates a compliance differentiator for domestically sourced production. In the United States, the continuation of investment tax credit eligibility for hybrid battery energy storage systems through 2035 sustains project-level economics that favor advanced storage deployments, indirectly supporting demand for higher-performance battery chemistries in stationary applications.
Raw material economics provide another layer of strategic advantage. Sulfur cathode active material costs in lithium-sulfur batteries are reported at approximately 7 cents per kWh, roughly one-third of the equivalent input cost in conventional lithium-ion architectures. This cost asymmetry is a fundamental argument for the long-term competitiveness of the chemistry, particularly in cost-sensitive applications where energy density and material affordability must be balanced. Coupled with domestic sourcing pathways for sulfur and lithium-metal anodes that support tariff-free manufacturing, the input cost structure creates a credible route to price competitiveness as scale increases.
On the demand side, public-sector cost targets are sharpening focus. The Department of Energy's long-duration storage shot aims to reduce the levelized cost of storage to 5 cents per kWh by 2030 through advanced battery technologies, including lithium-sulfur platforms. While this target spans multiple technology pathways, it signals a clear policy direction: advanced chemistries that can deliver low levelized cost at scale will be prioritized in procurement, incentive design, and research funding. For companies and investors, aligning product roadmaps with these cost trajectories is becoming a strategic necessity rather than an optional optimization.
Decision Framework for 2026 and Beyond
As the market moves from early commercialization into a phase of capacity expansion and application-specific scaling, strategic decisions must be grounded in a clear understanding of where value will accrue. Several considerations should guide executive planning. First, the concentration of market share among leading participants remains moderate, indicating that the sector is still in a competitive formation stage rather than a mature oligopoly. This creates room for new entrants, targeted acquisitions, and differentiated positioning, but it also requires disciplined analysis of which technical and commercial pathways are most likely to achieve scale.
Second, application segmentation will not converge uniformly. Aerospace and defense use cases prioritize energy density and supply chain security, automotive applications demand cost-competitive scaling and integration with existing vehicle architectures, and stationary storage deployments weigh levelized cost, cycle life, and regulatory compliance. Our segmentation analysis helps decision makers map these differing requirements to realistic adoption timelines and revenue opportunities, avoiding the trap of treating lithium-sulfur as a single-market proposition.
Third, supply chain strategy is becoming a competitive moat. Companies that can localize critical inputs, integrate recycling capacity, and align with regulatory requirements around carbon transparency are building advantages that extend beyond cell performance. The recent moves toward domestic lithium-metal foil production, European recycling capacity acquisition, and tariff-free input sourcing illustrate how supply chain design is now inseparable from technology strategy.
Why This Research Matters Now
The 2026 to 2032 forecast window is not a distant planning exercise. It is the period during which manufacturing capacity, customer qualification cycles, regulatory compliance costs, and partnership structures will be established. Decisions made in 2026 regarding technology bets, supplier relationships, geographic focus, and application prioritization will determine competitive positioning for the remainder of the decade. Our report is designed to provide the depth, structure, and forward-looking context needed to make those decisions with confidence.
The full study goes beyond summary indicators to deliver the detailed segmentation data, company profiles, regulatory impact assessments, and scenario-based revenue projections that strategic teams require. It is built for executives who need to translate market momentum into concrete action: where to invest, whom to partner with, which applications to prioritize, and how to position against a rapidly evolving competitive set. The macro trajectory is compelling, the technical pathways are diversifying, and the regulatory and cost environment is increasingly favorable. The critical question for 2026 is no longer whether lithium-sulfur batteries will matter, but how decisively an organization will act to capture its share of the opportunity.
Lithium-Sulfur Battery Market
For detailed analysis of this topic, please visit the official page: Lithium-Sulfur Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com