

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wind Turbine Blade Market Hits $29.34B in 2025, Projected 6.53% CAGR to 2032

Navigating the Wind Turbine Blade Market: Strategic Imperatives for 2026 and Beyond
The global energy transition is no longer a speculative narrative; it is a capital-intensive reality reshaping infrastructure portfolios worldwide. At the heart of this transformation lies the wind turbine blade, a critical component that dictates efficiency, longevity, and ultimately the levelized cost of energy. As we move through 2026, industry stakeholders face a complex matrix of technological innovation, regulatory pressure, and shifting geographic demand. This article serves as an executive overview of our latest comprehensive market research, designed to equip strategic decision-makers with the intelligence required to navigate this evolving landscape.
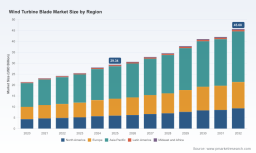
Our analysis indicates that the market has sustained a robust growth trajectory over the past half-decade. Valued at approximately 21.38 billion USD in 2020, the sector expanded steadily to reach 29.34 billion USD by 2025. This historical performance underscores the resilience of wind energy investments despite macroeconomic fluctuations. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market expected to surpass 45 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate that reflects sustained demand for both onshore and offshore capacity, driven by national renewable targets and corporate procurement strategies.
However, top-line figures only tell part of the story. The strategic value for enterprise leaders in 2026 lies in understanding the underlying dynamics propelling this growth. Our report dissects the market into critical dimensions, offering a granular view of where value is being created and where risks are consolidating. For instance, the shift towards larger rotor diameters and higher capacity turbines is altering material requirements and supply chain logistics. Similarly, the geographic redistribution of manufacturing hubs is responding to trade policies and localization mandates. Decision-makers must recognize that the market is not monolithic; it is a collection of distinct segments, each with its own profit pools and competitive intensities.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated turbine manufacturers and specialized blade suppliers. Our research identifies key players who are defining the standards for performance and sustainability. Companies such as LM Wind Power and Siemens Gamesa Renewable Energy remain pivotal, leveraging vertical integration and technological proprietary advantages to maintain market share. Vestas Wind Systems A/S continues to strengthen its position through strategic acquisitions, such as the recent expansion of its European manufacturing footprint, signaling a commitment to supply chain security and regional capacity.
Independent manufacturers like TPI Composites Inc. play a crucial role in the ecosystem, supporting multiple original equipment manufacturers across global facilities. Their ability to scale production, evidenced by significant production milestones reached in early 2025, highlights the importance of flexible manufacturing capabilities. Meanwhile, regional players in Asia and Europe, including Nordex SE, Enercon GmbH, and specialized Chinese manufacturers, are increasingly influential in shaping local market dynamics. The report provides detailed profiles of these entities, analyzing their strategic moves, capacity expansions, and partnership networks.
Market concentration remains a key metric for assessing competitive risk. The data suggests a moderately concentrated landscape where a handful of firms control a significant portion of revenue. Understanding the balance between integrated OEMs and independent suppliers is essential for procurement strategies and partnership evaluations. Our analysis explores how these relationships are evolving, particularly in the context of technology licensing and manufacturing alliances.
Technology and Sustainability: The New Battleground
Sustainability is transitioning from a corporate social responsibility initiative to a core operational requirement. The European wind industry has implemented a self-imposed landfill ban on decommissioned wind turbine blades effective January 2026. This regulatory milestone mandates that 100% of blades must be reused, recovered, or recycled. This shift places immense pressure on material science and end-of-life management strategies. Vestas has been proactive in this arena, aiming for full blade circularity by 2030 through initiatives like the CETEC project, which focuses on chemical disassembly processes for epoxy-infused blades.
Technological innovation is also accelerating in manufacturing processes. Advances such as additive manufacturing for blade molds, demonstrated through collaborations between industry leaders and national laboratories, are reducing production times and enabling more complex geometries. These developments offer potential efficiencies in cost and lead time, which are critical for meeting the aggressive installation targets set by governments globally. Siemens Gamesa's introduction of new offshore platforms exemplifies the push towards larger, more efficient turbines that can capitalize on offshore wind resources.
The report delves deep into these technological trajectories, evaluating their commercial viability and impact on cost structures. We assess the readiness levels of various recycling technologies and the potential for material redesign. For investors and product planners, understanding the timeline for these technologies to reach commercial scale is vital for long-term asset planning.
Market Dynamics and Regulatory Environment
The regulatory landscape is becoming increasingly complex, influencing both market entry and operational compliance. Beyond the European landfill ban, there are growing calls for Europe-wide regulations affecting large composite nacelle components. These regulations aim to standardize disposal practices and encourage circular economy principles across the industry. Companies operating in or exporting to these regions must align their product lifecycles with these emerging standards to avoid compliance risks and reputational damage.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Supply chain resilience is another critical dynamic. Geopolitical tensions and trade policies are prompting a reassessment of manufacturing locations. The data shows significant variation in regional market sizes, with Asia Pacific representing a substantial portion of global revenue, followed by Europe and North America. Each region presents unique challenges regarding logistics, labor costs, and local content requirements. Our study provides a comparative analysis of these regions, helping stakeholders optimize their geographic footprint without exposing sensitive strategic details prematurely.
Furthermore, the interaction between policy incentives and market demand creates volatility that requires agile strategic planning. Government subsidies, tax credits, and renewable portfolio standards vary significantly by jurisdiction. The report maps these policy frameworks against market growth projections to identify high-potential markets and potential bottlenecks.
What This Report Delivers for Your Organization
This market research is not merely a data compilation; it is a strategic toolkit designed for C-suite executives, investment managers, and product strategists. The full report offers detailed segmentation analysis across multiple dimensions, allowing you to isolate specific growth vectors relevant to your business unit. We provide historical data series that establish a reliable baseline for forecasting, alongside forward-looking estimates that account for scenario variations.
Readers will gain access to comprehensive profiles of key market participants, including their strategic focus, recent developments, and competitive positioning. This intelligence is crucial for benchmarking, merger and acquisition due diligence, and partnership identification. The analysis of recent industry events, such as major production milestones and facility acquisitions, provides context for understanding current market momentum.
Importantly, the report addresses the operational implications of sustainability mandates. We evaluate the cost implications of recycling technologies and the potential for new revenue streams from blade repurposing. This perspective is essential for companies looking to turn regulatory compliance into a competitive advantage. The insights provided are intended to support capital allocation decisions, R&D prioritization, and supply chain optimization.
Conclusion: The Path Forward
As the wind turbine blade market matures, the window for strategic advantage narrows. Success in 2026 and beyond will depend on the ability to anticipate technological shifts, navigate regulatory complexities, and optimize global operations. The data indicates a clear upward trend in market value, but realizing this potential requires nuanced understanding and precise execution.
Wind Turbine Blade Market
Our full market research report provides the depth and granularity needed to make informed decisions. It moves beyond general trends to offer specific, actionable intelligence tailored to the needs of industry leaders. We invite you to access the complete study to unlock the detailed segmentation data, comprehensive competitor analysis, and strategic recommendations that will define your approach in this critical sector. The insights contained within are designed to empower your organization to lead rather than follow in the renewable energy transition.
For detailed analysis of this topic, please visit the official page: Wind Turbine Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com