

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Precision Gear Market Reaches $1.14B in 2025, Booms at 6.5% CAGR to $1.77B by 2032

Precision at Scale: Navigating the High Precision Planetary Gear Reducers Market Through 2032
Executive Overview: A Market at the Intersection of Precision and Scale
The high precision planetary gear reducers market stands at a critical inflection point where mechanical engineering excellence meets accelerating industrial automation. As manufacturing ecosystems grow increasingly demanding in terms of torque density, positioning accuracy, and operational reliability, precision reducers have transitioned from peripheral components to mission-critical enablers of next-generation motion systems. This strategic intelligence briefing distills the core findings of our latest High Precision Planetary Gear Reducers Market research, offering decision-makers a structured foundation for capacity planning, technology roadmapping, and competitive positioning through 2032.
The market has demonstrated consistent expansion over the past half-decade, with assessed baseline valuations climbing from approximately 832 million USD in 2020 to a projected threshold near 1.14 billion USD in 2025. Forward-looking assessments indicate sustained momentum, with the market expected to reach roughly 1.2 billion USD in 2026 and continue its upward trajectory toward approximately 1.77 billion USD by 2032. The compound annual growth rate across the forecast horizon is estimated at 6.5 percent, reflecting a mature yet highly dynamic landscape where incremental efficiency gains, application diversification, and regional deployment shifts collectively shape demand curves. These figures represent aggregate market direction rather than isolated performance snapshots, underscoring the importance of segment-level intelligence for precise investment allocation.
Strategic Drivers Reshaping Demand Architecture
The underlying demand architecture for high precision planetary gear reducers is being reconfigured by three interlocking forces: automation intensity, precision tolerance escalation, and system integration complexity. Industrial motion control is no longer defined solely by load capacity; contemporary applications require reducers that maintain rigorous backlash thresholds, exhibit predictable thermal behavior under sustained duty cycles, and integrate seamlessly with servo architectures and digital control ecosystems. As servo-enabled automation platforms accelerate their penetration across discrete and process manufacturing, precision gear reduction has become a foundational requirement rather than an optional upgrade.
Parallel to this, the proliferation of advanced manufacturing infrastructure continues to elevate the baseline for mechanical accuracy. Updated transmission precision guidelines, including the 2024 revision of ISO 6336-1, now emphasize more stringent dynamic testing under thermal equilibrium conditions, establishing new benchmarks for validation, quality assurance, and supplier qualification. In this environment, organizations that rely on component-level uncertainty face heightened exposure to integration risk, warranty exposure, and production downtime. Understanding where precision requirements are tightening, and which engineering pathways are proving most scalable, is essential for supply chain resilience and product roadmap alignment.
Robot Joint Precision Reducers Market
Regional Demand Emergence and Competitive Reconfiguration
Demand dispersion across geographic markets is not uniform, nor is it static. Maturity, industrial mix, and capital investment cycles produce distinct regional demand signatures that influence volume absorption, pricing tolerance, and supplier localization strategies. Our analysis indicates that Asia Pacific currently anchors the largest share of market valuation, reflecting the scale of advanced manufacturing deployment, robotics integration, and industrial equipment production across the region. North America and Europe continue to represent structurally important markets, driven by high-value automation modernization, precision engineering ecosystems, and localized service expectations that reward reliability, responsiveness, and engineering support depth.
At the same time, Latin America and the Middle East and Africa are emerging as incremental growth theaters where industrial modernization programs, infrastructure investment, and re-shoring considerations are gradually expanding addressable demand. The strategic implication for global suppliers is not simply to chase aggregate volume, but to calibrate regional go-to-market models according to local application profiles, lead-time sensitivity, and after-sales service expectations. In practice, this requires differentiated assembly footprints, inventory positioning, and engineering localization strategies rather than a one-size-fits-all export approach.
Recent operational developments already illustrate how leading players are adapting to these regional realities. SEW-EURODRIVE, for example, has moved to establish local assembly capabilities for its P2.e planetary gear units in South Carolina, compressing lead times for cataloged ratios to as little as six weeks. Such localization actions are not merely logistical adjustments; they represent strategic commitments to service velocity, regional demand capture, and supply chain risk diversification. Meanwhile, Shanghai SGR Heavy Industry Machinery Co., Ltd. has used major industry exhibitions to showcase its N-series planetary gear reducers, emphasizing alloy steel formulations, multi-planetary load distribution design, and targeted applications in new energy yaw and pitch control systems. These releases reflect broader market trends in which precision transmission components are increasingly tied to new energy infrastructure, heavy automation, and specialized motion platforms.
Technology Roadmapping and Application Complexity
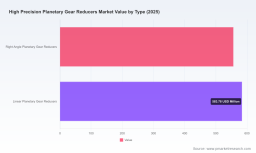
Within the broader market, product differentiation is increasingly defined by precision class, gearing architecture, and suitability for specific motion profiles. Right angle and linear planetary gear reducer families both command substantial market relevance, but their value propositions diverge across application scenarios. Right angle configurations remain critical where spatial constraints and shaft orientation requirements dictate compact torque transfer, while linear planetary designs are increasingly favored in precision actuation and positioning workflows that demand repeatable motion accuracy and predictable load distribution.
Industry stakeholders must also recognize that application diversity is not merely a segmentation detail; it is a strategic signal. Robotics remains one of the most prominent demand centers, where high precision planetary gear reducers enable torque control, joint accuracy, and compact packaging for increasingly capable manipulator systems. Industrial manufacturing continues to drive broad-based demand through CNC machine tools, packaging equipment, conveyors, and material handling automation. Semiconductor equipment represents a more specialized but strategically important application corridor, where ultra-clean environment compatibility, rigidity, and micron-level positioning control can determine end-equipment performance. Additional application domains further extend the addressable base, spanning medical device manufacturing, specialized automation platforms, and precision test and measurement systems.
The strategic insight for procurement, R&D, and product management teams lies in mapping these application requirements to the correct precision tier and mechanical configuration. Over-specifying where tolerance requirements are moderate erodes margin, while under-specifying in high-precision workflows creates integration fragility. Our research examines how leading engineering teams are aligning specification decisions with real duty cycles, thermal load scenarios, and lifecycle cost models rather than nominal catalog values alone.
High Precision Planetary Gear Reducers Market
Competitive Intensity and the Imperative of Differentiation
The competitive landscape for high precision planetary gear reducers is shaped by a concentrated but heterogeneous set of manufacturers, each pursuing distinct differentiation pathways. Europe remains home to several influential engineering-led suppliers, including Neugart GmbH, Wittenstein SE, SEW-EURODRIVE, and Stober Antriebstechnik GmbH, all of which emphasize low-backlash performance, high rigidity, and application-tailored design philosophies. NEUGART's Economy and Precision Line series, for instance, reflect a dual-track strategy that serves both cost-sensitive motion control deployments and applications requiring elevated precision. WITTENSTEIN's portfolio, spanning low-backlash servo gearboxes and hygienic-design variants, illustrates the market's need for specialized configurations in demanding operating environments. SEW-EURODRIVE continues to extend its industrial and servo offerings with high-torque planetary gear units, reinforcing its positioning in heavy-duty automation contexts.
In the Americas and Asia, competitive dynamics are increasingly defined by integration capability, servo application specialization, and scale-driven precision manufacturing. Apex Dynamics Inc. has built a reputation around helical gearing approaches that deliver low backlash and high torque in servo applications, while Harmonic Drive LLC has advanced zero-backlash performance concepts that align closely with robotics and precision actuation requirements. Sumitomo Heavy Industries and Nidec-Shimpo contribute complementary strengths in integrated drive technologies and compact motion control, respectively. In China, the competitive field includes Shanghai SGR Heavy Industry Machinery Co., Ltd., Hubei Planetary Gearboxes Co., Ltd., and Ningbo ZhongDa Leader Intelligent Transmission Co., Ltd., each targeting precision automation, industrial robotics, and intelligent transmission system development through localized engineering resources and expanding manufacturing capabilities. ZF Friedrichshafen AG, meanwhile, applies transmission heritage to precision planetary gear reducers across automotive and industrial contexts, highlighting the cross-pollination of engineering competencies across end markets.
Market structure analysis indicates that the top three players account for approximately 25 percent of assessed market value, while the top five collectively represent roughly 35 percent. This level of moderate concentration suggests a market in which scale incumbents hold meaningful advantage, but where specialized differentiation, application expertise, and regional responsiveness still create viable pathways for competitive success. The practical implication is that competitive strategy cannot rely on volume positioning alone. Suppliers must simultaneously invest in precision consistency, engineering support, lead-time reliability, and application-specific validation to protect share and expand margin.
Regulatory and Standards Evolution as Strategic Context
Standards evolution and measurement rigor are becoming more consequential for commercial competitiveness. ISO 6336-1:2024 updates have introduced more demanding dynamic testing expectations under thermal equilibrium, directly affecting how manufacturers validate gear quality and how system integrators assess supplier reliability. In parallel, broader industry signals reinforce the scale of precision motion demand. Global industrial robot installations reached 590,000 units in 2023, and more than 62 percent of those installations incorporated high precision planetary gear reducers for torque control and precise motion. Servo-based automation adoption grew by 13.4 percent in 2024 according to VDMA reporting, while machine tool export performance in Japan exceeded 10.7 billion USD in 2023, signaling sustained global investment in precision manufacturing infrastructure.
For corporate strategists, these dynamics carry two implications. First, compliance and validation capability are increasingly part of commercial differentiation; suppliers that can demonstrate test rigor, thermal stability, and documented quality systems are better positioned in qualification processes. Second, macro demand indicators provide directional confirmation that precision transmission remains embedded in broader automation expansion, reinforcing the case for long-cycle planning rather than short-term transactional positioning.
What the Research Delivers for Strategic Planning
This High Precision Planetary Gear Reducers Market report is designed to support actionable decision-making across strategy, product management, sales planning, and supply chain leadership. Beyond aggregate market sizing and forecast trajectories, the study provides structured analysis that allows organizations to benchmark their strategic assumptions, refine segment targeting, and anticipate demand shifts with greater confidence.
The report examines market segmentation from multiple operational angles, giving readers clarity on how demand is distributed across type and application categories, where growth is most concentrated, and which structural factors are likely to influence share movement over time. It also provides regional analysis that contextualizes demand intensity, local manufacturing dynamics, and localization implications for suppliers seeking to optimize service models and inventory positioning. Competitively, the research profiles the strategic posture, engineering focus, and recent moves of leading participants, helping readers interpret not just who is active in the market, but how rivals are positioning themselves for sustained relevance.
In addition, the analysis incorporates recent corporate developments and industry context that shape near-term market behavior. Trade show activity, local manufacturing expansions, standards revisions, and robotics and automation demand indicators are integrated into the narrative to help stakeholders connect strategic planning with on-the-ground developments. The objective is to provide a usable intelligence base for capacity planning, market entry evaluation, supplier selection, pricing strategy, and product roadmap alignment.
Recommended Strategic Actions for 2026 and Beyond
As organizations move from market awareness to action, several strategic priorities emerge. First, firms should strengthen precision validation and thermal-performance documentation to align with evolving standards expectations and integrator qualification requirements. Second, regional service models should be revisited in light of lead-time sensitivity and localized assembly trends, particularly where rapid delivery and application support are becoming competitive differentiators. Third, application-specific engineering engagement should be deepened, because value capture increasingly depends on matching reducer configuration to actual duty cycles, not catalog optimization alone.
Fourth, competitive positioning should account for moderate market concentration by balancing scale efficiency with differentiated expertise in key application areas such as robotics, industrial manufacturing, and precision equipment. Fifth, organizations should use forecast visibility through 2032 to inform investment pacing, ensuring that capacity, R&D, and go-to-market resources are aligned with the demand curve rather than reacting to it after the fact. In a market expanding toward a projected valuation approaching 1.77 billion USD by the end of the forecast period, disciplined strategic planning will separate durable participants from transient competitors.
Closing Perspective
The high precision planetary gear reducers market is not simply expanding; it is maturing into a more technically demanding, regionally nuanced, and competitively layered environment. Sustained growth at a 6.5 percent compound annual rate through 2032 signals continued relevance, but it also raises the bar for precision, reliability, localization, and engineering support. Organizations that treat precision reducers as strategic enablers rather than commodity components will be better positioned to capture value, reduce integration risk, and build durable supplier relationships across the automation ecosystem.
This intelligence briefing offers a high-level view of the terrain, but the full report provides the granular segmentation, regional valuations, application-level breakdowns, competitive benchmarking, and forecast scenarios necessary for precise strategic execution. For leadership teams seeking to translate market direction into operational decisions, the complete analysis can be accessed through the source report page, where the full dataset, detailed segmentation insights, and company-level assessments are available for review.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com