

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pad Printing Supplies Market to Hit $267.3M by 2032 with 5.65% CAGR

Strategic Intelligence for the Pad Printing Supplies Market: A 2032 Outlook
For procurement leaders, R&D directors, and competitive intelligence teams operating in industrial decoration and precision marking, the Pad Printing Supplies Market represents a microcosm of broader manufacturing shifts.
Over the past half-decade, the industry has navigated raw material volatility, tightening chemical regulations, and accelerating demand for eco-compliant consumables. The newly released Pad Printing Supplies Market research report distills these dynamics into a decision-grade framework, offering enterprise stakeholders a clear line of sight from historical performance through 2032. This overview previews the analytical architecture of the study and explains why its insights are indispensable for 2026 strategy formation.
The report is built on a rigorous methodological foundation that tracks revenue movement from 2020 through the base year of 2025. Historical data captures the market at roughly US$148.75 million in 2020, progressing through a series of incremental expansions to reach US$182.0 million by 2025. This trajectory reflects the sector's resilience against supply chain disruptions and its steady adoption in high-mix, low-volume production environments. Looking ahead, the forecast horizon extends to 2032, projecting the total market to surpass US$267 million over the period. The implied compound annual growth rate of 5.65 percent provides a reliable benchmark for investment pacing, capacity planning, and product roadmapping. Rather than presenting isolated figures, the study embeds these numbers within demand-side drivers, regulatory headwinds, and regional supply chain reconfigurations.
A defining feature of the 2026–2032 outlook is the tension between end-use momentum and material compliance. Pad printing has long been favored for its ability to reproduce fine detail on irregularly shaped substrates, but recent years have elevated the stakes for ink chemistry, pad durability, and cliché precision. Manufacturers serving consumer goods, hard goods, and identification applications increasingly require consumables that satisfy a mosaic of regulatory frameworks without sacrificing adhesion or line quality. The research report maps how these requirements reshape procurement criteria, how suppliers are re-engineering solvent and UV-based chemistries, and where end-users are willing to pay a premium for certified, low-VOC, and phthalate-free formulations. By examining the intersection of technical performance and compliance cost, the study provides a practical lens for evaluating total cost of ownership rather than sticker price alone.
Decoding the Market Structure: Concentration, Type, and Application Pressures
Market structure analysis is central to any credible strategic assessment, and this report approaches the Pad Printing Supplies Market with particular attention to competitive density and segmentation behavior. The sector exhibits moderate concentration at the top tier, with the leading three players accounting for approximately 32.4 percent of aggregate revenue and the top five reaching roughly 47.6 percent. Such figures signal a landscape where scale, distribution footprint, and technical service capabilities provide durable advantages, yet where specialized regional players and product-focused specialists retain meaningful share through customization and rapid turnaround.
Within this framework, the analysis examines how supply portfolios split across ink technologies and auxiliary materials. Solvent-based chemistries continue to hold a prominent position, reflecting entrenched manufacturing workflows and cost-performance expectations in established production lines. At the same time, UV-curable systems are steadily gaining relevance as throughput requirements intensify and cure-on-demand workflows reduce energy and solvent management burdens in controlled factory environments. Ceramic formulations and other specialized ink categories occupy a smaller but strategically significant role, particularly where marking durability, thermal exposure, and surface compatibility are decisive. The report evaluates how these type-level dynamics influence supplier negotiations, inventory strategies, and substitution risks across different production contexts.
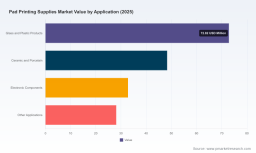
On the application side, the research dissects the demand architecture across major end-use categories. Glass and plastic products represent a substantial portion of the addressable market, consistent with the versatility of pad printing on non-flat surfaces and the enduring need for labeling, logo replication, and identification across consumer and industrial goods. Ceramic and porcelain applications form another significant pillar, driven by tableware, sanitaryware, and decorative goods manufacturers that demand inks capable of bonding to glazed and unglazed surfaces under varied curing conditions. Electronic components constitute an increasingly important niche, where miniature print fidelity, material compatibility, and traceability requirements push suppliers toward tighter process control and more specialized consumables. A broader set of remaining applications rounds out the demand matrix, illustrating how pad printing continues to migrate into adjacent use cases. The study deliberately avoids one-dimensional allocation tables, instead framing each application segment through operational requirements, regulatory exposure, and growth sensitivity to macroeconomic demand cycles.
Regional Divergence and Supply Chain Realities
Geographic context is indispensable for understanding where growth is being generated and how supply chains are adapting. The report profiles the Pad Printing Supplies Market across five major regional clusters: North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents a distinct combination of manufacturing density, regulatory posture, distributor infrastructure, and end-user purchasing behavior.
North America reflects a mature demand environment supported by a broad base of industrial decorators, packaging specialists, and contract manufacturers who prioritize reliability, service responsiveness, and compliance documentation. European operations are shaped by stringent chemical legislation, high labor costs, and an industry that increasingly rewards sustainable formulators and suppliers with traceable quality systems. Asia Pacific combines the most expansive manufacturing backdrop with rapidly evolving automation adoption, making it a region where volume, localization, and price competitiveness intersect with rising quality expectations. Latin America and the Mideast and Africa represent smaller yet strategically relevant markets, where import dependency, freight variability, and selective industrial growth patterns influence both supplier entry decisions and procurement timing.
Pad Printing Supplies Market
Worldwide Specialty Ink Market
Rather than reducing these dynamics to static share figures, the study assesses how regional differences alter lead-time risk, inventory buffering, formulation requirements, and aftermarket service expectations. The result is a practical decision tool for companies evaluating distribution expansion, localized stocking, or cross-border sourcing adjustments as the forecast period unfolds.
Competitive Landscape: Eight Companies Setting Different Standards
No market assessment is complete without a grounded view of the competitors actually shaping supply. The Pad Printing Supplies Market is populated by firms that compete on different axes: comprehensive consumables portfolios, machine and tooling integration, eco-certification leadership, and regional distribution scale. The research report profiles eight companies that exemplify these strategic postures and influence buying expectations across multiple segments.
TAMPOPRINT AG, headquartered in Germany, structures its offering around a complete pad printing consumables line, including inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production. This breadth positions the company as a one-stop resource for operations that prefer consolidated specification and reduced vendor fragmentation. INX International, based in the United States, emphasizes performance and regulatory alignment through its INXPad T200 solvent-based and UV pad printing inks. Its eco-formulations are designed to be free from phthalates and BPA, targeting packaging and product decoration environments where compliance documentation carries commercial weight. Marabu Druckfarben, also German, maintains a wide range of solvent-based and UV-curable pad printing inks focused on industrial decoration, marking, and identification, appealing to users with high repeatability requirements across varied substrate types.
Teca-Print USA, operating from the United States, concentrates on consumables supported by custom-mixed inks, printing pads, cliché plates, and full automation support, making it relevant for shops moving from manual to semi-automated workflows. Inkcups Now Corporation, likewise U.S.-based, has built visibility around ink cups, ceramic rings, and eco-responsible ink systems, including its SB Eco Series certified under GOTS and compliant with REACH and RoHS. Printex USA rounds out the equipment-plus-consumables profile by offering custom pad printing machines, tooling, fixtures, and consumables tailored for high-volume automated applications. ITW Trans Tech provides a full range of pad printing machines, fixtures, inks, pads, and printing plates, reinforced by what is described as the largest North American ink warehouse, a structural advantage for customers sensitive to replenishment speed. Boston Industrial Solutions differentiates through in-house silicone pads, inks, plates, fixtures, and accessories, allowing tighter control over the physical interface between pad, ink film, and substrate.
Regulatory Change as a Demand-Shaping Force
Regulatory and certification developments are no longer peripheral concerns in this market; they actively redirect procurement decisions and product roadmaps. A March 2025 milestone underscores this shift, when seven inks in the SB Eco Series achieved GOTS certification, reinforcing the broader movement toward formulations free from naphtha, PAH, and cyclohexanone while satisfying REACH, RoHS, and EN 71-3. This trajectory matters because it alters the qualification threshold for suppliers serving consumer-facing and regulated product categories.
A September 2025 product launch further illustrates how performance and compliance are being engineered together. The introduction of INXPad T200 solvent-based pad printing inks at K 2025 highlighted a sustainable system intended to enable recycling of recovered packaging materials while delivering high durability for toys, electronics, automotive, and promotional items. Equally important, these inks are described as free from phthalates and BPA and suitable for printing onto the non-food contact side of packaging, with compliance spanning REACH, RoHS, the Swiss Ordinance, the Toy Safety Directive, the GADSL list, and the EuPIA Exclusion Policy. Marabu has similarly aligned its pad printing inks with REACH and RoHS requirements, while broader industry references point to ISO 9001 and ISO 14001 certified ink lines with medical-grade biocompatibility testing, as well as eco-certified consumables validated under Eco-Passport, CLP/GHS, EN 71-3, REACH, and RoHS. These developments are not isolated; they signal that chemical stewardship, traceability, and certification readiness are increasingly part of the baseline commercial evaluation.
Inside the Research: What Decision-Makers Can Use Immediately
The strategic value of this report lies in its operational specificity. It is designed not only to explain market direction but to support concrete choices in sourcing, forecasting, and competitive positioning. Readers can expect a structured analysis that moves from macro trajectory to actionable segmentation intelligence, while preserving the analytical discipline needed to avoid overgeneralizing across diverse end-use contexts.
Key components include:
- A historical-to-forecast revenue assessment that benchmarks the current cycle and clarifies the pace of expansion through 2032.
- Systematic coverage of type-level dynamics across solvent-based, UV-curable, ceramic, and other ink portfolios, framed by performance trade-offs and regulatory exposure.
- Application-level evaluation across glass and plastic products, ceramic and porcelain, electronic components, and other use cases, emphasizing operational requirements and demand sensitivity.
- Regional analysis that links localized manufacturing conditions, distribution logistics, and compliance expectations to procurement strategy.
- Competitive profiling of major suppliers with attention to product breadth, automation support, eco-certification, and service infrastructure.
- Structured tracking of recent developments, certifications, and regulatory alignments that are reshaping qualification criteria for consumables.
- Decision-oriented synthesis for capacity planning, vendor consolidation, formulation selection, and market-entry prioritization.
By balancing breadth with depth, the study avoids the common pitfall of presenting segmentation data in isolation. Instead, it connects type, application, and regional behavior to real procurement pressures, allowing users to interpret numbers within the operational context that actually drives purchasing decisions.
Why 2026 Demands a Sharper Market View
The 2026 decision environment will be defined by a combination of demand stability, formulation evolution, and compliance-driven qualification. With the total market projected to reach approximately US$198.38 million in 2026 and continue expanding toward US$267.3 million by 2032, the size of the opportunity is clear. The more difficult question for enterprise teams is where growth will accrue, which product categories will face substitution pressure, and how quickly regulatory expectations will alter approved-supplier lists. A 5.65 percent CAGR is not merely a headline statistic; it is a planning parameter that helps set expectations for revenue expansion, inventory investment, and R&D prioritization across the forecast window.
At the same time, market concentration around the top three and top five players indicates that scale and service reliability still matter. Enterprises that depend on just-in-time replenishment, tight color matching, or specialized pad and cliché performance will need to assess not only what suppliers offer today but how those suppliers are adapting to sustainability, documentation, and automation demands. The report's competitive and regulatory analysis is intended to support those evaluations with current evidence rather than assumptions.
From Insight to Action: Accessing the Full Intelligence
Pad printing may be a specialized process, but its consumables market reflects the same strategic truth facing most industrial supply sectors: performance, compliance, and supply continuity now intersect in ways that reward early, evidence-based positioning. The Pad Printing Supplies Market research report is designed to give executives, procurement teams, and market strategists that evidentiary base. It consolidates historical trajectory, forward-looking growth modeling, competitive profiling, and regulatory developments into a single analytical structure tailored to practical use.
To move from directional understanding to fully segmented, decision-grade intelligence, the complete dataset and detailed analytical breakdown are available through the published report. The full market size progression, segmentation coverage, regional interpretation, and company-level assessments provide the granularity needed for budgeting, sourcing strategy, and competitive response planning. For teams preparing 2026 initiatives, the report offers both the context to interpret market movement and the structured evidence to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com