

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Forging Presses Market Hits USD 208.45M in 2025, Poised for 4.3% CAGR to 2032

Navigating the Forging Presses Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation, driven by the dual imperatives of industrial decarbonization and the relentless demand for high-strength, precision-engineered components. At the heart of this evolution lies the forging presses market, a critical machinery segment that underpins automotive lightweighting, aerospace structural integrity, and heavy industrial capacity. As we move into 2026, enterprise leaders and capital equipment strategists require more than fragmented data points. They need a cohesive, forward-looking intelligence framework that maps market trajectories, competitive maneuvering, and technological inflection points. Our newly released Forging Presses Market research report delivers precisely that: a comprehensive, decision-ready blueprint designed to align capital allocation, R&D prioritization, and Supply Chain positioning with the realities of the coming decade.
Market Architecture and the 2026 Growth Trajectory
Understanding the forging presses market requires a clear view of its structural evolution over the past half-decade. The sector has demonstrated consistent expansion, with total market revenue climbing steadily from 2020 through 2025 as global industrialization, infrastructure investment, and advanced manufacturing adoption compounded demand. This historical momentum has established a robust foundation for the current forecast window, which extends through 2032. The baseline year of 2025 reflects a mature yet dynamically expanding market, and the trajectory projected for 2026 indicates a meaningful inflection in capital equipment orders, technological upgrades, and regional capacity realignment.
Forging Presses Market
Our analysis projects a compound annual growth rate of 4.3 percent across the forecast horizon. While this figure may appear moderate at first glance, it obscures a far more important narrative: growth is not uniformly distributed. It is concentrated in specific technology pathways, application verticals, and geographic corridors where regulatory pressure, energy economics, and labor constraints are simultaneously reshaping procurement behavior. The 2026 market milestone represents more than a numerical checkpoint. It signals a transition phase where legacy mechanical systems are being strategically supplemented or replaced by hydraulic and servo-driven platforms that offer precision, energy recovery, and automation compatibility. For executives evaluating capacity expansion, modernization cycles, or cross-border equipment sourcing, understanding the timing and sequencing of this transition is essential. The research unpacks the underlying drivers of this growth curve, mapping how macroeconomic indicators, raw Material cost structures, and plant-level efficiency mandates converge to influence purchasing decisions at the operational level.
Segmentation Dynamics: Where Value Is Being Created
A superficial reading of market size inevitably leads to misallocated resources. The Forging Presses Market is characterized by distinct segmentation layers, each with its own technology adoption cycles, end-user procurement logic, and competitive intensity. Mechanical forging systems continue to hold substantial share, particularly in high-volume production environments where throughput consistency and established maintenance ecosystems remain advantageous. Yet the hydraulic segment is capturing disproportionate attention from capital manufacturers and end-user engineering teams. This shift is not merely a preference for newer technology. It reflects a structural realignment toward applications demanding complex part geometries, variable tonnage control, and integration with downstream automated handling systems.
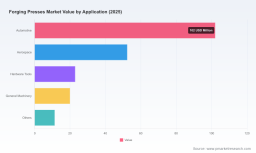
Application-side dynamics further illustrate where strategic focus is accumulating. Automotive manufacturing remains a primary demand engine, driven by the ongoing transition toward lighter structural components, electrification-compatible housing designs, and closed-die precision requirements. Aerospace demand sustains a parallel growth vector, with stringent material certification standards and fatigue-critical component specifications pushing forging specifications toward higher tonnage capabilities and tighter tolerance tolerances. Beyond these dominant verticals, hardware tools, general machinery, and specialized industrial applications contribute to a diversified demand base that buffers the market against cyclical downturns in any single sector. Regional demand patterns similarly reveal nuanced deployment strategies, with established industrial corridors sustaining steady replacement and upgrade cycles while emerging manufacturing hubs accelerate new capacity installations. Our report dissects these segmentation layers without reducing them to isolated percentages, instead presenting them as interacting forces that dictate pricing power, lead-time expectations, and technology roadmapping for equipment suppliers and buyers alike.
Competitive Landscape and Strategic Positioning
The forging presses market is defined by a concentrated yet highly differentiated competitive field. Leading manufacturers are no longer competing solely on tonnage ratings or unit pricing. They are competing on system integration, energy performance, automation readiness, and aftermarket service ecosystems. Our competitive analysis maps the strategic profiles of the sector's most influential players, tracing how each organization is positioning itself across mechanical, hydraulic, and hybrid technology pathways.
Cold Forging Machine Market
North American manufacturers maintain a strong footprint by emphasizing custom engineering, application-specific configurations, and responsive service networks. Companies such as Beckwood Press Company and Ajax-Ceco Machinery have built enduring reputations around hydraulic solutions tailored to both open-die and closed-die operations, with capacity ranges that address mid-to-large industrial requirements. Verson, operating within the broader SMS Group portfolio, provides a diversified offering spanning mechanical, hydraulic, and servo configurations, enabling end-users to align press specifications with variable production targets. Stamtec and C.W. Bear Company reinforce the segment's breadth by supplying mechanical, cold, and warm-hot forging solutions alongside supporting metal forming equipment. Distributors and component specialists such as L.T. Rogers Company and C.E. Johns & Co. play essential roles in sustaining ecosystem resilience, ensuring that legacy installations can be upgraded, maintained, and retrofitted as technology standards advance. National Forging Company and The Precision Hydraulic Press Co. further illustrate the market's dual identity as both an equipment manufacturing space and an operational service environment, while Hydro Punch Press Inc. and Sintokogio America Inc. address specialized forming and heavy industrial requirements. Jier Machine Tool and Macrodyne round out the competitive field with large-capacity hydraulic and servo solutions, the latter extending its reach into ultra-high-tonnage applications that serve extreme industrial demands.
International players are equally reshaping market expectations. Schuler Group has emerged as a global reference point for hydraulic and hybrid press architectures, leveraging advanced energy recovery systems and precision control frameworks to meet stringent European and global efficiency benchmarks. AIDA Engineering and Komatsu Industries contribute high-volume mechanical and servo capabilities that align with disciplined production cadence requirements, while SMS Group continues to expand its automation-integrated hydraulic press offerings for both open-die and closed-die environments. Fagor Arrasate reinforces the European supply base with forming machine expertise that complements broader press ecosystems. The result is a competitive landscape where differentiation is increasingly measured by engineering flexibility, environmental compliance, and lifecycle economics rather than hardware specifications alone.
Innovation Vectors and Recent Developments
Technology momentum in the forging presses market is accelerating, and recent developments provide a clear window into the direction of industry evolution. In July 2025, Maxiforja Group initiated production on the world's largest forging press delivered by ANDRITZ Schuler, incorporating a Kinetic Energy Recovering System that exemplifies the sector's move toward energy-conscious heavy manufacturing. Shortly thereafter, in October 2025, Schuler AG completed the delivery of its first full hybrid hydraulic-electric 4000-ton press to Audi Neckarsulm, achieving a 28 percent reduction in energy consumption. These milestones are not isolated engineering accomplishments. They demonstrate a broader industry pivot where energy recovery, hybrid actuation, and digital control integration are becoming procurement prerequisites rather than optional enhancements.
Also in October 2025, SMS Group successfully commissioned a fully automatic closed-die forging press at TZCO Chain Manufacturing in China, achieving throughput rates of up to 30 strokes per minute. This deployment underscores the growing importance of automation integration in high-cadence production environments, where labor constraints and consistency requirements are pushing manufacturers toward fully automated press lines. More recently, in May 2026, Macrodyne participated in the Forging Industry Technical Conference, signaling continued engagement with end-users, engineering teams, and technology partners around next-generation hydraulic and servo press architectures. These developments collectively illustrate an industry that is simultaneously scaling capacity and compressing energy intensity, a duality that directly informs equipment selection criteria and capital planning timelines.
Structural Forces Reshaping Procurement and Investment
Beyond corporate announcements and tonnage milestones, several structural forces are redefining how forging presses are specified, purchased, and operated. Carbon steel continues to account for a significant share of raw material utilization within the forging sector, driven by its favorable balance of cost-effectiveness and mechanical strength. This material dependency influences not only component design but also press tonnage selection, die durability expectations, and maintenance scheduling. Equipment strategies that ignore material-specific forming behavior risk suboptimal lifecycle economics and increased downtime.
Regulatory and energy efficiency mandates are exerting equally powerful pressure. Industry guidance now expects forging press technologies to deliver energy consumption reductions in the range of 22 to 35 percent compared to conventional systems. This benchmark is reshaping vendor evaluation frameworks, as procurement teams increasingly factor operational energy costs, recovery capabilities, and control system efficiency into total cost of ownership calculations. Simultaneously, persistent labor shortages across forging operations are accelerating investment in automation, digital control systems, and semi-autonomous press lines. Plant operators are no longer treating automation as a future-state aspiration. They are implementing it as a near-term operational necessity to mitigate personnel constraints, stabilize production cadence, and reduce variability in part quality. These dynamics converge to create a market environment where equipment decisions must account for energy performance, labor economics, and material behavior in an integrated manner. Our report provides the analytical scaffolding required to evaluate these forces systematically, allowing decision-makers to anticipate procurement timing, technology adoption windows, and competitive response patterns.
What This Research Delivers for 2026 Decision-Making
The Forging Presses Market research is structured to translate complex market data into actionable strategic guidance. Rather than presenting static tables in isolation, the report integrates market sizing, segmentation logic, competitive profiling, and macro-industrial context into a unified decision framework. Readers will find detailed assessments of mechanical and hydraulic technology pathways, including adoption drivers, performance trade-offs, and lifecycle cost implications. The application-side analysis connects end-user requirements in automotive, aerospace, hardware tools, general machinery, and other industrial sectors to specific press configurations and procurement behavior. Regional market dynamics are examined through the lens of capacity deployment, demand maturity, and technology diffusion patterns, providing context for sourcing strategies and market-entry considerations.
The competitive analysis extends beyond company summaries to evaluate strategic positioning, technology emphasis, and ecosystem influence. Recent developments are contextualized within broader industry trends, enabling readers to distinguish between discrete events and structural shifts. Market concentration metrics are incorporated to illuminate the balance between established incumbents and specialized challengers, while raw material dependence, energy mandates, and labor dynamics are woven into the discussion of procurement and investment timing. Altogether, the report equips capital equipment manufacturers, end-user engineering teams, investors, and supply chain strategists with the insight needed to align product roadmaps, capacity planning, and vendor evaluation with the market's actual trajectory.
Accessing the Full Intelligence Framework
The forging presses market is entering a phase where strategic advantage will belong to organizations that can read technological signals, interpret demand shifts, and time capital decisions accordingly. This research is designed to provide that capability. It offers the depth required to support rigorous internal analysis and the structural clarity necessary to translate findings into operational planning. For leaders seeking comprehensive segmentation data, detailed company profiles, full forecast breakdowns, and integrated scenario analysis, the complete report is available for review. Access the full publication to equip your 2026 and beyond strategy with decision-grade market intelligence.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com