

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semiconductor Photomask Market to Hit $5.9B by 2032 with 5.8% CAGR

Navigating the Next Frontier: Strategic Insights into the Semiconductor Photomask Market (2026-2032)
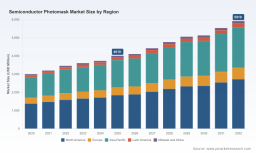
The semiconductor photomask market stands at a critical inflection point. As the foundational templates for lithography—the process that transfers circuit designs onto silicon wafers—photomasks are the unsung enablers of every advanced chip, from high-performance computing to next-generation displays. In 2025, the global photomask market reached an estimated $4,010 million, reflecting a steady upward trajectory from the $3,000 million recorded in 2020. Looking ahead, our latest research pegs the industry to surpass $5.9 billion by 2032, growing at a compound annual growth rate of 5.8 percent across the forecast period. These figures do more than chart revenue; they map the architectural backbone of a technology ecosystem under intense geopolitical, technological, and supply chain pressure.
For corporate strategists, investment committees, and procurement leaders, understanding why this market is expanding—and where the friction points lie—is no longer optional. This article serves as a strategic preview of our comprehensive Semiconductor Photomask Market research, outlining the analytical framework, competitive intelligence, and operational playbooks embedded in the full report. We invite you to explore how deep segmentation, scenario modeling, and regulatory mapping can transform high-level market awareness into actionable 2026 decision-making.
The Macro Trajectory: A Decade of Compound Growth Amid Structural Shifts
The historical data from 2020 through 2025 reveals a market that has proven remarkably resilient despite global chip shortages, capacity bottlenecks, and shifting demand cycles. Annual revenues climbed from $3,000 million in 2020 to $3,454.85 million in 2022, then accelerated further to $3,606.03 million in 2023 and $3,729.34 million in 2024. The $4,010 million baseline in 2025 underscores a structural acceleration rather than a cyclical rebound. Forecasts extend this momentum through 2032, projecting steady year-over-year gains that place the market well above $5,500 million by the end of the decade.
A 5.8 percent CAGR may appear measured against the explosive growth of some AI-driven semiconductor segments, but in the photomask world, it reflects something more profound: sustained capital expenditure in advanced logic and memory fabs, the proliferation of high-resolution display manufacturing, and the gradual migration of mature-node production into newer geographies. Our report dissects this trajectory across multiple dimensions, revealing where growth is concentrated, which application verticals are outpacing the baseline, and how product mix evolution is reshaping vendor economics. The narrative is not monolithic; it is a mosaic of converging demand signals that require precise navigation.
Navigating Regulatory Currents and Supply Chain Realities
No strategic assessment of the photomask industry in 2026 is complete without addressing the regulatory and supply chain environment. The landscape has grown increasingly complex, with policy interventions and material constraints actively reshaping cost structures, lead times, and geographic sourcing strategies.
On the regulatory front, the United States has intensified its focus on semiconductor supply chain security. A February 2025 executive order imposed a 25 percent tariff on semiconductors originating from China, a move that rippled through the broader electronics manufacturing ecosystem. By January 2026, the U.S. Commerce Department escalated its scrutiny with a proposed Section 232 investigation targeting semiconductor products, explicitly including photomask blanks. These actions occur alongside sustained dialogue between industry bodies and government agencies; for instance, the Semiconductor Industry Association submitted formal comments to the Bureau of Industry and Security in May 2025, addressing export controls and supply chain resilience.
Simultaneously, the U.S. CHIPS and Science Act has unlocked more than $52 billion in federal grants and tax incentives since its inception, catalyzing new fabrication capacity and, by extension, demand for high-quality photomask supply. These incentives are not distributed evenly across the value chain; they favor regions and technologies aligned with national security and advanced manufacturing priorities.
Beyond policy, operational realities are testing manufacturers. Supply chain constraints on high-purity quartz substrates and specialty materials were reported by 27 percent of manufacturers, introducing variability in lead times and cost predictability. Such constraints are not merely tactical inconveniences; they influence capacity planning, vendor selection, and the geographic distribution of production assets. Our report maps these dynamics in granular detail, offering a framework for assessing regulatory exposure, material dependency, and the strategic value of nearshoring or dual-sourcing arrangements.
Photomask Market
Competitive Architecture: Leaders, Moves, and Market Concentration
The photomask industry is characterized by a concentrated yet dynamic competitive structure. Our analysis indicates that the top three players collectively command approximately 45 percent of global revenue, while the top five entities account for roughly 60 percent. This concentration reflects the high barriers to entry associated with advanced lithography mask fabrication, stringent quality requirements, and the capital intensity of maintaining cutting-edge process capabilities. Yet within this consolidated landscape, strategic moves, geographic expansions, and technological investments are continuously reshaping the competitive equilibrium.
Among the most prominent players, Photronics Inc., headquartered in Brookfield, Connecticut, operates as a merchant leader providing integrated circuit and flat-panel display photomasks across eleven global facilities spanning North America, Asia, and Europe. In May 2026, the company reported second-quarter fiscal 2026 results that highlighted ongoing investments in U.S. and Korean facilities aimed at expanding advanced photomask capacity. This dual-region strategy underscores a broader industry trend: balancing proximity to leading-edge logic and memory clusters with the operational resilience offered by geographically distributed manufacturing footprints.
In Japan, Tekscend Photomask Corp.—rebranded from Toppan Photomask and based in Tokyo—has emerged as a global provider of semiconductor photomasks and related microfabrication products, maintaining facilities across Japan, the United States, Europe, and Asia. Tekscend's recent activity illustrates an aggressive capacity expansion posture. In October 2025, the company held a groundbreaking ceremony for a new photomask manufacturing facility in Singapore, designed to supply advanced precision photomasks to high-growth nodes. Just months later, in January 2026, Tekscend received a $15.2 million grant from the Texas government to expand its Round Rock facility by over 40 percent and create 50 new jobs. These parallel investments signal a deliberate strategy to position capacity closer to both North American and Asia-Pacific demand centers while capitalizing on regional incentive structures.
Dai Nippon Printing Co., Ltd., also headquartered in Tokyo, has focused its innovation pipeline on photomasks for advanced extreme ultraviolet (EUV) lithography nodes, including 3nm and 2nm process technologies. As EUV continues to define the frontier of logic scaling, suppliers capable of delivering masks with the requisite pattern fidelity, defect control, and material performance gain strategic leverage in the value chain. Hoya Corporation, another Tokyo-based leader, dominates the supply of EUV mask blanks and photomask blanks, occupying a critical upstream position that influences the entire mask fabrication ecosystem. Broadly, Hoya's position reflects the reality that blank quality and availability are gating factors for downstream mask makers, linking material science directly to lithography yield.
Rounding out the competitive set, SK-Electronics Co., Ltd., based in Seongnam, South Korea, stands as a major supplier of semiconductor photomasks and mask blanks, reinforcing the importance of Korean manufacturing ecosystems in the global photomask supply chain. Collectively, these players demonstrate that competitive advantage in this market is not simply a function of scale; it is increasingly defined by technological readiness for next-generation nodes, geographic alignment with fab expansion, and the ability to navigate regulatory and material constraints without compromising delivery.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
Our Semiconductor Photomask Market research is structured to move beyond high-level market sizing and into the operational and strategic details that decision-makers require. The report integrates historical performance data, forward-looking forecasts, and a multi-dimensional segmentation framework that allows readers to isolate growth drivers, assess risk exposures, and benchmark competitive positioning. Below is a preview of the core components embedded in the full analysis.
Segmentation by Region: Geographic Demand and Incentive Landscapes
The regional breakdown of market activity provides essential context for capacity siting, sourcing strategies, and competitive targeting. Northern America represents the largest revenue concentration, followed by Asia Pacific, which captures the second-largest share of global activity. Europe, Latin America, and the Middle East and Africa collectively account for the remaining portion, with distinct growth profiles and policy environments. Rather than presenting static percentage allocations, the report examines how regional demand patterns intersect with fab investment cycles, incentive programs such as the CHIPS Act, and the geographic placement of mask fabrication and blank supply assets. This lens helps strategists identify where demand is likely to outpace local supply and where partnership or capacity expansion opportunities may emerge.
Segmentation by Type: Reticle, Master, and Supporting Products
The product mix dimension is central to understanding vendor economics and technology roadmaps. Reticle-type photomasks command the highest revenue share, reflecting their critical role in high-volume manufacturing of integrated circuits. Master masks and other product categories contribute meaningful revenue streams, often serving specialized applications or acting as enabling inputs for next-generation processes. The report analyzes how the relative weight of each product category is evolving as node scaling, multi-patterning requirements, and display manufacturing demands shift the demand mix. This analysis is particularly valuable for suppliers evaluating portfolio prioritization and for buyers assessing long-term supply reliability across mask types.
Segmentation by Application: End-Market Demand Drivers
Demand for photomasks is ultimately anchored in the end markets they enable. Display manufacturing represents the largest application vertical, driven by the ongoing transition to high-resolution panels and advanced organic light-emitting diode technologies. Discrete components and optical devices form the next tier of demand, each with distinct technology roadmaps and procurement cycles. Microelectromechanical systems, while smaller in aggregate revenue, represent a high-precision segment where mask quality directly affects device performance. The full report examines how these application segments are expected to grow over the forecast period, what differentiates their pricing and specification dynamics, and how shifts in consumer electronics, automotive, and industrial demand translate into photomask order books.
Competitive Profiling and Tactical Intelligence
Beyond company-level profiles, the report synthesizes recent developments, facility investments, and strategic announcements to build a living map of competitive intent. Coverage includes expansion grants, new facility groundbreakings, equipment installation milestones, and financial reporting highlights that reveal where leading players are allocating capital. For example, the report contextualizes Tekscend Photomask's dual expansion in Texas and Singapore alongside Photronics' investments in U.S. and Korean facilities, using these moves to illuminate broader themes such as regional incentive capture, capacity localization, and node-specific capability building. This competitive intelligence is designed to support supplier selection, partnership evaluation, and strategic positioning exercises.
Translating Intelligence into 2026 Action Plans
Market research delivers value only when it is operationalized. Our report is built with that principle in mind, offering analytical structures that can be integrated directly into corporate strategy workflows. For capacity planners and procurement leaders, the segmentation frameworks provide a basis for demand forecasting, supplier diversification, and lead-time risk management—particularly important given the reported material constraints and the evolving regulatory environment. For investors and corporate development teams, the competitive profiling and growth trajectory analysis offer a foundation for evaluating market entry feasibility, partnership structures, and the strategic implications of concentration dynamics.
For executives monitoring geopolitical risk, the report's integration of policy actions—from tariff impositions and Section 232 investigations to export control discussions and incentive program impacts—creates a scenario-ready view of how regulatory shifts could affect cost structures, sourcing options, and regional competitiveness. This is not a static snapshot; it is a structured assessment that can be calibrated as policy trajectories and material supply conditions evolve.
Why the Full Intelligence Package Matters
The preview provided here captures the analytical architecture and strategic relevance of our Semiconductor Photomask Market research, but the complete report contains the detailed segmentation data, company-level profiling, scenario analysis, and forward-looking forecasts that enable precise decision-making. The macro numbers—$4,010 million in 2025, a 5.8 percent CAGR, and a projected $5,919 million market size by 2032—set the stage. The real strategic advantage lies in understanding where growth concentrates, how competitive moves reshape supply dynamics, and which regulatory and material risks demand proactive mitigation.
Semiconductor Photomask Market
To access the complete segmentation breakdowns, in-depth company profiles, regulatory impact assessments, and forecast models that power these insights, we invite you to explore the full research on our website. The report is designed for leaders who need more than a market overview—they need a decision-grade intelligence framework aligned with the realities of 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Semiconductor Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com