

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Electric Scooters Market Hits $38.23B in 2025, Forecasts 9.81% CAGR to 2032

Strategic Horizons for the Electric Scooter Market: Navigating Growth Through 2032
The urban mobility landscape is undergoing a seismic shift, driven by the dual imperatives of decarbonization and last-mile efficiency. Electric scooters, once viewed as niche recreational devices, have matured into integral components of the global transportation ecosystem. For stakeholders operating within this dynamic sector, understanding the trajectory of market expansion is not merely an exercise in forecasting it is a prerequisite for strategic positioning. Our latest comprehensive market research on the Electric Scooter Market offers a granular examination of the forces shaping industry outcomes from 2026 through 2032, providing executives, investors, and policymakers with the intelligence needed to navigate an increasingly complex competitive environment.
Electric Scooters Market
This analysis is built upon a rigorous evaluation of historical performance spanning 2020 to 2025, extending forward through a seven-year forecast period. The data reveals a market characterized by robust structural momentum, with a compound annual growth rate of 9.81 percent projected across the evaluation window. This sustained upward trajectory reflects deepening consumer adoption, expanding commercial deployment, and the convergence of supportive regulatory frameworks with technological maturation. Yet beneath these headline figures lies a far more intricate reality, one defined by regional asymmetries, product segmentation shifts, and intensifying competitive pressures that demand nuanced strategic responses.
Market Trajectory and Core Dynamics
The electric scooter sector has demonstrated remarkable resilience and expansion potential over the past half-decade. Revenue valuations have progressed from a baseline of 24.32 billion USD in 2020, climbing through successive growth phases to reach 38.23 billion USD by 2025. This historical arc establishes a credible foundation for near-term projections, with valuations anticipated to breach 41.58 billion USD in 2026 and continue their ascent toward 73.5 billion USD by 2032. Such growth is neither accidental nor uniform. It emerges from the interplay of urbanization pressures, infrastructural investments, evolving consumer preferences, and the strategic maneuvering of manufacturers seeking to capture share within an increasingly crowded arena.
Several macro force are propelling this expansion. Urban congestion in megacities has accelerated demand for compact, zero-emission alternatives to traditional motorized transport. Municipalities worldwide are integrating micromobility into broader transit networks, recognizing the role that electric scooters play in bridging gaps between mass transit hubs and final destinations. Simultaneously, advancements in battery chemistry, motor efficiency, and connected vehicle technologies have elevated product reliability and user experience, addressing earlier adoption barriers related to range anxiety and maintenance complexity.
However, growth is not without friction. Regulatory interventions have introduced new layers of complexity for market participants. Trade policy adjustments, including the imposition of significant tariffs on electric scooters imported from China, have reshaped supply chain considerations and prompted manufacturers to reevaluate sourcing strategies and regional production footprints. Concurrently, evolving standards governing lithium-ion battery transport, storage, and recycling impose compliance obligations that influence product design, logistics, and total cost structures. These dynamics underscore the necessity of proactive regulatory intelligence as a core competency for organizations operating in this space.
Segmentation Architectures and Demand Drivers
A superficial glance at aggregate market figures obscures the divergent growth patterns unfolding across product categories, end-use verticals, and geographic corridors. Understanding these sub-market dynamics is essential for allocating capital efficiently, tailoring product roadmaps, and identifying white-space opportunities that remain underserved by current competitive offerings.
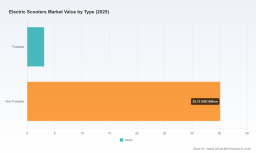
Product architecture continues to bifurcate between foldable and non-foldable designs, each addressing distinct user requirements and deployment contexts. Foldable configurations prioritize portability and multi-modal integration, appealing to commuters who combine scooter usage with public transit. Non-foldable variants, by contrast, emphasize structural robustness, payload capacity, and extended range, catering to applications where stability and durability outweigh portability concerns. The relative performance of these segments reflects broader shifts in consumer lifestyle patterns and commercial fleet requirements, with implications for manufacturing specialization and inventory strategy.
Application-wise, the market divides between personal use and commercial deployment, each following distinct adoption curves and value propositions. Personal use remains anchored in consumer preference for convenient, low-cost, environmentally conscious mobility solutions. Commercial applications, spanning last-mile delivery fleets, shared micromobility programs operated by municipal authorities or private operators, and corporate campus transportation, introduce additional dimensions of scale, utilization efficiency, and total cost of ownership. The interplay between these application verticals shapes demand volatility, pricing architecture, and the extent to which manufacturers can pursue differentiated value chains.
Geographically, market performance varies substantially, reflecting differences in urban density, regulatory environments, infrastructure maturity, and cultural acceptance of micromobility. Certain regions exhibit accelerated penetration rates driven by aggressive public-sector support and dense urban form, while others progress more incrementally as infrastructure catch-up and consumer education remain ongoing processes. These spatial divergences create heterogeneous opportunity landscapes, requiring market entrants and incumbents alike to calibrate their regional strategies with precision rather than relying on one-size-fits-all expansion models.
Competitive Landscape: Navigating an Increasingly Crowded Field
The electric scooter market is defined by a concentration of established players alongside a steady influx of new entrants, each leveraging distinct technological capabilities, brand positioning, and operational models to capture share. Our research maps this competitive terrain in detail, examining the strategic postures of leading manufacturers and shared mobility operators whose actions collectively shape market direction.
Among the prominent hardware manufacturers, several Chinese-based companies have built formidable portfolios emphasizing range, connectivity, and performance versatility. Segway-Ninebot continues to expand its E-series and Max series offerings, with recent product introductions at CES 2026 highlighting updated battery technologies and cross-platform integration between e-bikes and e-scooters. NIU International has reinforced its position through the KQi series and lightweight variants that blend integrated connectivity with extended range options tailored for urban environments. Yadea Technology Group broadens its footprint by spanning electric two-wheeler scooters and motorcycles, leveraging advanced battery and motor systems that serve both personal and commercial end markets. Kaabo has carved a niche in the heavy-duty off-road segment, deploying high-capacity batteries and high-output motors that appeal to enthusiasts and specialized commercial users alike.
The Indian market has emerged as a particularly dynamic theater of innovation and scale. TVS Motor Company has continued to refine its Orbiter and Star Series e-scooters, with the 2026 release of the TVS X model introducing ABS options and updated powertrain configurations aimed at mainstream commuting segments. Ather Energy has pursued a differentiated strategy centered on AI-optimized performance, swappable battery architectures, and telematics integration, positioning its Rizta and 450X models as technology-forward solutions for urban and last-mile transport. Ola Electric has scaled rapidly with its S1 Pro and S1 X scooters, emphasizing high-efficiency motors and fast-charging infrastructure designed to support both personal ownership and fleet applications. These Indian players benefit from a confluence of domestic demand, manufacturing scale, and aggressive product iteration that collectively intensifies competitive pressure across the broader market.
In North America, a diverse set of manufacturers and operators addresses varying consumer and institutional requirements. Apollo Scooters and Gotrax serve commuter segments with solid-tire designs, extended battery life, and foldable configurations that balance affordability with reliability. Navee and VMAX have targeted higher-performance use cases, emphasizing 48V systems, hub-motor configurations, and range specifications that support daily transport and off-road capabilities. InMotion focuses on rugged terrain and payload capacity through high-peak-power models. LexGo has introduced dual-motor options that extend range and performance envelopes for urban and highway commuting contexts. These regional players operate within a regulatory environment shaped by evolving customs policies and battery transport standards, making supply chain agility and compliance readiness critical differentiators.
The shared mobility segment introduces an additional competitive dimension, with operators such as Lime, Bird, Spin, Veo, and Gogoro deploying dockless or fleet-based models tailored to citywide micromobility programs and municipal partnerships. These companies emphasize utilization efficiency, battery-swapping ecosystems, and customized fleet solutions that align with urban transportation authority requirements. Their competitive calculus differs from hardware manufacturers, prioritizing operational economics, regulatory relationships, and user acquisition over unit sales volume.
Market concentration data indicates that a relatively small number of firms command a substantial share of aggregate revenue, with CR3 and CR5 metrics reflecting meaningful consolidation at the top of the competitive pyramid. This concentration does not eliminate opportunities for specialized entrants, particularly those that can differentiate through technology, regional focus, or niche application expertise, but it does raise the stakes for market participants seeking to achieve scale and defend margins.
Regulatory and Supply-Side Currents
Strategic decision-making in the electric scooter market must account for a broad array of externalities that influence costs, product design, market access, and competitive dynamics. Regulatory frameworks are evolving rapidly across jurisdictions, and the implications extend far beyond compliance checklists.
Trade policy has emerged as a particularly salient factor. Recent tariff measures imposed on electric scooters imported from China, coupled with duties on lithium-ion battery components, have compelled manufacturers and distributors to reassess sourcing strategies, pricing architecture, and regional assembly considerations. Organizations that have developed flexible supply chain models, localized production capabilities, or diversified sourcing portfolios are better positioned to absorb policy-driven cost pressures while maintaining competitive pricing.
Battery-related regulations introduce additional complexity. Updated guidance on lithium battery marking, watt-hour rating requirements, and quantity limits for batteries packed with equipment impose new documentation and packaging obligations that influence logistics, warehousing, and cross-border movement. In parallel, recycling mandates in certain jurisdictions require elevated material recovery rates for battery components used in shared fleets, affecting total lifecycle costs and incentivizing investments in closed-loop material management.
Raw material dynamics further complicate the supply-side picture. Surging export volumes and values for lithium batteries reflect robust global demand for energy storage and electrified mobility, but they also introduce volatility considerations related to commodity pricing, capacity allocation, and geopolitical factors. Manufacturers that have secured long-term supply agreements, invested in battery technology differentiation, or developed partnerships with experienced component suppliers gain relative advantage in navigating these fluctuations.
Trip data collection and urban mobility monitoring efforts by transportation authorities provide increasingly granular visibility into usage patterns, trip lengths, and modal substitution effects. Access to such data, whether through public reporting or proprietary partnerships, enables operators and manufacturers to refine product specifications, optimize fleet deployment, and tailor marketing strategies to evidence-based usage insights rather than assumption-driven planning.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
This market research report is designed to translate complex market signals into structured, actionable intelligence. Beyond high-level sizing and growth projections, the analysis provides a detailed operational framework that supports strategic planning across multiple functional domains.
The report examines historical performance and forward-looking forecasts across the full evaluation period, grounding projections in transparent methodology while identifying inflection points, risk factors, and catalyst events that could alter trajectory. Segmentation analysis disaggregates demand by product architecture and application vertical, revealing where growth is accelerating, where saturation may emerge, and where unmet needs create openings for informed market entry. Geographic analysis maps regional performance differentials without reducing them to simplistic rankings, instead exploring the structural drivers that underpin divergent outcomes and the strategic implications for market access, partnership selection, and capacity deployment.
Hoverboard Scooters Market
Competitive profiling extends beyond descriptive summaries to assess strategic positioning, product portfolio coherence, recent launch activity, and the manner in which leading firms are responding to regulatory and supply-side pressures. Recent developments, including product introductions at major trade exhibitions, model refreshes targeting specific performance or range thresholds, and the expansion of model lineups by emerging brands, are contextualized within broader competitive dynamics to illustrate how incumbents and challengers are contesting market share.
Regulatory and supply-chain analysis is integrated throughout rather than treated as a standalone appendix, ensuring that decision-makers understand how policy developments, battery standards, recycling mandates, and trade measures interact with pricing, product design, and market entry timing. This integrated approach enables organizations to evaluate not only what the market is likely to do, but also where constraints and enablers will shape the feasible set of strategic choices.
For corporate strategists, the research supports scenarios around capacity investment, product portfolio optimization, and geographic prioritization. For investors, it provides a framework for assessing market attractiveness, competitive durability, and the risk-adjusted return profiles associated with different segments and regions. For policy-oriented readers, it illuminates the relationship between regulatory design, infrastructure development, and market outcomes, offering evidence that can inform program design and stakeholder coordination.
Conclusion: Prioritizing Precision in a High-Growth Market
The electric scooter market presents a compelling growth narrative, but growth alone does not guarantee competitive success. Organizations that thrive in this environment will be those that combine macro-level appreciation of market momentum with micro-level understanding of segmentation dynamics, competitive behavior, regulatory exposure, and supply-chain resilience. Aggregate figures provide necessary context, but they do not substitute for the granular intelligence required to allocate resources efficiently, position products effectively, and anticipate shifts before they become industry consensus.
This report offers that depth. It is structured to equip decision-makers with a comprehensive view of where the market stands, how it is evolving, and what strategic options are most likely to yield durable advantage through 2032. To access the full dataset, detailed segmentation breakdowns, regional performance analysis, competitive benchmarking, and the complete set of forecasts underpinning this analysis, we invite you to explore the full report on our platform. The complete intelligence package provides the precision necessary to convert market opportunity into executable strategy.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com