

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chitosan Market Hits $19.15M in 2025, Set to Reach $67.66M by 2032 at 19.76% CAGR

Navigating the Chitosan Revolution: Strategic Intelligence for 2026 and Beyond
The global chitosan market stands at a pivotal inflection point. What was once a niche biopolymer of interest primarily to academic researchers and specialized formulators has matured into a strategic commodity with cross-industry relevance. Over the past half decade, value creation has accelerated from below eight billion dollars in 2020 to nearly twenty billion dollars by 2025, reflecting a compound trajectory that places chitosan among the fastest expanding segments in the broader bio-based materials landscape. For corporate decision makers, procurement leaders, and innovation directors, this momentum is not merely a statistical curiosity. It signals shifting supply chains, evolving regulatory architectures, and the emergence of differentiated application platforms that will reward organizations equipped with precise, forward-looking intelligence.
This strategic briefing introduces our newly published Chitosan Market study, a comprehensive analytical resource designed to translate complex market dynamics into actionable decision frameworks for the 2026 planning cycle and beyond. Rather than offering static snapshots, the report constructs a living map of where value is concentrating, which application pipelines are transitioning from pilot to commercial scale, and how regulatory developments in key jurisdictions are rewriting the competitive calculus. By dissecting the structural forces that will shape the next seven years, this research empowers executives to allocate capital with greater precision, anticipate supply constraints before they materialize, and position product portfolios ahead of regulatory and consumer shifts.
The purpose of this overview is straightforward. We will outline the macro trajectory that frames the investment thesis, demystify the segmentation architecture that matters most to strategists, examine the competitive landscape through the lens of corporate positioning and recent strategic moves, and illustrate how regulatory tailwinds and raw material transitions are reshaping market access. Throughout, we maintain a deliberate focus on strategic implication over commodity data, reserving granular split-level figures for the full report. This approach ensures that decision makers encounter enough analytical depth to validate the rigor of our methodology while recognizing that precise, segment-level intelligence requires engagement with the complete publication.
The Growth Architecture: Translating Macro Momentum into Strategic Foresight
The expansion narrative underpinning the chitosan market is anchored in a sustained upward revenue curve that has outpaced many conventional biopolymer segments. Historical tracking from 2020 through 2025 reveals a market that has consistently compounded at rates reflecting both structural demand pull and incremental capacity deployment. By 2026, the top-line valuation is projected to clear the twenty-three billion dollar threshold, and the forecast horizon through 2032 points toward a market that will more than triple its current scale. A compound annual growth rate of 19.76 percent across the 2026 to 2032 window underscores a phase of accelerated commercialization rather than speculative hype.
For strategists, the critical takeaway is not the headline growth figure alone but what it implies about market maturation. At this velocity, demand is fragmenting across use cases with different risk profiles, regulatory exposures, and margin structures. Water treatment applications continue to anchor baseline procurement, while cosmetics and personal care formulations leverage chitosan's film-forming and bioactive credentials for premium positioning. Pharmaceutical and biomedical pathways are moving from controlled clinical exploration toward scaled manufacturing, and food and beverage sectors are testing clean-label and natural preservation synergies. This diversification means that aggregate growth obscures segment-level divergence in profitability, lead times, and supply chain resilience. The full report disentangles these dynamics, offering operational templates that differentiate between volume-driven commoditization and value-driven specialization.
Chitosan Market
The forecast period also invites scrutiny of inflection points that could compress or extend the growth trajectory. Capacity expansions, substitution risks from alternative biopolymers, and fluctuations in feedstock availability all feed into scenario planning. Our modeling framework integrates historical elasticity patterns with forward-looking supply logic, allowing decision makers to stress-test investment assumptions under multiple demand and cost environments. This is precisely the kind of structural insight that generic market summaries cannot provide, and it forms the analytical backbone of the complete study.
Segmentation as a Strategic Compass: Where Value Is Truly Concentrated
In high-growth biopolymer markets, segmentation is rarely a passive classification exercise. It is a diagnostic tool that reveals where margins are defended, where innovation is accelerating, and where competitive intensity is reshaping pricing power. The chitosan market divides across source origins, application domains, and geographic footprints, but the real strategic question is how these dimensions interact to create defensible positions for individual firms and categories.
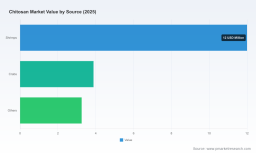
Source dynamics illustrate this complexity. Traditional crustacean-derived pathways remain dominant, with shrimp-processing byproducts supplying a substantial share of the feedstock base and crab-derived streams adding differentiated grade characteristics. Yet the source mix is undergoing quiet but meaningful re-architecture. Insect-derived production, particularly through black soldier fly feedstock systems, is scaling as a sustainable alternative that decouples supply from marine capture volatility and appeals to organizations prioritizing traceability and circular sourcing narratives. The full report evaluates the cost curves, scalability constraints, and regulatory acceptability of these alternative pathways, enabling sourcing strategists to map resilience against conventional marine dependency.
On the application side, the distribution of demand reflects a market in transition. Environmental applications, particularly water treatment, continue to command meaningful volume, but higher-value segments are growing their share of strategic attention. Cosmetic formulators are embedding chitosan into skincare architectures that emphasize barrier support and natural derivation. Pharmaceutical and biomedical developers are exploring drug delivery matrices, wound care platforms, and targeted therapeutic carriers. Food and beverage innovators are experimenting with preservation, clarification, and clean-label functionality. Each application pathway carries distinct qualification requirements, supplier qualification timelines, and margin expectations. Rather than presenting static split-level percentages that flatten these nuances, the report provides functional roadmaps that connect grade specifications, regulatory status, and commercialization readiness for each application cluster.
Geographic dispersion further complicates segmentation. Regional markets differ not only in absolute scale but in regulatory posture, processing infrastructure, and end-user procurement culture. Some regions are anchored by mature industrial ecosystems with established export channels, while others are emerging as demand centers fueled by localized formulation capacity and domestic sourcing incentives. By mapping regional dynamics through the lens of entry barriers, logistics friction, and partner availability, the study equips expansion planners with a structured view of where near-term traction is most achievable and where longer lead times are probable.
Competitive Dynamics: Positioning, Differentiation, and the 2025-2026 Strategic Chessboard
No market advancing at this pace can be understood without a clear view of the firms actively shaping it. The chitosan competitive landscape is characterized by a blend of established specialty producers, regionally anchored manufacturers, and emerging innovators pushing grade specialization and sustainable sourcing narratives. Concentration metrics indicate that a relatively small cluster of leading participants commands a meaningful share of total market value, with the top three firms holding roughly 42 percent and the top five collectively approaching 48 percent. This structure suggests that while scale players exert pricing gravity, there remains substantial room for differentiation by grade purity, application expertise, and supply reliability.
Worldwide Chitosan for Water and Waste Treatment Market
Several organizations exemplify the strategic postures now defining the sector. Primex EHF operates at industrial scale with a focus on high-purity pharmaceutical, food, and agricultural grades derived from crustacean shells, positioning itself as a supply reliability partner across multi-sector demand. Heppe Medical Chitosan GmbH emphasizes customized purity and formulation support for cosmetic, pharmaceutical, and medical applications, illustrating how technical service can function as a moat in grade-sensitive markets. KitoZyme S.A. has built a reputation around high-molecular-weight fungal and crustacean-derived chitosan for biomedical and industrial use, while simultaneously expanding its portfolio toward clean-label and sustainability-oriented applications. Advanced Biopolymers AS leverages its NovaMatrix brand architecture across wound care, drug delivery, and food-related use cases, demonstrating the commercial value of brand association in functionally complex categories.
Regional scalability is another recurring theme. BIO21 Co., Ltd. reflects Asia-Pacific manufacturing depth serving agriculture, food, and pharmaceutical end markets, while T.C. Bio Corporation and Zhejiang Golden-Shell Pharmaceutical Co., Ltd. represent China-based production capacity that supports both pharmaceutical-grade and industrial-grade export channels. Taizhou City Fengrun Biochemical Co., Ltd. specializes in high-quality chitosan targeted at cosmetics, food, and agriculture, underscoring the ongoing segmentation of Chinese supply around grade credibility. In North America, ChitoLytic, Inc. and Tidal Vision highlight a growing domestic emphasis on medical, food, agricultural, and industrial grades, with Tidal Vision particularly active in bios stimulant and crop defense solutions. Entoplast introduces an alternative sourcing narrative through insect-derived chitin and chitosan, and Chitinor AS reinforces the appeal of Arctic-sourced pharmaceutical and food-grade material. These profiles are not merely company summaries; they are archetypes that reveal how firms are choosing to compete on scale, purity, sustainability, or application specificity.
Recent developments in 2025 and 2026 make these strategic choices especially visible. Tidal Vision advanced its regenerative agriculture agenda with the Canadian launch of chitosan-based seed treatment and bio-stimulant products, reinforcing a positioning at the intersection of crop performance and sustainable input substitution. Iterro Life Sciences introduced a commercially available chitosan formulation designed for inhaled drug delivery, a milestone that signals how biomedical applications can move from laboratory promise to market-access reality. KitoZyme expanded its clean-label and sustainable application range, aligning product architecture with consumer-facing sustainability expectations. Golden-Shell Pharmaceutical pursued distribution partnerships aimed at broadening availability in emerging markets, a move that illustrates how established producers are extending reach without necessarily building new manufacturing footprints. On the regulatory front, the USDA Agricultural Marketing Service advanced a May 2026 NOSB Subcommittee Proposal and Technical Report evaluating chitosan as a nonsynthetic substance for inclusion on the National List for organic crop production as a pesticide, with a full vote anticipated in spring 2026. Simultaneously, EFSA-related reviews have kept chitosan and chitosan hydrochloride under assessment as basic plant protection substances in the EU, with renewal pathways under ongoing evaluation. These developments are not peripheral noise. They are strategic signals that can alter demand timing, qualification requirements, and competitive access across multiple application segments.
Regulatory Tailwinds, Raw Material Realities, and Strategic Implications for 2026
Regulatory architecture is increasingly a determinant of market velocity rather than a compliance afterthought. In the chitosan space, the classification debates unfolding in North America and Europe carry direct consequences for application eligibility, labeling strategy, and the speed with which new use cases can scale. The possibility that chitosan could secure a nonsynthetic classification under organic crop production frameworks in the United States would materially broaden its addressable base among organic growers and input formulators seeking compliant alternatives to synthetic pesticides. The EU context, with its focus on basic substance approval and periodic review cycles, introduces a parallel layer of procedural complexity that can affect product development timelines and market entry sequencing. Our report maps these regulatory threads against application roadmaps so that teams can anticipate qualification steps, budget for approval lead times, and design portfolio strategies that are robust to procedural uncertainty.
Raw material dynamics are equally consequential. Because chitosan is predominantly extracted from marine shellfish exoskeletons as a byproduct of seafood processing, its supply logic is intertwined with crustacean aquaculture output and capture fisheries volumes. This linkage creates both opportunities and vulnerabilities. On one hand, integrated byproduct utilization can strengthen cost efficiency and circular sourcing narratives. On the other, feedstock availability can fluctuate with harvest cycles, processing throughput, and regional supply chain disruptions. The expanding role of insect-derived chitin and chitosan, enabled by black soldier fly feedstock processes, is reshaping the strategic conversation around supply diversification. For firms seeking to reduce exposure to marine feedstock variability or to meet stakeholder expectations around alternative sourcing, this pathway is moving from conceptual interest to commercially relevant option. The full report assesses the scalability, cost dynamics, and certification considerations that will determine how quickly these alternative streams can complement or substitute for traditional marine inputs.
Taken together, the regulatory and raw material environments point to a market where strategic advantage will accrue to organizations that integrate compliance foresight with supply chain architecture. Companies that treat these factors as separate workstreams risk missing the interaction effects that shape real-world commercialization. For example, a change in organic certification status can alter downstream demand timing; a shift in feedstock availability can affect grade consistency or pricing stability; a new regional approval can unlock a previously constrained application but only if the right grade purity and documentation are in place. The research study is built to connect these dots, translating qualitative developments into decision-relevant frameworks rather than leaving them as isolated news items.
What the Full Study Delivers: Operational Intelligence for Executive Decision Making
The complete Chitosan Market research is designed as an executable intelligence platform rather than a static market description. It brings together historical performance tracking, forecast modeling, segmentation logic, competitive profiling, and regulatory mapping in a structure that supports both strategic planning and operational execution. Readers will find detailed analysis of demand trajectories across application domains, source-related supply considerations, and regional market characteristics that matter for expansion, sourcing, and partnership decisions. The report also provides structured evaluations of leading companies, recent product launches, distribution and partnership activity, and regulatory developments that are actively reshaping market access.
Beyond aggregate narrative, the study is built to support scenario-based thinking. Decision makers can use its frameworks to assess how changes in feedstock availability, regulatory classification, or application adoption speed could recalibrate growth expectations and competitive positioning. The inclusion of concentration analysis, recent developments, and company-level profiles allows stakeholders to benchmark their own strategies against the prevailing modes of competition, whether those modes emphasize industrial scale, grade specialization, sustainability positioning, or application-specific formulation capability. For teams evaluating market entry, capacity investment, supplier qualification, or portfolio expansion, the report offers a structured reference point that reduces reliance on fragmented assumptions.
Mapping the Road Ahead: Why This Research Matters for 2026 Strategy
The chitosan market is entering a phase where growth is increasingly tied to application credibility, regulatory alignment, and supply chain differentiation rather than to broad category momentum alone. That shift favors organizations that can read the market not just as a revenue curve but as a system of interacting demand drivers, sourcing constraints, compliance pathways, and competitive maneuvers. The compound trajectory projected through 2032 suggests opportunity, but sustained advantage will depend on the quality of strategic interpretation applied to that opportunity.
This strategic briefing has outlined the macro direction, the segmentation logic that matters, the competitive archetypes now in play, and the regulatory and raw material developments that will influence market access in the near term. It has also signaled the depth of operational content available in the full study, from forecast modeling to company-level positioning analysis and application-specific commercialization roadmaps. For executives preparing for 2026 and beyond, the central question is not whether chitosan represents a growing market, but how to engage with it in a way that aligns sourcing, product strategy, regulatory posture, and partnership choices with where value is genuinely concentrating. The complete report is designed to answer that question with the precision required for investment-grade decision making.
To access the full segmentation detail, competitive profiling, forecast scenarios, and regulatory mapping that support these strategic conclusions, we invite you to explore the complete Chitosan Market research on our platform. The publication provides the granular intelligence, functional roadmaps, and decision frameworks that turn high-level market momentum into concrete action plans.
For detailed analysis of this topic, please visit the official page: Chitosan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com