

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
5.5% CAGR and $5.4B Forecast: The Real Drivers Behind Foam Protective Packaging Market Growth
By pmarketresearch, 2026-09-21
The Foam Protective Packaging Market: Strategic Trends and Commercial Opportunities Amid a Shifting Landscape
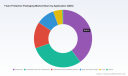
Foam protective packaging remains a foundational element in modern supply chains, providing cushioning, shock absorption, and thermal protection for products ranging from consumer electronics to medical devices. The market continues to expand at a steady pace, with revenue projected togrow from approximately USD 3,750 million in 2025 to around USD 5,442 million by 2032, reflecting a compound annual growth rate of roughly 5.5 percent over the 2026–2032 forecast period. This trajectory follows a decade of incremental but consistent expansion, with the sector moving from about USD 3,000 million in 2020 toward the mid-3,000 to low-4,000 million range by the mid-2020s. While the overall market does not experience explosive growth, its resilience stems from structural demand across diverse end-use sectors and the ongoing need to protect goods in increasingly complex logistics networks. For executives and investors, the critical question is not whether the market will grow, but how competitive dynamics, regulatory pressure, and technology shifts will reshape value creation within it.
Market Snapshot and Core Challenges
The current market environment is characterized by moderate growth, fragmented supplier landscapes, and intense pressure on traditional materials. Foam packaging benefits from broad application across electronics, automotive components, pharmaceuticals, consumer goods, and food, which helps distribute risk across multiple demand streams. However, this diversity also means that shifts in any one vertical can quickly alter regional or product-level dynamics. The market concentration among leading players remains moderate, with the top three firms accounting for just under half of total revenue and the top five capturing slightly more than half. This structure suggests that while scale advantages exist, there is still meaningful room for specialized suppliers and regional players to compete on customization, service, and niche material performance.
One of the most pressing challenges is the regulatory tightening around expanded polystyrene (EPS) and other foam materials. Multiple U.S. states have enacted or expanded EPS restrictions for food service and packaging applications, with New York’s expanded polystyrene ban taking effect in early 2026 and California imposing recycling-rate requirements on EPS food service ware producers. These measures create uncertainty for suppliers that rely heavily on conventional EPS, especially where recycled content alternatives are still maturing. At the same time, the industry is navigating raw material volatility and the cost implications of transitioning toward recycled, bio-based, or compostable formulations without compromising protective performance.
A second challenge lies in balancing customization with operational efficiency. Many end users require foam inserts, cushioning systems, and engineered packaging solutions tailored to specific product geometries and handling conditions. Yet highly customized production can strain margins and complicate scale operations. Suppliers must therefore decide how much to invest in flexible fabrication capabilities versus standardized, on-demand systems that can serve a broad customer base with minimal changeover. The tension between bespoke solutions and repeatable, efficient processes is reshaping product portfolios and capital allocation decisions across the sector.
Worldwide Mobile Phone Protective Cases Market
A third challenge is the growing expectation for sustainability credentials that do not sacrifice protection. Customers increasingly ask for packaging that reduces waste, supports recycling, or uses renewable content, but they still demand reliable shock protection and temperature assurance. Meeting both sets of requirements simultaneously forces manufacturers to refine material formulations, validate performance under real-world logistics conditions, and communicate environmental attributes transparently. In this environment, claims that are not backed by robust testing or verifiable supply-chain data can expose companies to reputational and compliance risk.
Key Drivers Shaping Market Dynamics
Technology innovation is a central force redefining what foam protective packaging can deliver. On-demand foam-in-place systems and semi-automated solutions are expanding the range of operations that can produce protective packaging close to the point of use, reducing storage needs and enabling faster response to order variability. Recent product updates, such as the launch of a semi-automated foam packaging system aimed at small-scale production with minimal maintenance, illustrate how equipment providers are lowering the threshold for adoption among smaller and mid-sized users. At the same time, advances in custom foam inserts and engineered cushioning continue to support high-value, sensitive applications where precision fit and shock performance are critical. These innovations are not merely incremental; they are changing the economics of how protection is produced, stored, and deployed across the supply chain.
Policy and regulatory developments are reshaping material choices and regional competitiveness. The expansion of EPS restrictions in multiple U.S. states is pushing manufacturers and brand owners to evaluate alternatives earlier in the product-design cycle, rather than treating regulatory compliance as a late-stage adjustment. In this context, recycled content strategies are gaining attention, with some formulations incorporating EPS recycled content at levels that vary by application and performance requirement. The availability of higher recycled-content options remains under development, but the direction of travel is clear: regulatory and customer pressure is accelerating the shift toward materials and designs that can demonstrate reduced environmental footprint while maintaining protective function. For suppliers, the ability to offer compliant, validated alternatives is becoming a competitive differentiator, especially in regions where mandates are already in force.
Demand-side behavior is also evolving as companies re-examine damage reduction, logistics efficiency, and sustainability goals together. Packaging damage is no longer viewed solely as a product-loss issue; it is increasingly treated as an operational and environmental problem that affects returns, replacements, and waste. Case examples in the market show how cushioning systems are being evaluated not just for protection but also for their contribution to broader operational and sustainability outcomes. This mindset is particularly relevant for high-volume distributors and e-commerce operators, where damage rates, labor time, and packaging waste all influence total cost. As a result, buyers are more likely to consider integrated cushioning solutions that combine reliable protection with compact storage, easier handling, and material attributes aligned with corporate sustainability targets.
Supply-chain and cost-structure changes are adding another layer of complexity. Energy inputs, resin pricing, and transportation costs all influence the competitiveness of foam-based solutions relative to alternative protective materials. Suppliers that can localize production, optimize material usage, and reduce changeover times are better positioned to manage cost variability. In parallel, consolidation among specialized manufacturers is altering the supply base, with acquisitions expanding capabilities from individual foam inserts to broader engineered packaging systems. These shifts are changing the bargaining dynamics between suppliers and large buyers, while also creating opportunities for partners that can offer end-to-end support across design, fabrication, and fulfillment.
Competitive Landscape and Leading Strategies
The competitive field in foam protective packaging spans large diversified providers, specialized foam manufacturers, and emerging players focused on sustainable or regenerative materials. Among the more prominent participants are companies with strong positions in foam-in-place systems, custom inserts, and engineered packaging solutions. Sealed Air Corporation has built recognition around on-demand cushioning systems, including expanding foam bags and equipment for blocking, bracing, and temperature assurance. Pregis LLC has emphasized foam-in-place cushioning platforms and custom foam inserts designed for shock protection and sustainability. Veritiv Corporation offers foam-in-place solutions for custom cushioning applications, while Foam Industries focuses on custom foam inserts, boxes, and complete engineered packaging systems. Specialty suppliers such as Foam Packaging Specialties and Protective Packaging Inc. concentrate on custom-fabricated foam packaging for delicate goods, semiconductor protection, and industrial or medical applications. Protective Packaging Solutions extends similar capabilities into industrial and medical shipping cases. Meanwhile, Cruz Foam has positioned itself around regenerative, compostable protective foam packaging for temperature-sensitive and fragile goods, and Storopack Hans Reichenecker GmbH offers protective foam solutions that include bio-based and high-performance options.
The strategic positioning of these leaders reflects different answers to the same underlying question: how to create value when protection, cost, and sustainability must be optimized together. Larger, more diversified players tend to compete on integrated systems, brand trust, and the ability to serve broad customer bases with standardized yet customizable solutions. Their recent activity underscores a push toward easier-to-deploy equipment and documented performance outcomes. For example, one major provider launched a semi-automated foam packaging system designed for smaller-scale production with low maintenance requirements, broadening the addressable market beyond large industrial users. Another leading player published a case study showing how a foam-in-place cushioning system helped convert packaging damage challenges into operational and sustainability gains for a major toilet distributor. These moves signal a focus on practical adoption, measurable outcomes, and the integration of protection with broader operational goals.
Specialized manufacturers, by contrast, often compete on depth of customization, material expertise, and the ability to serve technically demanding applications. The acquisition of one specialty supplier by another to expand from custom foam inserts to complete packaging systems illustrates how niche players are adding breadth to strengthen their value proposition. In high-sensitivity segments such as semiconductors, medical devices, and complex industrial components, the ability to engineer fit, cushioning density, and material behavior can matter more than scale alone. This creates a market structure in which both scale-oriented and specialty-oriented strategies can succeed, provided they are aligned with clear customer segments and validated performance claims.
Market evolution is likely to feature continued consolidation among smaller fabricators, alongside new entry from companies offering sustainable or regenerative foam alternatives. The regulatory environment and customer sustainability expectations are lowering barriers for innovators who can demonstrate credible environmental benefits without sacrificing protection. At the same time, established players are responding by expanding their own sustainable portfolios, including bio-based and high-performance options. The net effect is a competitive landscape that is becoming more pluralistic: scale players compete on system efficiency and reach, specialists compete on tailored performance, and sustainability-focused entrants compete on material differentiation. Companies that can bridge two or more of these positions—such as combining custom engineering with compliant, lower-impact materials—are likely to gain the strongest competitive traction.
Future Trends and Commercial Opportunities
Over the next three to five years, one clear trend is the accelerating integration of protection, sustainability, and operational efficiency into a single packaging decision. Buyers will increasingly favor solutions that reduce damage while also supporting waste reduction, recycling, or renewable content goals. This creates opportunities for suppliers that can provide validated, application-specific performance data alongside credible environmental attributes. Packaging decisions will be evaluated more holistically, with total cost of ownership—including damage, returns, labor, and disposal—becoming a central metric rather than unit price alone.
A second trend is the broadening adoption of on-demand and semi-automated foam systems across a wider range of operation sizes. As equipment becomes easier to deploy and maintain, smaller and mid-sized users can produce protective packaging closer to the point of use, reducing inventory and improving responsiveness. This opens new commercial avenues for equipment and material providers that can serve distributed production models, especially in regions where logistics complexity and order variability make centralized packaging less attractive. The opportunity here is not just in selling foam, but in enabling a more flexible protection model that aligns with changing fulfillment patterns.
A third trend is the continued material transition driven by regulation and customer preference, with recycled content, bio-based options, and compostable formulations gaining ground where performance allows. The direction of regulatory travel in multiple U.S. states suggests that compliance will increasingly be a baseline requirement rather than a differentiator. Suppliers that invest early in validated alternative materials and transparent documentation will be better positioned to retain customers through transitions. At the same time, uncertainty remains around the pace of recycled-content scaling, the performance trade-offs in certain applications, and the consistency of enforcement across jurisdictions. These uncertainties create both risk and opportunity: companies that can navigate material variation, demonstrate robust testing, and offer clear guidance will have an advantage in markets where buyers are under pressure to shift quickly.
PW Consulting
Strategic Actions for Decision Makers
For manufacturers and suppliers, the priority is to align product portfolios with the dual demands of protection and sustainability while improving operational flexibility. This means investing in material and equipment options that can serve both standard and custom applications, building validated performance data for alternative formulations, and reducing changeover complexity where possible. Companies should also evaluate where they can add value through integration—combining cushioning design, fabrication, and deployment support—rather than competing solely on material price. In a market where regulatory pressure and customer expectations are moving in the same direction, the ability to offer compliant, high-performing, and operationally efficient solutions will be a decisive advantage.
For investors, the most compelling opportunities lie in businesses that can demonstrate durable differentiation through either technical specialization, sustainable material leadership, or system-level efficiency. Given the moderate concentration of the market and the ongoing consolidation among specialty players, due diligence should focus on the durability of customer relationships, the credibility of sustainability claims, and the supplier’s ability to adapt to material and regulatory change. Investors should also watch for companies that are expanding from component supply into broader engineered packaging systems, as this shift can deepen customer lock-in and improve margin resilience. The key is to identify operators that are positioned not just for market growth, but for the more specific value shifts occurring within that growth.
For procurement and supply-chain leaders, the strategic imperative is to treat foam protective packaging as a total-cost and risk management decision rather than a commodity purchase. This involves comparing solutions on damage reduction, handling efficiency, storage footprint, and material compliance, while ensuring that sustainability claims are supported by verifiable data. Building partnerships with suppliers that can provide application-specific engineering, validated performance, and flexible production options can reduce exposure to damage-related losses and regulatory disruption. As mandates around EPS and other materials continue to expand, early engagement with alternative solutions will make it easier to manage transition risk without compromising protection standards.
The foam protective packaging market is entering a phase in which incremental growth is being reshaped by technology, regulation, and changing buyer expectations. Navigating this environment requires a clear understanding of where value is shifting—from straightforward material supply toward integrated, compliant, and operationally efficient protection solutions. For decision makers seeking detailed segmentation data, regional nuances, and tailored recommendations, a comprehensive market report provides the deeper intelligence needed to translate these strategic trends into concrete action.
Screen Protective Film Market
For detailed analysis of this topic, please visit the official page: Foam Protective Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The CMMS Software Market: Strategic Shifts and Commercial Opportunities in Asset Management
The computerized maintenance management system software market has entered a phase of accelerated evolution, driven by converging pressures around operational efficiency, technological maturity, and workforce constraints. From a base of approximately 215 million USD in 2025, the market is positioned to expand steadily through the end of the decade, reflecting a compound annual growth rate near 10.12 percent across the forecast horizon through 2032. This trajectory is not merely a function of incremental adoption; it signals a structural shift in how organizations approach asset lifecycle management, maintenance scheduling, and operational reliability. The transition from fragmented, paper-heavy workflows to integrated, data-driven maintenance platforms has reached a tipping point where scale, interoperability, and intelligent automation are becoming the baseline expectations rather than premium differentiators.
Behind the headline growth figures lie several inflection points that reshape how procurement teams, operations leaders, and investors should interpret the landscape. The market is no longer dominated by a single deployment paradigm or a narrow set of industrial verticals. Instead, organizations are navigating a complex trade-off between speed of implementation, long-term data sovereignty, and the ability to embed predictive capabilities into day-to-day maintenance routines. At the same time, labor cost dynamics continue to exert pressure on operational budgets, with maintenance technician labor representing a meaningful share of total operational expenses in manufacturing environments. These constraints are pushing organizations to seek software-enabled productivity gains, not simply digitization for its own sake. The result is a market where value creation depends less on feature checklists and more on how effectively platforms reduce unplanned downtime, standardize compliance workflows, and integrate with broader enterprise systems.
Market Snapshot: Scale, Structure, and Core Challenges
The overall market size has grown consistently from the early 2020s, with annual revenue progression reflecting broader enterprise software adoption cycles and the gradual normalization of cloud-first procurement. The 2025 baseline of 215 million USD serves as a reference point for understanding the pace of expansion into the late 2020s and early 2030s. Growth from 2026 onward accelerates as organizations complete initial migration waves and begin layering advanced functionality onto established maintenance workflows. The compound annual growth rate of 10.12 percent indicates a market that is expanding faster than general IT spending in many industrial sectors, but the growth is uneven across deployment models, use cases, and regional maturity levels.
Three core challenges define the current operating environment:
-
Deployment and data governance trade-offs. Organizations must balance the agility and lower upfront cost of cloud-based delivery against the control, latency, and regulatory requirements that still drive demand for on-premise or hybrid arrangements. The decision is no longer purely technical; it affects vendor lock-in, integration complexity, and long-term total cost of ownership.
-
Labor cost pressure and skills shortages. Rising labor expenses for maintenance technicians are forcing organizations to extract more output from existing teams. Software platforms that can standardize work orders, streamline scheduling, and reduce administrative overhead are increasingly viewed as operational necessities rather than optional tools.
-
Fragmented enterprise integration requirements. Maintenance does not operate in isolation. Asset data must connect with ERP, inventory, safety, and compliance systems. Platforms that fail to support clean data exchange or that require heavy customization struggle to scale beyond pilot deployments.
These challenges are not separate problems; they interact. A cloud-first deployment can reduce implementation friction, but only if the platform can integrate cleanly with existing enterprise systems and support the compliance posture of the organization. Likewise, labor cost pressures magnify the importance of usability and mobile access, since field technicians are unlikely to adopt tools that add complexity rather than reduce it. The market is therefore rewarding vendors that can simplify deployment while preserving flexibility, and penalizing those that force organizations into rigid implementation models.
Key Drivers Reshaping Demand and Value Creation
Technology Innovation and the Move Toward Intelligent Maintenance
The most consequential shift in the CMMS software market is the gradual embedding of advanced analytics, condition monitoring inputs, and AI-assisted decision support into maintenance workflows. Platforms are increasingly expected to move beyond scheduling and record-keeping toward predictive and prescriptive capabilities. This does not require every deployment to be fully AI-driven from day one, but it does raise the floor for what buyers consider viable. Solutions that can prioritize work orders based on asset criticality, surface recurring failure patterns, and reduce manual data entry are gaining preference over tools that simply digitize legacy processes. The practical impact is a narrowing gap between traditional CMMS functionality and broader enterprise asset management expectations, especially in environments where asset reliability directly affects production continuity and safety outcomes.
CMMS Software Market
Policy, Compliance, and Regulatory Expectations
Regulatory and standards-driven expectations continue to influence procurement decisions, particularly in sectors where equipment reliability intersects with safety, environmental compliance, or audit readiness. Maintenance records, inspection intervals, and corrective action tracking are increasingly subject to internal governance and external scrutiny. As a result, platforms that support documented workflows, traceability, and standardized reporting have an advantage in regulated contexts. This driver is less about sudden regulatory shocks and more about the cumulative effect of compliance becoming a permanent design requirement rather than a post-deployment add-on. Organizations are selecting platforms that can sustain auditable processes without heavy custom development, which in turn favors vendors with mature configuration options and clear data structures.
Demand-Side Behavior and the Operational Imperative
On the demand side, the dominant behavior change is the shift from reactive maintenance planning to more disciplined preventive and condition-informed approaches. This shift is being accelerated by the cost of unplanned downtime and the difficulty of scaling technician headcount quickly in tight labor markets. Maintenance teams are looking for systems that make it easier to standardize routines, capture asset history, and coordinate across shifts and sites. At the same time, executives are increasingly treating maintenance software as part of a broader operational resilience strategy. That means purchase decisions are less likely to be confined to the maintenance department alone and more likely to involve operations, finance, and IT stakeholders who evaluate the platform through the lens of total cost of ownership, uptime impact, and data usability.
Supply Chain and Cost Structure Dynamics
Cost structure changes in the broader industrial environment are also shaping purchasing behavior. Maintenance software buyers are more attentive to implementation effort, ongoing administration overhead, and the hidden costs of fragmented toolchains. In manufacturing and adjacent sectors, labor cost pressure has become a central consideration in vendor evaluation, since platforms that reduce coordination friction and improve first-time fix rates can meaningfully offset workforce expense. This is encouraging a preference for solutions that can be adopted incrementally, configured without extensive specialist dependence, and extended over time as organizational maturity grows. Cost is therefore not just a license or subscription question; it is increasingly a question of operational drag and change-management burden.
Competitive Landscape and Leading Strategies
The competitive environment reflects a mix of established enterprise players, specialist platforms, and vendors with strong positioning in particular deployment models or verticals. The market is moderately concentrated, with the largest firms holding meaningful but not overwhelming share. That structure leaves room for differentiation through product focus, deployment flexibility, vertical depth, and integration strategy rather than through price alone. Several strategic postures are visible across the field.
One clear pattern is the emphasis on AI-enabled asset operations and work order intelligence. Vendors in this group position their platforms as operational hubs that connect maintenance tasks, asset data, safety workflows, and integration points into a single interface. Their differentiation lies in reducing administrative effort, improving visibility into asset conditions, and making maintenance data more usable for planning and reliability teams. A second pattern centers on enterprise-grade mobility, compliance, and scale. These solutions target large operations where mobile access, standardized work orders, and auditable asset performance tracking matter as much as core scheduling functionality. Their value proposition is often tied to consistency across sites, support for complex organizational structures, and the ability to maintain governance over maintenance processes. A third pattern is cloud-native EAM/CMMS delivery aimed at multi-site and cross-industry use. These platforms emphasize accessibility, configuration breadth, and the ability to support asset and maintenance management without heavy on-premise infrastructure. They tend to compete on time-to-value, upgrade cadence, and the ease of scaling across locations.
Beyond these broad postures, several contextual shifts are shaping strategy. Recent product recognition for one of the incumbent platforms illustrates how analyst validation and sector reputation continue to influence buyer confidence, especially in procurement processes where risk aversion favors established names. At the same time, the market is not static. New entrants and adjacent platforms are expanding the definition of what a maintenance system can do, while larger portfolios are absorbing maintenance functionality into broader asset, facility, or workplace management offerings. IBM’s comprehensive CMMS/EAM orientation, for example, reflects the continued relevance of large-scale platforms that combine predictive maintenance emphasis with enterprise integration depth. Meanwhile, specialist vendors such as Aptean and AssetPoint highlight how tailored modules for manufacturers, scheduling, and supply chain linkage remain important in environments where maintenance cannot be separated from production planning or inventory dynamics.
The landscape is evolving along two simultaneous axes: consolidation and specialization. Consolidation is visible where buyers prefer fewer vendors, broader modules, and platforms that can cover maintenance, asset data, and adjacent workflows. Specialization persists where organizations need depth in particular verticals, mobile maintenance, or multi-site coordination. The most durable strategies appear to be those that combine a credible core maintenance experience with clear paths into integration, advanced analytics, and operational context. In practice, that means vendors must demonstrate not only that their system can manage work orders and assets, but also that it can fit into the way organizations actually run maintenance operations at scale.
Strategic Outlook: Three Trends Defining the Next Three to Five Years
Trend 1: Maintenance Platforms Become Reliability and Decision-Support Hubs
Over the next few years, CMMS software is likely to be evaluated less as a record-keeping system and more as an operational decision-support layer. The practical implication is that platforms will be expected to help prioritize interventions, connect maintenance data with asset performance indicators, and reduce the latency between issue detection and action. For commercial opportunities, this favors vendors that can make maintenance data immediately actionable without requiring extensive data science resources. It also creates room for solutions that can coordinate maintenance with inventory, parts availability, and scheduling constraints, since those factors often determine whether a work order is meaningful in practice.
Trend 2: Cloud-First Adoption Matures Into Integration-First Buying
Cloud adoption is already well underway, but the next phase of purchasing will increasingly emphasize integration quality, data portability, and fit with existing enterprise architecture. As organizations move past initial migration, the question shifts from where the software runs to how well it connects. This opens opportunities for platforms that offer clean APIs, prebuilt connectors, and configurable data models, especially for buyers who want to avoid prolonged customization cycles. It also raises the stakes for vendors that rely on heavy implementation services to make their tools viable, since integration friction can erode the cost and speed advantages that cloud delivery is supposed to provide.
Trend 3: Labor Economics Drive Productivity-Led Purchasing
Because maintenance labor represents a significant share of operational expenses in many industrial settings, buyers will continue to favor tools that directly improve technician productivity and reduce coordination waste. The commercial opportunity here is not simply selling software; it is proving that the platform can shorten administrative cycles, improve work order clarity, support mobile execution, and help teams manage more assets without proportionate headcount growth. This trend also raises the importance of change management and usability. Even strong platforms can underperform if they are difficult to adopt in daily field workflows, so vendors that invest in practical adoption paths are better positioned than those that rely on feature breadth alone.
These trends carry notable uncertainties. Adoption speed will depend on how quickly organizations can standardize asset data and overcome internal silos. The pace of advanced capability adoption may vary sharply between sectors, with some industries moving quickly toward predictive workflows while others remain focused on foundational discipline. Pricing pressure could intensify as buyers compare an expanding set of cloud options, and vendor differentiation may narrow if core maintenance features become commoditized. The organizations that benefit most will be those that treat CMMS software as part of a broader operating model transformation rather than a standalone IT purchase.
Actionable Implications for Decision Makers
For manufacturers and asset-intensive operators, the priority is to define maintenance maturity goals before evaluating tools. Platforms should be assessed against concrete operational outcomes such as reduced unplanned downtime, better work order closure quality, clearer asset history, and smoother coordination across sites or shifts. The most useful purchases are those that can be deployed incrementally, support mobile execution, and integrate with existing enterprise systems without extensive customization. Manufacturers should also weigh how well a solution can accommodate predictive and condition-informed workflows over time, since the platform selected today will shape how quickly advanced maintenance practices can be scaled tomorrow.
Preventive Maintenance Software Market
For investors and strategic analysts, the market rewards attention to integration strategy, deployment flexibility, and the ability to move upmarket without losing usability. The moderately concentrated structure suggests that share gains will likely come from clear product positioning and successful enterprise adoption rather than from broad commoditized competition. It is worth watching which vendors can convert cloud adoption into sticky, well-integrated deployments and which can demonstrate measurable productivity benefits in environments where labor costs and downtime risks are most acute. Differentiation in compliance support, multi-site coordination, and asset reliability workflows is likely to be more durable than differentiation in basic work order features alone.
PW Consulting
For procurement and IT leaders evaluating CMMS solutions, the practical question is whether the platform reduces operational friction or simply relocates it. Key evaluation criteria should include implementation burden, mobile usability for field staff, data model flexibility, integration readiness, and the vendor’s ability to support both immediate maintenance needs and longer-term reliability goals. Buyers should also consider how the vendor handles configuration, upgrades, and ongoing administration, since those factors often determine whether a deployment remains effective after the initial rollout. In markets where options are expanding, the differentiator is frequently not the presence of a feature but the ease with which the feature can be operationalized at scale.
For organizations seeking a more detailed view of segment-level dynamics, vendor positioning, and regional variation, a comprehensive market report can provide the granularity needed to translate these strategic themes into procurement plans, investment theses, and rollout roadmaps. Detailed breakdowns of deployment splits, application context, regional momentum, and vendor-specific developments help decision makers move from directional insight to execution-ready judgment. In a market where the pace of change is accelerating and the cost of poor selection is rising, the value of deeper intelligence lies in reducing uncertainty at the point of decision.
For detailed analysis of this topic, please visit the official page: Computerized Maintenance Management System (CMMS) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thaumatin Market 2032: Beyond the 7.5% CAGR—Sweetener Shifts Reshaping Growth
By pmarketresearch, 2026-09-21
The Thaumatin Market: Strategic Trends and Commercial Opportunities Through 2032
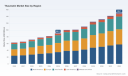
The global thaumatin market has entered a phase of accelerating maturation, transitioning from a niche specialty ingredient to a strategically important component in the broader natural sweeteners and flavor modulation landscape. Valued at approximately $63.0 million in 2020, the market has expanded to $90.5 million by 2025, and forward projections indicate a trajectory toward $149.7 million by 2032. This expansion reflects a compound annual growth rate of 7.5 percent across the forecast period, a pace that signals sustained commercial momentum rather than a temporary cyclical upturn. The growth is not merely a function of volume expansion; it represents a structural shift in how manufacturers approach sugar reduction, flavor balancing, and clean-label formulation. Thaumatin's dual functionality as both a high-intensity sweetener and a taste-modifying agent positions it at the intersection of several converging demand forces, yet the market's evolution is shaped by constraints that require careful strategic navigation.
The current landscape is defined by a moderately concentrated competitive structure, with the top three players accounting for roughly 45 percent of combined revenue and the top five controlling just above half of the market. This concentration level suggests that while scale advantages exist, there remains meaningful room for specialized suppliers, regional distributors, and formulation-focused entrants to capture differentiated positions. The market's growth trajectory is not uniform across all segments; food-grade applications dominate the revenue mix, pharmaceutical-grade thaumatin commands a substantial secondary share, and a residual category supports niche industrial and specialty uses. Similarly, sweetening applications represent the largest end-use category, flavoring and taste-masking functions account for a significant portion, and a smaller share is distributed across auxiliary applications. These structural balances matter because they reveal where value creation is concentrated and where future margin opportunities are likely to emerge.
Market Dynamics and Structural Challenges
Despite the favorable growth outlook, the thaumatin market faces several interdependent challenges that will shape competitive outcomes over the next several years. The first and most fundamental constraint lies in raw material availability. Thaumatin is extracted from the katemfe fruit, which originates from a limited geographic base in West Africa. Total raw material exports from Ghana and Nigeria were approximately 210 metric tons in 2023, a volume that constrains the scale at which thaumatin can be produced and creates inherent supply elasticity limitations. This raw material bottleneck is not merely a logistical issue; it defines the ceiling for rapid volume expansion and makes supply chain resilience, farmer relationships, and extraction efficiency critical competitive variables. Companies that can secure stable katemfe access, optimize yield per ton of raw fruit, or develop blending strategies that reduce thaumatin intensity requirements will hold structural advantages in a supply-constrained environment.
A second challenge involves the tension between regulatory certainty and shifting nutritional labeling frameworks. Thaumatin benefits from a well-established regulatory foundation: it remains authorized as a sweetener and flavor enhancer in the European Union under Regulation (EC) No 1333/2008, and it is classified as generally recognized as safe by the FDA for use as a sweetener and flavor modifier in the United States. This regulatory clarity is a competitive asset that distinguishes thaumatin from newer or less-tested sweetener alternatives. However, regulatory approval alone does not guarantee commercial adoption. The European Commission's 2023 Nutri-Score algorithm, for instance, penalizes added sugars more heavily, which has accelerated reformulation efforts in beverages and cereal categories where thaumatin's role as a flavor enhancer and taste-balancing agent becomes commercially relevant. The challenge for manufacturers is that regulatory status and consumer perception do not always align; even authorized ingredients must navigate consumer skepticism around ultra-processed foods, label simplification expectations, and the broader clean-label movement that favors recognizable ingredient names.
A third structural challenge relates to cost and labor dynamics in the raw material supply chain. Small-scale farmers in West Africa handle cultivation and harvesting of the Thaumatococcus daniellii plant, and this labor-intensive model supports rural livelihoods but also introduces variability in yield quality, harvest timing, and supply consistency. Labor cost structures, weather variability, and the fragmented nature of smallholder cultivation can create fluctuations that ripple through extraction facilities and ultimately affect pricing stability for downstream customers. In a market where thaumatin already occupies a premium positioning relative to some bulk sweeteners, supply-side volatility can complicate long-term formulation commitments and contract negotiations. Addressing these constraints requires investment in farmer support programs, quality standardization initiatives, and potentially blended ingredient systems that reduce dependency on pure thaumatin volumes without sacrificing functional performance.
PW Consulting
Key Drivers Shaping the Market Trajectory
The market's expansion is being propelled by a combination of technological, regulatory, demand-side, and supply chain factors that reinforce one another. On the innovation front, formulation science has advanced significantly in using thaumatin not simply as a standalone sweetener but as part of blended systems designed to mitigate off-notes, enhance mouthfeel, and reduce the total sweetener load required to achieve target sensory profiles. Recent product launches illustrate this shift. In early 2025, Ingredion introduced a Reb M plus thaumatin blend developed for sugar-free yogurts, reporting a 38 percent reduction in aftertaste during European consumer trials. Around the same time, Natex UK Ltd launched the ThaumActive ready-to-use natural sweetener range tailored for flavored waters and protein beverages. These developments are meaningful because they demonstrate thaumatin's evolving commercial role: it is increasingly valued for its ability to improve the sensory quality of reduced-sugar and high-protein formats, rather than solely for its sweetness intensity.
Regulatory and policy dynamics provide another layer of momentum. The continued authorization of thaumatin across major markets gives formulators a predictable compliance pathway, which is especially valuable in categories such as beverages, dairy alternatives, and functional foods where ingredient scrutiny is high. At the same time, public health-oriented labeling and sugar taxation pressures are pushing manufacturers to reduce added sugar without sacrificing taste acceptance. Thaumatin's taste-modifying properties make it particularly useful in these reformulation scenarios, where it can soften bitterness from high-intensity sweeteners, improve the perceived sweetness profile at lower dosages, and support cleaner ingredient declarations when used in moderation. This regulatory and reformulation environment creates a durable demand pull, but it also favors suppliers who can offer technical support, application-specific guidance, and proven blend compatibility rather than bulk commodity pricing alone.
Consumer and enterprise behavior is shifting in ways that reinforce thaumatin's relevance. The broader sugar reduction trend is no longer confined to confectionery or soft drinks; it now extends to dairy, baked goods, RTD beverages, and sports nutrition formats. At the same time, the clean-label and natural ingredients movement favors plant-derived sweeteners with established regulatory histories over synthetic alternatives. Thaumatin's botanical origin and multi-functional profile align well with these preferences, particularly in premium and health-oriented product tiers where ingredient narrative matters. For large food and beverage manufacturers, thaumatin is increasingly evaluated not just on cost per unit of sweetness but on total formulation value, including taste modulation, label positioning, and compatibility with other natural ingredients.
Supply chain and cost structure changes are also reshaping competitive dynamics. Because katemfe supply is geographically concentrated and relatively limited, companies with integrated or closely coordinated sourcing arrangements are better positioned to manage price stability and supply continuity. At the same time, advancements in extraction efficiency, quality control, and downstream blending capabilities can improve the effective economics of thaumatin use. Suppliers that invest in application-focused formulation services, ready-to-use ingredient formats, and consistent batch quality can command stronger value capture even in a supply-limited environment. This dynamic is gradually rewarding capability-driven players over pure volume players, particularly as end-users seek to minimize formulation risk while navigating sugar reduction targets.
Competitive Landscape and Strategic Positioning
The competitive field features a mix of international ingredient companies, regional specialists, and distribution-focused suppliers. Tate & Lyle operates as a broad natural high-intensity sweetener producer, leveraging thaumatin within a wider portfolio that serves food and beverage applications. Its strategic advantage lies in scale, application breadth, and the ability to position thaumatin alongside complementary sweetening and texturizing ingredients. Naturex, now aligned with Givaudan, brings a natural ingredients and flavor expertise that supports thaumatin's use in taste-modulation contexts, especially where sensory balance and label-friendly positioning are priorities. Natex UK Ltd has carved out a specialist identity with a strong focus on natural thaumatin and formulated sweetening solutions, including its Sweetence brand, and its recent launch of ready-to-use formats for flavored waters and protein beverages reflects a deliberate move toward application-ready offerings that reduce customer formulation burden.
Van Wankum Ingredients and Silver Fern Chemical operate more on the supply and distribution side, connecting manufacturers with thaumatin supply for food and industrial applications, while Penta Manufacturing Company provides thaumatin as a natural sweetener and flavor enhancer with a U.S.-based commercial footprint. These companies illustrate a market where differentiation can come from multiple directions: portfolio breadth, technical formulation capability, regional supply reliability, or specialized customer segments. The presence of both established multinationals and focused specialists creates a competitive environment in which customer value is increasingly determined by service depth, application knowledge, and supply consistency rather than price alone.
The market structure is evolving along two parallel tracks. On one hand, there is consolidation pressure as larger ingredient groups seek to strengthen their natural sweetener portfolios and capture cross-selling opportunities across sweetening, flavor, and functional ingredients. On the other hand, there is room for fragmentation and specialization, particularly in application-tailored formats, regional market focus, and niche health-oriented categories. New entrants and smaller companies can compete by developing proprietary blends, securing reliable katemfe access through strong farmer relationships, or concentrating on underserved applications such as high-protein beverages, functional waters, or premium dairy alternatives. The strategic lesson is that thaumatin's market does not reward generic participation; it rewards companies that can link supply reliability with formulation utility and customer-specific technical support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, several trends are likely to define thaumatin's commercial trajectory. The first is the growth of blended, application-specific sweetening systems. As formulators continue to balance taste, cost, label clarity, and sugar reduction goals, thaumatin's value will increasingly be expressed in combination with other natural sweeteners and flavor modulators. Ready-to-use blends and pre-balanced formulations will become more important because they reduce development time and sensory risk for customers, especially smaller manufacturers and private-label producers who may lack extensive in-house formulation resources. This trend favors suppliers that can offer standardized, application-tested formats with documented sensory outcomes.
The second trend is the widening of thaumatin's application footprint beyond traditional sweetener uses. Its function as a flavor enhancer and taste-masking agent is becoming more commercially visible in categories such as high-protein beverages, sugar-reduced dairy, and functional drinks where off-note suppression is critical. If this trajectory continues, thaumatin's revenue mix could gradually shift toward more value-added application contexts, where pricing power is supported by technical differentiation rather than commodity positioning. The opportunity here is substantial for companies that invest in sensory research, category-specific formulation guidance, and collaboration with customers during product development.
Saccharin Market
The third trend involves supply chain maturation and potential geographic diversification. Given the current concentration of katemfe exports from Ghana and Nigeria, any initiative that improves cultivation practices, expands responsible sourcing, or enhances extraction yield could meaningfully affect market capacity and price stability. At the same time, efforts to standardize raw material quality and strengthen farmer partnerships may reduce supply variability and improve long-term planning for downstream users. However, uncertainty remains. Crop sensitivity, climate conditions, and the social and economic complexity of smallholder supply chains mean that supply expansion cannot be taken for granted. Companies should treat raw material resilience as a strategic priority rather than an operational detail.
These trends create clear commercial opportunities, but they also carry risk. If sugar reduction momentum slows in certain categories, or if alternative sweeteners gain stronger consumer acceptance at lower cost points, thaumatin's growth rate could face headwinds. If regulatory frameworks evolve in ways that alter labeling expectations or ingredient disclosure norms, manufacturers may need to adapt formulation strategies quickly. And if supply chain disruptions affect katemfe availability, price volatility could test customer relationships and margin structures. The businesses best positioned to navigate these uncertainties will be those that build flexible sourcing, maintain strong technical credibility, and differentiate through formulation value rather than price competition alone.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat thaumatin as a formulation enabler rather than a standalone sweetener. Integrating thaumatin into blended systems, investing in sensory validation early in the development cycle, and selecting suppliers with demonstrated application support can shorten time-to-market and improve taste outcomes in reduced-sugar formats. Companies should also evaluate ready-to-use and pre-blended options where they exist, especially for categories like flavored waters, protein beverages, and sugar-reduced dairy, where sensory balance is difficult to achieve with single-ingredient approaches.
For investors and strategic planners, thaumatin represents a market with steady structural growth and clear differentiation opportunities, but success depends on identifying players with credible supply relationships, formulation capabilities, and application-focused product architectures. Capital allocation and partnership decisions should weigh not only revenue trajectory but also raw material resilience, technical service depth, and the ability to capture value in higher-margin application segments. Companies that rely purely on commodity-style participation may face margin pressure, while those with specialty positioning and customer lock-in through formulation expertise are better placed to sustain value capture.
For procurement and supply chain leaders, securing predictable thaumatin supply requires a proactive approach. Long-term supplier relationships, quality consistency requirements, and contingency planning for raw material variability should be central to sourcing strategy. Where possible, procurement teams should collaborate with suppliers on traceable sourcing, batch standardization, and blended options that reduce exposure to pure thaumatin volume constraints. Building flexibility into specification and formulation parameters can also help mitigate the impact of supply fluctuations without compromising product quality or label commitments.
Understanding thaumatin's market trajectory at this level of detail is essential for companies making multi-year formulation, sourcing, and investment decisions. Broad growth figures provide useful context, but the real strategic value lies in segment-specific demand patterns, application-level performance data, regional sourcing dynamics, and competitor capability mapping. For decision-makers who need granular segmentation, scenario analysis, and customized recommendations tailored to specific product categories or markets, the complete PW Consulting research report offers a more detailed view of the data and strategic options that can inform next steps.
Thymol Market
For detailed analysis of this topic, please visit the official page: Thaumatin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Multiwall Paper Bags Market 2026: Why the 4.5% CAGR and $244.7M Outlook Changes Everything
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Multiwall Paper Bags Market
Navigating Transition: Market Overview and Key Challenges
The multiwall paper bags market has established itself as a critical component of industrial packaging, serving sectors ranging from construction to agriculture. Over the past five years, the market has demonstrated steady expansion, with revenue climbing from approximately 135.4 million U.S. dollars in 2020 to an estimated 179.5 million in 2025. This trajectory reflects a compound annual growth rate of 4.5 percent, positioning the sector for continued moderate expansion through 2032, when revenues are projected to approach 244.7 million U.S. dollars. While the growth profile is stable rather than explosive, the underlying dynamics are shifting in ways that create meaningful strategic implications for manufacturers, investors, and procurement leaders.
The market structure remains relatively fragmented at the top, with the top three players collectively holding about 22.4 percent of revenue and the top five accounting for 28.7 percent. This concentration level indicates a landscape where scale advantages exist but do not fully dictate outcomes, leaving room for regional specialists and product-focused innovators to compete effectively. The distribution of revenue across regions shows North America as the largest contributor, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but growing shares. Across product types, kraft paper continues to anchor the market, while coated and recycled variants occupy meaningful niches. On the application side, building materials represent the largest end-use segment, with agriculture, chemicals, food, and minerals following in varying degrees of demand intensity.
Despite the constructive growth baseline, the industry is confronting several transition points that will shape competitive outcomes over the next five years. First, volatile raw material costs are compressing margins and forcing manufacturers to rethink procurement strategies and pricing models. Second, regulatory frameworks are accelerating the shift away from plastic-heavy multilayer sacks toward fully recyclable paper-based solutions, raising compliance costs but also opening differentiation opportunities. Third, demand patterns are evolving as end-users prioritize sustainability credentials, moisture resistance, and supply chain reliability, pushing suppliers to balance performance with environmental claims. These challenges are not merely headwinds; they are re-shaping the criteria by which companies win or lose in the market.
Key Drivers Reshaping the Landscape
Regulatory and compliance pressures are among the most consequential forces currently influencing the market. The EU Packaging and Packaging Waste Regulation, which begins applying from August 2026, requires improved recyclability documentation and labeling compliance for packaging, including multiwall paper bags. By 2030, all packaging must be recyclable, a mandate that favors sack kraft paper over multilayer sacks with high plastic content in multiwall applications. In parallel, plastic bag bans in various regions are compelling manufacturers to pivot toward sustainable, recyclable, and biodegradable materials as compliant alternatives. These regulatory shifts are raising the bar for product design and documentation, but they also reward suppliers that can demonstrate credible recyclability and reduced plastic use.
Raw material dynamics are equally central to the market's evolution. Benchmark kraft linerboard prices surged by 22 percent year-on-year in 2023 due to constrained supply and high energy costs, and volatility has persisted into subsequent periods. Fluctuating prices for paper and adhesives continue to challenge manufacturers, as rising input costs directly impact production economics and profit margins. This environment favors companies with vertically integrated production, diversified sourcing, and the ability to pass through cost adjustments without eroding customer relationships. It also incentivizes material efficiency innovations that reduce weight or improve strength-per-unit, helping to offset cost pressure while meeting performance requirements.
Kraft Paper Bag Market
Demand-side behavior is shifting in ways that reward performance and sustainability simultaneously. End-users in building materials, agriculture, chemicals, and food sectors are increasingly scrutinizing packaging for moisture resistance, durability, and environmental impact. For humidity-sensitive products, the ability to maintain integrity without relying on plastic layers has become a competitive differentiator. At the same time, procurement teams are seeking suppliers that can provide consistent quality, flexible sizing, and transparent sustainability credentials. These expectations are pushing manufacturers to invest in product development that addresses both functional and regulatory demands, rather than treating sustainability as a separate initiative.
Technology and process innovation are beginning to play a more visible role in competitive positioning. While multiwall paper bags may appear to be a mature product category, advances in production optimization, material formulation, and design intelligence are enabling suppliers to improve strength, reduce weight, and enhance moisture barriers. Recent product-level activity illustrates this direction: in May 2025, Mondi Group launched its re/cycle PaperPlus Bag Advanced, a high-performance paper bag designed for humidity-sensitive products with up to 60 percent reduced plastic use and a strong moisture barrier. This launch underscores how sustainability and performance are converging, setting a benchmark that other players will need to match or differentiate around.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape features a mix of global packaging leaders and specialized manufacturers, each pursuing distinct positioning strategies. Mondi Group, headquartered in Vienna, focuses on AI-powered multiwall bag production, sustainable paper-based packaging, and moisture-resistant bag solutions for industrial applications including cement and chemicals. Its emphasis on humidity-sensitive performance and reduced plastic use aligns closely with regulatory and demand trends. Smurfit Kappa, based in Atlanta, specializes in AI-enhanced bag design, lightweight yet durable multiwall sacks, and eco-friendly industrial packaging, positioning itself around design intelligence and sustainability. Segezha Group, headquartered in Moscow, provides AI-assisted high-strength multiwall bags, biodegradable packaging solutions, and customizable industrial paper sacks for food and agricultural sectors, leveraging customization and biodegradability as differentiators.
WestRock Company, also headquartered in Atlanta, focuses on AI-driven material optimization, high-barrier multiwall bags, and recyclable paper bag technologies for building materials, chemicals, and agriculture sectors, emphasizing barrier performance and recyclability. Sonoco Products Company and International Paper contribute from the U.S. with broad industrial and consumer packaging portfolios, with International Paper supplying kraft paper bags and corrugated packaging for industrial and consumer applications. More regionally focused players add further diversity: Bag Supply Company manufactures millions of high-quality multiwall paper bags annually for agricultural, industrial, construction, and consumer goods; Southern Packaging LP supplies customizable multi-wall paper packaging solutions through vertically integrated production facilities for industrial bulk packaging; JohnPac produces cost-effective multiwall paper bags for seed and grain storage and transport with custom shapes and sizes; and Novolex offers its Dubl Life line of FSC-certified or 100 percent recycled kraft paper bags for industrial and consumer use.
PW Consulting
The strategic logic across these players reveals several differentiation paths. One is performance-led, targeting moisture resistance, strength, and barrier properties for demanding applications. Another is sustainability-led, emphasizing reduced plastic use, recyclability, biodegradability, and certified fiber sources. A third is cost and customization-led, serving specific end-use verticals with tailored sizes and economical production. Vertical integration and sourcing flexibility are recurring advantages in a volatile raw material environment, while investments in design and production intelligence are increasingly used to improve efficiency and product consistency.
Industry events and community engagement are also shaping the competitive rhythm. The PSSMA 2026 Production Managers' Seminar and Bag Boot Camp in Greenville, South Carolina, along with the PSSMA 2026 Annual Meeting in Napa, California, reflect ongoing지식交流 and capability-building within the sector. These gatherings provide forums for sharing operational best practices and aligning on emerging standards, which can accelerate adoption of improved processes and compliance practices across the supply base.
Looking at market structure evolution, the current fragmentation at the top suggests room for selective consolidation among regional players seeking scale, while also leaving space for differentiated specialists to thrive. New entrants are unlikely to disrupt the market through volume alone; instead, they will need to bring clear advantages in sustainability credentials, moisture performance, customization, or cost efficiency. The interplay between regulatory deadlines, raw material volatility, and end-user expectations will likely reward companies that can combine operational resilience with credible product innovation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The first major trend is the acceleration of recyclable and reduced-plastic multiwall paper bag designs as regulatory and customer expectations converge. With the EU requiring all packaging to be recyclable by 2030 and plastic bag bans expanding in various regions, suppliers that can deliver high-performance paper-based sacks with minimal or no plastic content will gain a structural advantage. This trend creates opportunities for product differentiation tied to documented recyclability, reduced plastic use, and moisture barrier performance that does not rely on multilayer plastic construction. The commercial implication is clear: sustainability is becoming a performance attribute, not just a compliance checkbox.
The second trend is continued raw material cost volatility paired with a growing emphasis on material efficiency and supply chain resilience. As kraft linerboard and adhesive prices remain sensitive to supply constraints and energy costs, manufacturers will increasingly value sourcing flexibility, vertical integration, and design choices that improve strength-to-weight ratios. Companies that can maintain quality while optimizing material usage will be better positioned to protect margins and offer competitive pricing. Procurement leaders should expect more variability in lead times and input costs, making supplier reliability and transparency increasingly valuable.
The third trend is the gradual integration of production and design intelligence into multiwall bag manufacturing. While not a wholesale transformation of the category, AI-assisted design and material optimization are enabling suppliers to improve consistency, reduce waste, and tailor bags to specific end-use requirements. This trend supports both cost efficiency and product performance, and it may become a baseline expectation for leading suppliers over the forecast period. The opportunity lies in pairing these capabilities with clear customer benefits, such as customized sizing, enhanced moisture resistance, or faster response to specification changes.
Tea Bag Paper Market
Potential risks and uncertainties should not be overlooked. Regulatory timelines may shift or be implemented with varying rigor across jurisdictions, creating compliance complexity for suppliers operating in multiple markets. Raw material price swings could intensify if energy costs or supply disruptions escalate, pressuring margins even for well-prepared manufacturers. End-user demand could also evolve in unexpected ways if alternative packaging materials gain traction in specific applications, or if economic conditions slow procurement in construction and agriculture. Navigating these uncertainties will require scenario planning, flexible sourcing, and product portfolios that can adapt to changing requirements without sacrificing core performance.
Implications and Actionable Considerations for Decision Makers
For manufacturers, the priority is to align product development with the converging demands of recyclability, moisture performance, and cost efficiency. Investing in reduced-plastic or fully recyclable multiwall designs, improving material utilization, and strengthening sourcing flexibility can help protect margins while meeting regulatory and customer expectations. Building documentation and labeling capabilities that support compliance in key markets, particularly where recyclability requirements are tightening, will also reduce execution risk. Where possible, enhancing production and design intelligence can improve consistency and responsiveness, giving suppliers an edge in customized or performance-sensitive segments.
For investors, the market offers moderate growth with meaningful differentiation potential rather than uniform upside. Attention should focus on players with credible sustainability credentials, resilient cost structures, and clear positioning in performance-sensitive applications such as building materials, chemicals, and humidity-sensitive food or agricultural products. Vertical integration, diversified sourcing, and evidence of product innovation that reduces plastic content or improves barrier performance are useful indicators of competitive strength. At the same time, raw material volatility and regulatory complexity warrant careful assessment of margin resilience and compliance readiness across geographies.
For procurement and supply chain leaders, the emphasis should be on supplier capability and transparency rather than price alone. Evaluating suppliers on moisture resistance, recyclability documentation, customization flexibility, and sourcing stability can reduce risk in demanding applications. Given ongoing input cost variability, diversifying the supplier base where feasible and securing commitments that balance cost with reliability can improve outcomes. Engaging suppliers early on specification changes and compliance requirements can also smooth transitions as regulatory deadlines approach and performance expectations rise.
Strategic decisions in this market benefit from detailed, up-to-date intelligence on segment-level demand patterns, regional dynamics, and competitor movements. PW Consulting's comprehensive research report on the Multiwall Paper Bags Market provides deeper segmentation data, regional breakdowns, and customized guidance to support planning and investment choices. Accessing that level of detail can help translate the trends and considerations outlined here into precise, actionable strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Multiwall Paper Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Manned Security Services Market: The 7.12% CAGR Signals a Strategic Shift
By pmarketresearch, 2026-09-21
The Manned Security Services Market: Strategic Trends and Commercial Opportunities in an Evolving Landscape
The manned security services market has reached a critical inflection point. In 2025, the sector crossed the $242.5 million threshold in annual revenue, building on a steady recovery from the $185.3 million baseline observed at the start of the decade. Over the past five years, the trajectory has reflected not just post-pandemic normalization, but a fundamental recalibration of how organizations think about physical protection. The market is projected to expand at a compound annual growth rate of 7.12 percent through 2032, reaching an estimated $393.1 million by the end of the forecast period. This growth is not merely an extension of historical patterns; it is being shaped by structural shifts in technology, regulation, labor dynamics, and buyer expectations. For executives, investors, and procurement leaders, understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers and examining the forces that will determine competitive advantage in the years ahead.
Market Snapshot and Core Challenges
A Sector in Transition
The market has grown consistently from 2020 through 2025, but the composition of that growth tells a more nuanced story. Commercial facilities continue to anchor demand, while industrial sites and residential complexes represent secondary but strategically important demand pools. The service mix remains dominated by traditional guarding, though cash and valuables protection and specialized security services contribute distinct, higher-margin segments that reflect evolving risk profiles. This diversification is a response to the reality that one-size-fits-all security models no longer satisfy the operational complexity of modern facilities, logistics networks, and public-facing institutions.
Challenge One: Labor Scarcity and Wage Pressure
The most persistent constraint on the industry is human capital. Manned security remains, by definition, labor-intensive. Organizations that rely on guard presence at perimeter points, access control stations, and roaming patrols are competing for a workforce that is simultaneously in high demand across adjacent sectors such as logistics, facilities management, and hospitality. Wage escalation is no longer a temporary fluctuation; it is a structural cost input that compresses margins for providers that compete primarily on price. In markets where basic guarding is commoditized, the pressure is especially acute, with thousands of active security companies vying for the same talent pool. The result is a two-tier dynamic: providers that can attract, retain, and professionalize their personnel through career pathways, training, and competitive compensation are gaining share, while those locked into low-cost models face turnover, service inconsistency, and reputational risk.
Worldwide Site Safety Service Market
Challenge Two: Regulatory Friction and Compliance Complexity
Regulation is reshaping how manned security operates across jurisdictions. In some regions, foreign ownership restrictions are mandating local control and altering the competitive playing field for international operators. In others, procurement frameworks are introducing new clauses that affect how private security functions are structured and contracted, particularly in cross-border or government-adjacent environments. These dynamics do not simply add administrative overhead; they influence market entry strategy, partnership models, and the cost of scaling. Companies that treat compliance as a one-time onboarding exercise are exposed, whereas those that embed regulatory intelligence into their operating design can convert constraints into barriers that protect incumbent positions.
Challenge Three: The Technology Expectation Gap
Buyers increasingly expect that manned security will be augmented by technology—remote monitoring, video analytics, access control integration, and data-driven reporting. Yet the integration of these capabilities with human presence remains uneven. Some incumbents have built seamless hybrid offerings; others are stitching together point solutions that create operational friction. The expectation gap is widening the wedge between providers that can deliver coordinated, intelligence-led protection and those that offer body-only presence without situational awareness. For decision-makers, this creates a procurement challenge: how to ensure that the human element and the technological layer reinforce each other rather than operate in parallel silos.
Key Drivers Shaping the Market
Technology as a Force Multiplier, Not a Replacement
The most consequential driver of market evolution is the maturation of technology that amplifies the effectiveness of security personnel rather than displacing them. Remote guarding stations, analytics-enabled video feeds, and integrated alarm response platforms allow a smaller on-site footprint to achieve coverage that previously required a larger physical guard complement. This is particularly relevant for organizations managing multiple sites, variable-risk environments, or extended operating hours. The strategic implication is not simply cost reduction; it is the ability to redeploy personnel to higher-value tasks such as incident response, customer engagement, and specialized patrols. Where technology is deployed thoughtfully, it raises the baseline quality of service and creates differentiation in a market that has historically competed on headcount and price.
Policy and Regulatory Signals Redirecting Investment
Recent policy developments are acting as catalysts for reallocation. The closure of a significant government business unit by one of the largest global providers illustrates how portfolio choices are being shaped by shifting contract landscapes and regulatory considerations. Simultaneously, procurement frameworks that govern private security functions abroad are introducing clarity—and complexity—into how services are structured for international operations. These signals matter because they influence not only who wins contracts, but how services are designed, staffed, and audited. Providers that proactively align their operating models with emerging compliance expectations are better positioned to secure long-term public and quasi-public contracts, while those that lag face re-bid risks and margin compression.
Demand-Side Shifts: Risk Profiles Are Becoming More Granular
On the demand side, organizations are moving away from generic security packages toward solutions that reflect the specific risk profile of their facilities, supply chains, and reputational exposures. Commercial facilities are prioritizing customer experience and loss prevention within a single security function. Industrial sites are emphasizing perimeter integrity, access control, and rapid incident escalation. Residential complexes are balancing resident safety with privacy and community integration. This granularity is driving demand for specialized services and for guard personnel who are trained not only in presence and deterrence, but in de-escalation, observation, and communication. The buyers who are winning contracts are those that articulate a clear security mission and tie it to measurable outcomes, rather than treating security as a generic cost center.
Cost Structure Evolution and the Pursuit of Predictability
Cost structures are shifting as labor, insurance, technology, and compliance costs converge. Providers are responding by standardizing service tiers, incorporating technology-assisted monitoring to moderate labor intensity, and building clearer pricing models that improve predictability for clients. This evolution benefits both sides: organizations gain budgeting clarity and service consistency, while providers gain operational discipline and reduced churn. The market is increasingly rewarding business models that balance human presence with scalable infrastructure, because that balance delivers the reliability that risk-conscious buyers require.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market features several large, globally active providers whose strategies reveal how scale, footprint, and integration are being leveraged. Allied Universal operates across North America with a broad service portfolio spanning manned guarding, mobile patrols, risk consulting, and technology-enabled solutions, anchored by strong government and commercial contracts. Its positioning reflects the value of a large, diversified contract base and the ability to offer integrated services that span physical presence and advisory support. Securitas, headquartered in Sweden, operates in dozens of markets with a focus on on-site guarding, mobile guarding, remote guarding, and integrated solutions, emphasizing manned personnel services supported by technology. Its strategy underscores the importance of geographic breadth and the hybrid model of human presence combined with remote capabilities. Prosegur, based in Spain, specializes in manned guarding combined with alarms, logistics, and integrated security solutions across a wide country footprint, illustrating how logistics-adjacent security can create cross-selling opportunities and operational synergies. GardaWorld, headquartered in Canada, delivers manned security, cash logistics, and risk management with a strong presence in government and high-risk environments, highlighting the premium that specialized, high-assurance services can command. Paladin Security and InterCon Security, both with North American foundations, emphasize government and commercial guarding contracts, demonstrating that regional depth and relationship-driven account management remain viable paths to growth even as global players expand.
Recent Developments as Strategic Signals
Recent contract activity and recognition highlight how incumbents are reinforcing their positions. A major provider secured a new contract for guard services at county mental health facilities and clinics, a type of engagement that blends public-sector procurement with the need for trained, sensitive, and consistent personnel. Another provider ratified a renewed contract with a university that expanded protections and included wage increases, reflecting both the prioritization of campus safety and the willingness to invest in personnel to sustain service quality. Separately, a North American security provider received multiple industry awards, signaling that excellence in execution, client service, and operational discipline continues to be recognized and rewarded. These examples are consistent with a broader pattern: winning engagements often requires a combination of reputation, reliable staffing, and the ability to adapt services to the specific environment.
Market Structure: Consolidation Pressures and Differentiated Niches
The market is characterized by a moderate concentration at the top, with the largest players holding meaningful but not dominant shares, and a long tail of regional and specialty providers. This structure creates two simultaneous dynamics. First, there is pressure for consolidation among mid-tier and regional firms seeking to achieve scale in staffing, technology deployment, and contract procurement, particularly as compliance and labor costs rise. Second, there is room for differentiation in niches such as high-risk environments, cash and valuables logistics, specialized facility protection, and integrated remote-plus-on-site models. New entrants that can combine technology fluency with disciplined personnel management are finding traction, but they face the same labor and compliance realities as incumbents. The net effect is a market that is neither fully consolidated nor highly fragmented, but one in which strategic positioning—clear service boundaries, credible integration, and reliable execution—is becoming the primary determinant of sustainable share gains.
Future Trends and Commercial Opportunities
Trend One: Hybrid Security Models Will Become the Standard
Over the next three to five years, the distinction between manned and technology-assisted security will increasingly blur into hybrid models that are treated as the baseline offering. Remote monitoring, analytics, and integrated alarm response will be combined with on-site personnel deployed in a more targeted fashion. The commercial opportunity lies in designing service packages that explicitly map technology functions to human responsibilities, so that clients receive a coordinated outcome rather than a stack of separate capabilities. Providers that can demonstrate measurable improvements in response times, coverage efficiency, and reporting clarity will be better positioned to win multi-site and long-term contracts. The risk is that poorly integrated hybrids create confusion about accountability and degrade client trust; therefore, execution discipline and clear service definitions will be critical.
Trend Two: Professionalization of the Security Workforce Will Differentiate Providers
Professionalization—through structured training, clear career pathways, measurable performance standards, and competitive compensation—will move from a nice-to-have to a core competitive requirement. Organizations will increasingly evaluate providers not only on availability and price, but on the quality, consistency, and retention of the personnel assigned to their sites. The opportunity is to build workforce models that reduce turnover, improve service reliability, and create reputational advantage. In commoditized segments, however, wage and staffing pressure will remain a headwind, and providers that lack a clear workforce value proposition will find it harder to defend margins or win complex contracts. The uncertainty lies in the pace of wage escalation across different regions and the extent to which technology can offset labor intensity without compromising service quality.
Trend Three: Regulatory Clarity Will Reshape Market Access and Portfolio Choices
As regulatory frameworks around ownership, procurement, and cross-border private security functions become more defined, market access will be recalibrated. Providers with strong local knowledge, compliant ownership structures, and established relationships will have advantages in certain regions, while others may need to partner, restructure, or refocus their portfolios. The commercial opportunity is to use regulatory intelligence to shape where to compete, how to structure contracts, and which assets to retain or divest. Recent portfolio adjustments by large providers are a reminder that strategic withdrawal from specific segments can free resources for higher-conviction areas. The risk is that regulatory change introduces sudden compliance costs or contract re-bidding, particularly for operators with exposure to government-adjacent or internationally regulated engagements.
Strategic Recommendations for Decision-Makers
For Providers and Operators
Design service models around outcomes, not headcount. Clients increasingly buy protection that is visible, measurable, and integrated, rather than simply the presence of personnel. Providers that can articulate how manned presence, remote support, and reporting work together will command stronger positioning. Invest in workforce stability as a strategic asset: structured training, predictable scheduling, and competitive compensation are not merely cost items; they are the foundation of service quality and client retention. Where commoditization is intense, differentiate through specialization, reliability, or integration rather than price alone, because price competition in a high-turnover environment erodes both margins and reputation.
Managed Security Services System Market
For Investors and Sponsors
Evaluate potential investments with a clear view of labor economics and regulatory exposure. Business models that rely heavily on low-cost staffing without a credible plan for retention and professionalization are exposed to margin volatility and service risk. Preference should be given to operators with demonstrated ability to integrate technology into manned operations in a way that improves coverage and reporting, as well as those with diversified contract bases that reduce dependence on any single public-sector or cyclical customer. Pay close attention to geography and ownership rules, because compliance architecture can either enable scale or constrain it. In markets where concentration is moderate and fragmentation persists, there may be opportunities to build value through disciplined consolidation, shared services, and technology standardization, provided that integration risk is managed carefully.
For Procurement and Risk Leaders
Buy security as a coordinated capability, not as a commodity line item. Define the security mission for each site or portfolio in terms of outcomes—deterrence, response, access control, customer experience, and reporting—then evaluate providers against how they assign responsibilities across personnel and technology. Require evidence of workforce stability, training standards, and escalation protocols, because these factors determine whether service quality holds under stress. Favor contracts that include clear performance metrics, regular reporting, and defined accountability for both on-site and remote components. When regulated environments or cross-border operations are involved, confirm ownership, compliance, and contracting structures early, because late-stage surprises can disrupt delivery and increase cost.
The manned security services market is expanding, but growth alone does not guarantee profitability or competitive advantage. The sector is being reshaped by labor dynamics, regulatory evolution, technology integration, and a more demanding demand base. Organizations that treat these forces as signals to redesign service models, workforce strategies, and portfolio choices will be better positioned to capture value. For those seeking deeper granularity—segment-level sizing, regional dynamics, competitive benchmarking, and tailored scenario analysis—a comprehensive research resource is available to support more precise planning and decision-making.
PW Consulting
For detailed analysis of this topic, please visit the official page: Manned Security Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Shower Chairs Market: Why 5.6% CAGR and Home Care Demand Are Redefining Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Medical Shower Chairs Market
The medical shower chairs market is entering a phase of sustained expansion, driven by demographic shifts and evolving care delivery models. Market revenue climbed from approximately $605.2 million in 2020 to $800.0 million in 2025, reflecting steady year-over-year momentum. Forecasts indicate this trajectory will continue through 2032, with the market projected to surpass $1.1 billion. This growth translates to a compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. The sector’s expansion is not a simple continuation of historical patterns; it reflects structural changes in how mobility support equipment is designed, procured, and reimbursed. Understanding these underlying forces is essential for manufacturers, investors, and procurement leaders seeking to position themselves ahead of market shifts rather than react to them.
Shower Trolley Market
Market growth is being shaped by several concurrent pressures. Aging populations across developed economies are increasing the prevalence of conditions that impair safe bathing, including neurodegenerative diseases and post-surgical mobility limitations. At the same time, healthcare systems are shifting more rehabilitation and long-term care functions into community and home settings. This transition raises demand for equipment that is both clinically appropriate and adaptable to non-institutional environments. A second pressure comes from regulatory scrutiny. Device recalls and adverse event reporting have reinforced expectations around quality system compliance, material durability, and locking mechanism reliability. Manufacturers that treat these as routine compliance exercises risk reputational and operational exposure, while those that embed safety verification into product development cycles are strengthening market trust. A third challenge lies in reimbursement uncertainty. Coverage decisions increasingly hinge on documented medical necessity, functional assessments, and evidence that standard bathing alternatives cannot be used safely. This changes how suppliers must position products and how care providers justify procurement.
Lift Chair Market
Technology Innovation and Clinical Design Shifts
Product development is moving beyond basic seating platforms toward integrated mobility and positioning solutions. Manufacturers are incorporating narrow compact frames, slim wheels, and three hundred and sixty-degree access configurations that reduce caregiver strain and improve maneuverability in tight bathroom layouts. Tilt and recline mechanisms are becoming more refined, with manual and powered options tailored to varying levels of patient independence and caregiver assistance. Color variants and material finishes are also gaining attention, particularly for institutional procurement teams that balance clinical utility with environmental aesthetics and user dignity. These design choices are no longer cosmetic; they are functional differentiators that affect adoption in hospitals, rehabilitation centers, and private homes.
Powered models and modular configurations represent a meaningful breakpoint in the market. Equipment that supports complex positioning criteria for patients with significant physical disabilities is expanding the addressable population beyond users who only need static seating support. This shift aligns with broader trends in person-centered bathing solutions, where the objective is to preserve patient comfort while standardizing safe transfer and hygiene routines. For commercial players, the implication is clear: product portfolios that offer configurable height, tilt, and access features can capture demand across multiple care settings without requiring separate product lines for each segment.
Policy and Reimbursement Dynamics
Reimbursement frameworks are a decisive factor in purchase behavior. Bath and shower chairs are covered under Medicare and Medicaid plans when medically necessary, subject to standardized evaluation criteria that assess whether a patient cannot safely use regular bathtubs or showers. Documentation expectations now commonly include a face-to-face physician examination within a defined period and specialty evaluations from occupational or physical therapists. These requirements shape procurement timelines and influence which products proceed through approval workflows.
Recent policy activity underscores how coverage language can influence category access. In April 2026, a Medicare Advantage organization obtained a favorable ruling in an appeal for coverage of a rolling shower chair that met complex positioning criteria for significant physical disability. This outcome illustrates that coverage is not static; it can expand when clinical justification demonstrates functional need that conventional equipment cannot address. At the same time, supplier cost structures remain uneven. Medicare durable medical equipment supplier costs for rolling shower chairs can exceed four thousand dollars, with reimbursement limited to covered plans under complex positioning requirements. This gap between cost and reimbursement creates pressure on pricing strategies and emphasizes the importance of clear clinical documentation and appropriate coding practices.
Regulatory oversight continues to influence product reliability expectations. Adverse event reports and Class II device recalls involving certain shower chair models have drawn attention to quality system compliance, locking integrity, and load-bearing stability. These developments do not halt market growth, but they sharpen procurement risk assessment. Purchasers increasingly evaluate manufacturers on their ability to demonstrate consistent production controls, traceability, and post-market surveillance. Companies that can provide transparent quality records and rapid issue resolution gain a tangible advantage in institutional tenders and home-care distribution channels.
Demand-Side Behavior and Care Setting Transition
User demand is being reshaped by where care is delivered and who participates in equipment selection. Home care remains the dominant application area, reflecting patient preference, cost containment pressures, and the expansion of outpatient rehabilitation services. Families and home-health providers now prioritize equipment that is easy to install, clean, and store, while still meeting weight capacity and safety requirements. This is especially relevant as more households adapt bathrooms for aging-in-place use rather than relying exclusively on facility-based solutions.
Hospitals and rehabilitation centers continue to be important adopters, but their purchasing logic is evolving. Caregiver safety has become a more explicit procurement criterion, with facilities favoring powered options and designs that reduce manual handling risk during transfers. Long-term care facilities, while smaller in relative volume, provide stable recurring demand and tend to value standardization across units, ease of maintenance, and compatibility with existing hygiene workflows. The commercial implication is that product positioning should not assume a single buying profile. In home care, usability and storage often dominate; in institutional settings, caregiver ergonomics, durability, and documentation compatibility can outweigh other factors.
Supply Chain, Cost Structure, and Procurement Realities
Cost structure pressures are coming from multiple directions. Raw material volatility, component specialization, and the need for repeated safety testing contribute to higher baseline production costs for advanced models. At the same time, reimbursement ceilings and coverage limitations constrain the pricing flexibility of suppliers that depend heavily on public payment pathways. This dynamic is pushing manufacturers to differentiate through configuration rather than price competition alone. Modular designs, accessory ecosystems, and serviceable components can reduce total cost of ownership for facilities that must balance acquisition cost with maintenance and replacement cycles.
Procurement teams are also becoming more disciplined in their evaluation criteria. Safety-tested designs, adjustable height and tilt functions, and clearly documented weight capacities are increasingly treated as baseline expectations rather than premium features. Suppliers that fail to provide clear technical specifications or that rely on vague performance claims face longer approval cycles and greater scrutiny. For distributors, this environment favors inventory 전략의 that align with documented demand patterns in home care and institutional segments, reducing exposure to overstocked SKUs that do not match reimbursement realities or facility specifications.
Competitive Landscape and Leading Strategies
The market remains relatively fragmented, with the top three participants holding roughly twenty-five percent of share and the top five approaching thirty percent. This concentration indicates that no single manufacturer dominates the category, leaving room for differentiated positioning and targeted segment strategies. The market is large enough to support multiple product philosophies, but it is also demanding enough that generic offerings face increasing difficulty in securing both institutional contracts and sustained home-care distribution.
Several leading companies illustrate distinct strategic approaches. ActiveAid emphasizes modular, self-propelled shower and commode chairs with narrow compact frames, slim wheels, three hundred and sixty-degree access, and tilt or recline options. Its recent expansion into broader color variants reflects an effort to support hospital, institutional, and home use with a consistent platform. This approach signals a focus on adaptability and visual integration across environments, which can matter in facilities that value uniformity as well as in home settings where equipment appearance influences user acceptance.
Arjo positions itself around person-centered bathing solutions, offering shower systems, chairs, and trolleys with powered options and caregiver safety features. Its emphasis on diverse mobility levels and powered assistance aligns with the institutional trend toward reducing caregiver strain and standardizing safe bathing routines. By embedding safety and ergonomics into the product narrative, Arjo targets procurement teams that prioritize workforce protection and clinical workflow consistency.
PW Consulting Health Care Research Center
DHG focuses on shower chairs and transfer benches with adjustable features, defined weight capacities, and safety-tested designs for patient comfort in hospital and home settings. This positioning is practical and specification-driven, appealing to buyers who need clear performance parameters and repeatable configurations. DHG’s approach highlights the commercial value of transparent technical documentation and product consistency across settings.
Etac provides shower commodes such as Alto, Swift Mobil, and Swift Mobil Tilt-2, with powered or manual options, three hundred and sixty-degree access, ergonomic design, and adjustable height or tilt. Its portfolio supports both user and caregiver needs, which is particularly relevant where patient mobility varies widely within the same facility or household. Etac’s broader international heritage, combined with U.S. market presence, also illustrates how established design reputations can support credibility in a category where safety and usability are closely scrutinized.
Invacare offers the I-Fit shower chair and Ocean series with tilt or recline, powered models, and accessories for bariatric and standard users. Its breadth across weight classes and feature levels reflects a strategy of covering multiple patient profiles with interconnected product lines. This can simplify catalog management and cross-selling, but it also requires rigorous quality oversight given that shower chair models in this category have appeared in adverse event reporting and recall activity. The lesson for competitors is consistent: product variety must be matched by disciplined production and post-market controls.
The overall competitive pattern suggests a market that rewards specialization without sacrificing platform flexibility. Leaders are differentiating through powered access, modular framing, caregiver-centric safety features, and clearer documentation of use cases and capacities. At the same time, market evolution is likely to see continued consolidation pressure among smaller suppliers who cannot sustain compliance costs or distribution reach, while new entrants may focus on underserved niches such as compact home-use configurations, bariatric-specific designs, or equipment that integrates more smoothly with existing bathroom layouts.
Future Trends and Commercial Implications
Over the next three to five years, one major trend will be the continued expansion of powered and complex positioning solutions. As reimbursement pathways for advanced models become clearer through case-by-case appeals and updated clinical criteria, demand for tilt, recline, and powered mobility options should increase, particularly in rehabilitation and complex-disability settings. This opens commercial opportunities for manufacturers that can prove functional benefit and support documentation workflows, but it also raises the bar for engineering reliability and service support.
A second trend is the deepening alignment between product design and home-care adoption. As more bathing support equipment is procured for private residences, buyers will favor designs that combine safety with straightforward installation, cleaning, and storage. Manufacturers that offer compact frames, secure locking mechanisms, and materials suited to frequent sanitation will be better positioned in this channel. There is also room for bundled accessories and configuration guidance that help families and home-health providers match equipment to specific bathroom constraints.
A third trend is the growing influence of risk and compliance visibility in purchasing decisions. Given ongoing recalls and adverse event reporting, procurement teams are likely to place greater weight on quality system transparency, post-market monitoring, and documented testing. Suppliers that can communicate their compliance processes clearly and respond quickly to issues will gain trust. This creates an opportunity for companies to build reputation capital around reliability, not just product features. The associated risk is that regulatory attention may continue to affect specific models and production batches, requiring manufacturers to maintain agile quality controls and proactive communication.
Actionable Guidance for Decision Makers
Manufacturers should prioritize platform flexibility over narrow feature competition. Equipping product lines with modular tilt or recline options, clear weight classifications, and caregiver-friendly access designs can expand addressable demand across home care, hospitals, and long-term care facilities without fragmenting production. Equally important is investing in documentation that supports medical necessity pathways and procurement evaluation, since reimbursement clarity and specification transparency increasingly determine purchase speed.
Investors should evaluate exposure to advanced positioning and powered models, as well as the strength of each company’s quality and compliance infrastructure. Growth in the category is likely, but returns will be shaped by which participants can manage cost structure pressures, maintain reimbursement-relevant documentation, and respond effectively to safety scrutiny. Portfolio concentration in home-care-friendly configurations and bariatric-capable designs may provide resilience across economic and reimbursement cycles.
Procurement leaders should standardize evaluation criteria around safety-tested design, adjustable height and tilt, defined weight capacity, locking reliability, and documentation compatibility. Rather than selecting products on appearance or price alone, purchasing teams can reduce downstream risk by aligning acquisitions with caregiver workflow needs and patient positioning requirements. For facilities managing mixed user profiles, configurable platforms can reduce inventory complexity while preserving appropriate clinical support.
The commercial landscape in this market is evolving quickly enough that strategic decisions benefit from current segment definitions, regional demand patterns, and reimbursement detail. A deeper view of these dynamics can help organizations translate broad trends into product, pricing, and procurement choices that are better aligned with near-term reality. Readers seeking a more granular breakdown of market segments, share shifts, and actionable entry points can refer to the complete PW Consulting market research report for detailed segmentation data and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Medical Shower Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beneath the Surface: Strategic Trends and Commercial Opportunities in the Marine Trenchers Market
The marine trenchers market has entered a phase of steady structural expansion, underpinned by growing offshore infrastructure investment and evolving technical requirements for subsea installation. Valued at approximately 120.0 million USD in 2020, the market reached an estimated 148.5 million USD by 2025, reflecting a compound annual growth rate of 4.0 percent over the 2020–2025 period. Forward projections extend through 2032, with revenue anticipated to approach 195.5 million USD by the end of the forecast horizon. While the growth trajectory appears measured in percentage terms, the underlying shift in project complexity, operational depth, and equipment specialization tells a more dynamic story. Marine trenching has moved from a supporting activity in pipeline and cable deployment to a critical capability that directly influences project economics, environmental compliance, and operational risk.
Several inflection points define the current market environment. First, the push toward deeper water projects and more complex seabed conditions is placing new demands on trenching systems, particularly around tool interchangeability, remote operation, and sediment adaptability. Second, rising project costs linked to maintenance, specialized labor, and equipment wear are forcing operators to prioritize reliability and lifecycle performance rather than upfront price comparisons. Third, the growing emphasis on offshore wind, interconnectors, and gas infrastructure is expanding the number of burial and trenching campaigns, but also compressing scheduling windows and increasing the premium on proven, repeatable execution. These dynamics are not merely operational concerns; they are reshaping procurement strategies, fleet planning, and competitive positioning across the supply chain.
Key Drivers Shaping the Market Trajectory
Technological Innovation and the Shift Toward High-Performance, Multi-Mode Systems
One of the most visible drivers in the marine trenchers market is the continued advancement of equipment capability. The industry is moving beyond single-purpose designs toward systems that can switch between mechanical cutting, jetting, and hybrid modes depending on sediment type and burial depth. This flexibility is increasingly valued because seabed conditions are rarely uniform, and project specifications often require precise depth control, minimal surface disturbance, and adaptable tool configurations. Higher horsepower platforms, improved hydraulic and electro-hydraulic architectures, and more robust cutting chains and bits are enabling operators to maintain productivity in harder sediments where wear rates and ground speed have historically limited performance.
Recent equipment milestones illustrate this direction. In October 2025, Osbit Ltd secured a contract with NKT to design and build the T3600 subsea trencher, described as one of the most powerful systems in the segment with 3,600 horsepower and dual jetting and cutting tools. The concept reflects a broader preference for machines that can handle heavier workloads while reducing the need for multiple vessel-based interventions. By February 2026, the T3600 had arrived at the Port of Blyth for final fit-out and commissioning ahead of operational use in 2027. This kind of development signals an industry leaning toward higher-capacity platforms that can address longer burial campaigns, more demanding ground conditions, and tighter project schedules.
For decision-makers, the implication is clear: equipment selection is becoming less about whether a trencher can complete a burial task and more about how effectively it can do so across variable conditions, with lower downtime and fewer operational compromises. Manufacturers that can demonstrate measurable improvements in tool life, ground speed stability, and mode switching are better positioned to capture perceived value, even when capital or rental costs are higher.
Policy, Regulation, and the Spreading Footprint of Offshore Infrastructure
Regulatory and policy environments are exerting a quiet but persistent influence on trenching demand. Environmental standards, seabed protection requirements, and cable and pipeline burial specifications are increasingly factored into project design, which in turn raises the baseline expectation for trenching quality and consistency. In many regions, burial is no longer treated as a discretionary step; it is a core requirement for protection against fishing activity, anchor damage, and environmental disturbance.
Broader energy and infrastructure trends reinforce this direction. European offshore wind capacity reached approximately 25 GW by 2020, and the continued expansion of wind farms and interconnector networks has sustained demand for cable burial equipment and related trenching standards. At the same time, Europe imported 85 billion cubic meters of LNG in 2020, helping accelerate demand for subsea pipeline burial and associated marine trenching in the region. These figures are not just energy statistics; they represent the kind of large-scale infrastructure activity that creates recurring requirements for burial, rehabilitation, and intervention services.
The policy-driven opportunity is twofold. Projects are increasingly spread across multiple geographies and seabed environments, which broadens the addressable market for trenching equipment and services. At the same time, regulatory expectations can raise the bar for execution, favoring operators with documented quality control, traceability, and compliance capabilities. Procurement teams are likely to weigh not only schedule and cost, but also the ability to meet region-specific burial standards and environmental safeguards.
Demand-Side Changes: More Burial Work, More Complexity, More Coordination
Demand for marine trenchers is being shaped by a shift in how offshore projects are planned and executed. Cable and pipeline installations are no longer isolated activities; they are integrated into wider grid, gas, and industrial networks that require coordinated scheduling across multiple contractors and vessels. As a result, trenching work is often planned around limited weather windows, restricted seabed access, and tight connection milestones. This places a premium on equipment availability, predictable performance, and rapid mobilization.
Pipeline burial remains the largest application area in terms of revenue contribution, reflecting the continued importance of protected subsea transport infrastructure. Cable burial is also significant, driven by interconnectors, wind farm export and array cables, and telecommunications links. Umbilical burial represents a smaller but technically demanding segment, often involving more delicate handling requirements and specialized burial approaches. The practical takeaway is that demand is diversified across infrastructure types, but the common thread is a need for burial solutions that can be deployed reliably across different project phases and seabed conditions.
For buyers and operators, this means that trenching capability is being evaluated within a broader project ecosystem. Equipment that can be integrated easily with different vessel configurations, ROV support, and survey and monitoring workflows is more attractive than a standalone machine optimized for a narrow set of conditions. The market is rewarding flexibility and service integration as much as raw trenching power.
Cost Structure and Operational Pressures: Wear, Labor, and Maintenance
Cost dynamics remain a significant driver of purchasing and operating behavior. Subsea trenching operations face elevated costs when sediment conditions accelerate chain and bit wear, especially in harder ground where achievable ground speeds and component life must be carefully managed. Performance monitoring against established geotechnical reference frameworks has become a practical necessity rather than an academic exercise, because underestimated wear or overly optimistic speed assumptions can materially affect project budgets and schedules.
Labor and maintenance costs add another layer of pressure. Specialized subsea trenching maintenance and operator training contribute meaningfully to overall project expenses, particularly for offshore infrastructure campaigns that require sustained operational readiness. High skill requirements, limited pools of experienced personnel, and the cost of keeping complex systems in field-ready condition all feed into total cost of ownership. This is an important shift from a purely equipment-purchase mindset to a broader operating-cost perspective.
Worldwide Underwater Dredging Robot Market
Recent project activity highlights how these cost and performance considerations play out in practice. In April 2025, Van Oord added a new Jet-It subsea trencher to its cable burial fleet following successful North Sea testing, reinforcing the value of proven shallow-water cable burial capability. In January 2025, DeepOcean completed a subsea trenching project in the US Gulf of Mexico using a 2,800hp trencher for cable and pipeline burial, demonstrating the continued relevance of powerful mechanical and jetting systems in active offshore regions. These deployments show that performance validation in real seabed conditions is a decisive factor in fleet expansion and project award decisions.
PW Consulting
Competitive Landscape and Leading Strategies
The marine trenchers market is characterized by a concentrated but diverse set of participants. Market concentration is notable, with the top three companies accounting for roughly 62.0 percent of revenue and the top five firms holding about 78.0 percent. This level of concentration suggests that scale, technological reputation, and established project relationships matter significantly, while still leaving room for specialized players and regional specialists to compete on differentiated capabilities.
Several companies illustrate the range of strategic positions in the market. Soil Machine Dynamics Ltd, based in Wallsend, Tyne & Wear, United Kingdom, manufactures subsea trenchers, burial machines, and related intervention equipment for pipeline and cable laying, including the Q-Trencher and Shallow Water Trencher models. Royal IHC, headquartered in Kinderdijk, Netherlands, designs and manufactures the Hi-Traq® multi-tool subsea trenchers, jetters, and tracked trenching vehicles for shallow water cable burial and offshore wind projects. Seatools B.V., based in the Netherlands, specializes in custom subsea trenching vehicles, mechanical and jet trenchers, cable ploughs, and upgrades for pipeline and cable installations. Osbit Ltd, also in the United Kingdom, designs, builds, and upgrades subsea trenching systems including mechanical, jetting, and cutter trenchers for cable and pipeline burial. Mastenbroek Limited, another UK-based manufacturer, provides subsea trenchers with conventional or undercut/rotary heads, available in hydrostatic or electro-hydraulic configurations for various sediment types.
The competitive field also includes operators and integrated service providers that use or deploy trenching equipment as part of broader campaign execution. Allseas Group, based in the Netherlands, operates Digging Donald, a fully remote-controlled pipeline burial trencher capable of depths up to 450 meters with interchangeable tools. DeepOcean Group, headquartered in the United Kingdom, operates a fleet and provides marine trenching equipment including mechanical trenchers, jetting ROVs, and ploughs for pipeline, cable, and umbilical burial. Van Oord, also in the Netherlands, operates and manufactures its own fleet of trenchers including Deep Dig-It, Dig-It, and Jet-It for subsea cable burial up to more than 5 meters below the seabed.
Differentiation Through Capability, Flexibility, and Execution track Record
What distinguishes the stronger positions is not simply equipment ownership, but the ability to match trenching technology to project needs and to prove performance in the field. Some manufacturers compete on power and tool versatility, emphasizing high horsepower and dual-mode systems that can adapt to harder or mixed sediments. Others compete on specialization, focusing on shallow water cable burial, tracked vehicles, or custom trenching vehicles that can be tailored to specific seabed and water-depth constraints. A third group differentiates through remote operation, depth capability, and tool interchangeability, which matters when projects require precise burial at greater depths or when surface vessel exposure must be minimized.
Recent developments show how these strategies are being reinforced. The T3600 contract award to Osbit and its subsequent arrival for fit-out point to a push toward higher-power, multi-tool systems that can serve demanding pipeline and cable projects. Van Oord's addition of a new Jet-It trencher after North Sea testing reflects a practical emphasis on validated cable burial performance in a region with active wind and interconnector work. DeepOcean's Gulf of Mexico project completion demonstrates the value of proven fleet deployment in geographically diverse markets.
Market Evolution: Consolidation, Specialization, and Selective New Entry
The market is likely to continue evolving around three themes. First, consolidation may remain attractive for firms seeking to broaden geographic reach, capture more of the project lifecycle, or combine equipment manufacturing with service delivery. Second, specialization will persist because seabed conditions, water depths, and project types are too varied for a single equipment architecture to dominate all segments. Shallow water cable burial, deep pipeline burial, umbilical handling, and mixed-sediment trenching each reward different design priorities. Third, new entry and expansion will depend on credible technical differentiation and demonstrated execution, rather than brand presence alone. In a market where top suppliers already hold a substantial share, credibility is built through project record, performance data, and the ability to integrate with operator and client workflows.
For strategic planners, the competitive takeaway is that procurement is increasingly comparative and evidence-based. Vendors that can articulate measurable differences in wear performance, operating efficiency, and deployment flexibility are better placed to defend pricing and win repeat work. For investors and industry participants, the more interesting question is not whether the market will grow, but which capabilities will be rewarded as project conditions become more varied and cost scrutiny intensifies.
Future Trends to Watch Over the Next 3 to 5 Years
Trend 1: Higher-Capacity, Multi-Mode Trenching as a Baseline Expectation
Over the next few years, the threshold for competitive trenching capability is likely to rise. Projects in harder sediments, deeper water, and more constrained schedules will push operators toward higher horsepower platforms with interchangeable tools and multiple burial modes. The recent emphasis on powerful dual-function systems is not an isolated product trend; it reflects a broader expectation that trenching equipment should reduce the need for rework, handle variable ground conditions, and keep campaigns on schedule.
The commercial opportunity here lies in equipment and service packages that lower total operating risk rather than simply increase peak power. Manufacturers and fleet providers that pair high-capacity machines with proven tool management, maintenance planning, and operational support may find stronger demand than those competing on hardware specifications alone. The risk is that power upgrades can raise capital and maintenance costs, so any advantage must be translated into measurable gains in productivity, component life, or schedule reliability.
Trend 2: Greater Integration of Remote Operation, Monitoring, and Fleet Standardization
Remote-controlled and remotely supervised trenching is likely to become more prominent as projects seek to improve precision, reduce vessel exposure, and standardize execution across multiple sites. The growth of fully remote pipeline burial systems and ROV-supported jetting and mechanical trenchers indicates a market moving toward operational models that depend less on manual intervention and more on controlled, repeatable processes. At the same time, operators managing multiple vessels and campaigns will increasingly value fleet standardization, common maintenance regimes, and shared training pathways.
Marine Deck Machinery Market
This trend creates opportunities for companies that can offer not just equipment, but consistent operating interfaces, training support, and lifecycle management. For buyers, standardized fleets and remote operation can simplify crew deployment and reduce variability between projects. The uncertainty is operational maturity: remote and semi-remote systems require dependable communications, maintenance readiness, and skilled oversight, so the benefits will depend on how well they are integrated into real-world campaign planning.
Trend 3: Regional Demand Diversification with Uneven Pace
Demand for marine trenching is expected to remain geographically diverse, supported by offshore wind, interconnectors, pipeline and cable networks, and energy infrastructure expansion in multiple regions. However, the pace of growth is unlikely to be uniform. Some markets will see sustained activity driven by large-scale wind and grid investments, while others may experience more intermittent demand tied to specific pipeline or LNG-related projects. This uneven pattern means that fleet planning and regional positioning will matter more than broad but shallow market exposure.
The associated opportunity is to align equipment portfolios and service coverage with the regions and project types most likely to generate recurring work. Companies that understand local seabed conditions, regulatory expectations, and project scheduling realities will be better positioned to capture demand without overextending into less predictable segments. The main risk is overgeneralizing from one region's pipeline or wind activity to the entire market; seabed conditions, permitting environments, and vessel logistics vary enough to make regional nuance a strategic necessity.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment developers, the priority should be to translate technical differentiation into commercial clarity. Higher power, multi-mode tools, and remote operation features are attractive, but their value increases when they are linked to measurable outcomes such as reduced rework, longer component life in challenging sediments, and faster mobilization. Investment in demonstration projects, peer-reviewed performance data, and lifecycle support can be as important as the hardware itself. Companies should also consider how their offerings fit into broader project ecosystems, including compatibility with different vessel types, ROV support, and survey workflows.
For investors and strategic partners, the most defensible opportunities are likely to be found where market concentration, technical lead times, and execution track record intersect. A concentrated market can create durable positions for firms with proven capability, but it also means that competitive advantage must be continually renewed through product evolution and reliable project delivery. Capital allocation decisions should account for the reality that trenching demand is tied to large infrastructure cycles, which can be strong but unevenly timed. Preference for operators and manufacturers with diversified project exposure, disciplined cost structures, and credible maintenance and training capabilities may offer a more balanced risk profile than pure capacity expansion.
For procurement teams and project developers, equipment selection should be evaluated against total project risk rather than headline performance alone. Burial depth requirements, sediment variability, maintenance readiness, training burden, and regional support availability all influence long-term outcomes. Where possible, validation through recent deployments in comparable conditions can provide more useful guidance than specification comparisons in isolation. Buyers may also benefit from considering fleet compatibility and service integration, especially when multiple projects or regions are involved, because standardization can reduce training costs and improve scheduling predictability.
Across all perspectives, the most valuable intelligence is the kind that connects equipment capability to real operational conditions and project economics. Market size and growth rates provide context, but the decisions that matter most are usually about which trenching approach fits a given seabed profile, which fleet configuration best supports regional demand, and which performance trade-offs are acceptable when wear, labor, and maintenance costs are factored in. Detailed segmentation data, company-level positioning, and region-specific demand analysis can make those choices sharper and less reliant on assumption.
Closing Perspective
The marine trenchers market is expanding at a steady pace, but its strategic significance is growing faster than the headline numbers suggest. Burial and trenching are increasingly integral to the safe, compliant, and cost-effective deployment of offshore pipelines, cables, and umbilicals. That shift rewards systems that combine power, flexibility, remote operability, and proven field performance, while also rewarding operators and manufacturers that can manage the practical realities of wear, specialized labor, and project scheduling. The next several years will likely favor participants who treat trenching capability as part of an integrated infrastructure solution rather than as a standalone tool purchase. For executives, investors, and procurement leaders, the most useful next step is to align equipment and service choices with the specific seabed conditions, regional demand patterns, and cost structures that will shape each project's outcome.
For detailed analysis of this topic, please visit the official page: Marine Trenchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ballast Water Treatment Equipment Market: Why 8.7% CAGR Changes Everything
By pmarketresearch, 2026-09-21
The Ballast Water Treatment Equipment Market: Navigating the Next Wave of Maritime Compliance and Capital Opportunities
The global fleet is undergoing a quiet but profound transformation. As environmental regulations tighten and port state inspections become more rigorous, ballast water treatment has shifted from a compliance checkbox to a strategic operational priority. The market has expanded at a steady pace, with revenues crossing the seven-billion-dollar threshold in 2025 and projected to surpass ten billion before 2030, maintaining a compound annual growth rate of 8.72 percent through 2032. This trajectory reflects more than incremental fleet upgrades; it signals a structural realignment in how shipowners, regulators, and technology providers approach ballast water management as a long-term operational and sustainability imperative.
Growth is broad-based, spanning mature and emerging maritime regions, with Asia Pacific representing the largest share of activity, followed by Europe and North America. While the regional distribution reflects differing fleet compositions and regulatory timelines, the underlying momentum is universal: older vessels are being retrofitted, newbuilds are specifying treatment systems at the design stage, and operators are seeking equipment that balances performance with minimal downtime. Against this backdrop, the market is no longer defined solely by regulatory compliance deadlines. It is increasingly shaped by technology maturity, cost-of-ownership dynamics, and the growing emphasis on electronic record-keeping and verifiable treatment performance under intensifying inspection regimes.
Market Landscape and Core Challenges
The current phase of the ballast water treatment equipment market is characterized by a maturing technology base, heightened enforcement activity, and a competitive environment that favors players capable of demonstrating reliable performance across diverse water conditions and vessel types. Revenue growth has been consistent, supported by a pipeline of retrofit projects and newbuild specifications. Yet beneath the headline figures lie structural tensions that will determine which companies and investors capture durable value.
1. Treatment Performance Under Real-World Variability
Ballast water systems must handle wide fluctuations in salinity, temperature, turbidity, and biological load. This variability continues to challenge system reliability, particularly for technologies sensitive to water quality or requiring precise chemical dosing. Operators are increasingly scrutinizing performance data, service histories, and the ease of maintenance when selecting equipment. The implication is clear: systems that can demonstrate consistent efficacy with simpler maintenance profiles, and that integrate cleanly into existing vessel operations, are gaining preference over solutions that demand frequent calibration or extensive crew intervention.
2. Regulatory Tightening and Inspection Pressure
The regulatory environment is moving from baseline compliance toward verifiable, auditable performance. Recent amendments to the Ballast Water Management Convention have updated record-keeping requirements, including revised Ballast Water Record Book forms and the introduction of electronic records, reinforcing the expectation that operators maintain detailed, accessible documentation. Concurrently, port state control concentrated inspection campaigns have targeted ballast water management during specific windows, employing structured questionnaires and on-site verification to assess system compliance. These developments elevate the importance of systems that not only meet technical standards but also facilitate transparent reporting and straightforward audits.
3. Capital Allocation and Retrofit Economics
Shipowners face competing capital priorities, particularly in an environment where dry-dock schedules, compliance upgrades, and operational efficiency investments all compete for limited budgets. Retrofitting ballast water treatment equipment requires careful planning around vessel downtime, installation complexity, and integration with existing piping and control systems. For fleet operators, the decision often hinges on total cost of ownership rather than upfront price alone, including energy consumption, consumables, service availability, and the potential for future regulatory changes. This dynamic is reshaping procurement behavior toward solutions that offer predictable operating costs and adaptable configurations.
Key Drivers Redefining Market Dynamics
Several interconnected forces are accelerating growth and reshaping competitive priorities in the ballast water treatment equipment market. Understanding these drivers is essential for identifying where demand is heading and which capabilities will differentiate successful participants.
Technology Innovation and Treatment Modality Evolution
The technology landscape reflects a shift toward hybrid and multi-barrier approaches that combine filtration with disinfection methods such as ultraviolet treatment, electrolysis, and chlorine-based disinfection. Filtration-plus-UV configurations are widely recognized for their chemical-free operation and suitability across many vessel types, while electrolysis-based systems offer compact footprints and strong disinfection performance. Chlorination-focused solutions provide effective treatment in certain operating conditions but require careful handling and monitoring. The practical trend is toward systems that can adapt to varying ballast water quality, minimize consumables dependency, and integrate smoothly with vessel automation and data systems. This is not merely a technical preference; it reflects operational priorities around crew workload, maintenance intervals, and regulatory verifiability.
Policy and Regulatory Momentum
Policy remains the foundational demand driver, but its influence is deepening beyond initial compliance. The ongoing review of the ballast water management framework, informed by accumulated data and operational experience, points to potential amendments that could further refine performance requirements and measurement approaches. For manufacturers and shipowners alike, this means designing for future-proofing. Systems that are modular, upgradable, and capable of producing auditable electronic records will be better positioned as the regulatory framework evolves. The emphasis on documentation and verification also raises the strategic importance of service and support, since compliance is increasingly judged by both equipment performance and the quality of operational records.
Demand-Side Shifts in Fleet Strategy
Shipowners and operators are recalibrating fleet strategy in response to energy efficiency goals, operational resilience, and reputational considerations. Ballast water treatment is now part of a broader conversation about vessel sustainability and operational risk management. Newbuild orders increasingly include treatment specifications as standard, while retrofit activity is being prioritized for vessels with longer remaining service lives. This demand-side shift favors solutions that can be installed with minimal disruption, integrated with existing bridge and automation systems, and supported by local service networks. In addition, operators are increasingly factoring in the ease of proving compliance during inspections, which makes system transparency and documentation support a material purchasing consideration.
Supply Chain and Cost Structure Pressures
Cost structures in the equipment and services space are being re-evaluated as operators seek to manage total expenditure over the lifecycle of the vessel. While initial pricing remains relevant, buyers are paying greater attention to energy use, filter replacement cycles, chemical handling where applicable, and the availability of service and spare parts across key operating regions. This has encouraged a broader view of value, with some operators favoring solutions that reduce recurring consumable costs or that offer service agreements aligned with planned maintenance schedules. At the same time, supply chain resilience matters, particularly for components that must be available across multiple regions and vessel types. Providers that can combine reliable hardware with predictable service delivery are increasingly differentiated.
Competitive Positioning and Strategic Differentiation
The competitive landscape is moderately concentrated, with a handful of leading firms accounting for a significant share of activity. This concentration reflects the credibility requirements of the market: shipowners prefer suppliers with established certification status, proven installation experience, and the ability to support vessels across regions. At the same time, the diversity of treatment technologies and vessel requirements leaves room for specialized offerings and regional strengths.
Technology Archetypes and Differentiators
Leading participants are building distinct identities around treatment architecture, service capability, and integration depth. Alfa Laval, for example, has focused on filtration-plus-UV systems with an emphasis on compact design and compatibility with a range of vessel types, positioning its PureBallast product line around operational simplicity and performance consistency. Techcross has emphasized electrochemical approaches through direct and indirect electrolysis systems, catering to operators seeking robust disinfection performance and a footprint suited to certain vessel configurations. Hyde Marine’s Guardian series combines filtration and UV treatment with a focus on reliability and installation flexibility. Optimarin offers filtration-plus-UV systems with a strong service orientation, while De Nora Marine and Evoqua Water Technologies are associated with filtration-plus-electrolysis architectures that appeal to operators prioritizing disinfection performance and compact layouts. Wärtsilä presents both UV and electrochemical options, leveraging broad marine system integration capabilities. Norwegian Greentech, Trojan Marinex, and Ecochlor round out a field that includes filtration-plus-UV and filtration-plus-chlorine disinfection approaches, each with distinct operating trade-offs.
The strategic implication is that no single technology archetype dominates across all segments. Instead, differentiation is emerging around the fit between treatment method and vessel profile, the quality of documentation and inspection readiness, and the reliability of regional service support. Companies that can articulate clear performance cases, provide robust training and maintenance pathways, and align their offerings with electronic record-keeping expectations are likely to strengthen their position as scrutiny intensifies.
Concentration, Consolidation, and Market Evolution
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. Larger players with integrated marine system portfolios can leverage cross-selling, service networks, and engineering partnerships to deepen their footprint. At the same time, specialized manufacturers and regional service providers can compete by offering niche performance advantages, faster installation, or customized support for specific vessel types. Recent certification updates from classification bodies have reaffirmed approvals for a broad set of manufacturers, underscoring that the market remains open to multiple qualified participants. This environment favors companies that can demonstrate not only technical compliance but also the operational credibility to withstand inspection campaigns and evolving record-keeping expectations.
A further evolution likely to shape the competitive landscape is the increasing importance of digital readiness. Systems that produce clean, auditable data trails and interface with vessel reporting processes are better positioned for the inspection environment and the broader movement toward electronic records. This is not only a compliance consideration; it is becoming a differentiator in how operators assess risk, manage audits, and maintain documentation across fleets.
Strategic Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the direction of the ballast water treatment equipment market and its commercial opportunities.
1. Compliance Becomes Continuous, Not Episodic
As inspection activity intensifies and electronic record-keeping becomes standard, the market will increasingly value systems that support ongoing verification rather than one-time certification. This trend favors solutions with clear documentation outputs, straightforward maintenance, and service models that help operators sustain compliance over time. For equipment providers, the opportunity lies in embedding compliance support into the product experience and service package, reducing the administrative burden on shipowners while strengthening reliability during audits.
Commercial implication: Providers that combine robust hardware with documentation-ready workflows, crew training, and localized service can create stickier relationships and reduce attrition in competitive retrofit and newbuild decisions.
2. Technology Convergence Around Practical Performance
While multiple treatment modalities will persist, the market is likely to see greater emphasis on practical performance across variable water conditions, ease of maintenance, and compatibility with vessel systems. Hybrid approaches that pair pre-treatment filtration with a disinfection method selected for the operating profile will remain central. Over the next few years, differentiation will increasingly hinge on real-world reliability, energy efficiency, and the ability to adapt configurations to specific vessel types and routes. This could encourage more modular designs and more flexible service agreements.
Commercial implication: Manufacturers that invest in field performance data, simplify maintenance, and align configurations to vessel operating patterns can strengthen their value proposition beyond compliance certification alone.
3. Regulatory Refinement Will Reshape Requirements and Planning Horizons
The ongoing review of the ballast water management framework, informed by operational data, suggests that requirements could evolve. Potential amendments may influence measurement approaches, reporting expectations, or performance verification methods. For shipowners and builders, this means adopting a forward-looking procurement stance, favoring systems that can be updated or reconfigured without major rework. For suppliers, it means designing products and service offerings with regulatory adaptability in mind.
Commercial implication: Early alignment with likely regulatory directions can reduce future retrofit risk and position companies to capture demand from operators seeking durable, adaptable solutions rather than short-term compliance fixes.
Worldwide Black Water Treatment System for Boats Market
Risks and Uncertainties to Monitor
No strategic outlook is complete without acknowledging uncertainty. The pace and content of future regulatory amendments remain dependent on international consensus and technical review processes. Inspection campaigns can vary in intensity and focus across regions, affecting short-term demand patterns. Economic conditions, vessel utilization, and capital availability will influence the timing of retrofit investments, particularly for older tonnage. In addition, technological trade-offs among treatment methods mean that performance claims must be carefully matched to specific operating conditions, and that supplier claims should be validated against real-world service data where possible.
PW Consulting
These uncertainties do not diminish the long-term trajectory; they reinforce the value of informed, scenario-aware decision-making. The operators and investors who succeed will be those who treat ballast water management not as a single compliance event but as a continuing operational capability.
Actionable Recommendations for Decision-Makers
For manufacturers, investors, and procurement teams, the current market environment calls for a balanced focus on compliance credibility, operational practicality, and lifecycle economics.
Water Treatment Equipment Market
For Equipment Manufacturers and Technology Providers
Position offerings around verifiable performance and inspection readiness, not certification alone. Invest in field performance documentation, crew training materials, and service models that reduce downtime and support electronic record-keeping. Consider modular architectures that allow configuration adjustments as requirements evolve. Strengthen regional service presence where retrofit and newbuild activity is concentrated, since responsiveness and parts availability increasingly influence purchasing decisions.
For Investors Evaluating Exposure
Assess exposure through the lens of total cost of ownership rather than unit pricing, with attention to service attach rates, consumable economics, and the breadth of certification and approval status across key regions. Differentiate between players with broad marine system integration capabilities and those with focused technology strengths. Monitor regulatory developments that could shift demand timing or favor particular treatment approaches, and weigh the resilience of service networks against the risk of regional inspection variability.
For Shipowners and Procurement Teams
Prioritize solutions that match the vessel’s operating profile, expected water quality variability, and inspection exposure, while keeping total cost of ownership at the center of evaluation. Favor systems that simplify maintenance, integrate with existing control and reporting workflows, and provide clear documentation support. Plan retrofit campaigns with dry-dock scheduling and service availability in mind, and seek configurations that can adapt to potential regulatory updates without major rework.
In all cases, the strategic value of detailed, up-to-date market intelligence is substantial. Segment-level demand patterns, regional inspection nuances, and technology-specific performance considerations can materially affect procurement timing and product selection. Access to granular data and tailored scenarios helps decision-makers move from broad trends to specific, defensible choices. PW Consulting’s in-depth research on the ballast water treatment equipment market provides that layer of detail, offering segmented analysis and customized viewpoints to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Ballast Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com