

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
5.5% CAGR and $5.4B Forecast: The Real Drivers Behind Foam Protective Packaging Market Growth

The Foam Protective Packaging Market: Strategic Trends and Commercial Opportunities Amid a Shifting Landscape
Foam protective packaging remains a foundational element in modern supply chains, providing cushioning, shock absorption, and thermal protection for products ranging from consumer electronics to medical devices. The market continues to expand at a steady pace, with revenue projected togrow from approximately USD 3,750 million in 2025 to around USD 5,442 million by 2032, reflecting a compound annual growth rate of roughly 5.5 percent over the 2026–2032 forecast period. This trajectory follows a decade of incremental but consistent expansion, with the sector moving from about USD 3,000 million in 2020 toward the mid-3,000 to low-4,000 million range by the mid-2020s. While the overall market does not experience explosive growth, its resilience stems from structural demand across diverse end-use sectors and the ongoing need to protect goods in increasingly complex logistics networks. For executives and investors, the critical question is not whether the market will grow, but how competitive dynamics, regulatory pressure, and technology shifts will reshape value creation within it.
Market Snapshot and Core Challenges
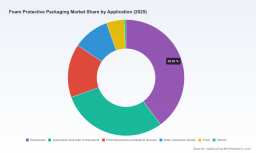
The current market environment is characterized by moderate growth, fragmented supplier landscapes, and intense pressure on traditional materials. Foam packaging benefits from broad application across electronics, automotive components, pharmaceuticals, consumer goods, and food, which helps distribute risk across multiple demand streams. However, this diversity also means that shifts in any one vertical can quickly alter regional or product-level dynamics. The market concentration among leading players remains moderate, with the top three firms accounting for just under half of total revenue and the top five capturing slightly more than half. This structure suggests that while scale advantages exist, there is still meaningful room for specialized suppliers and regional players to compete on customization, service, and niche material performance.
One of the most pressing challenges is the regulatory tightening around expanded polystyrene (EPS) and other foam materials. Multiple U.S. states have enacted or expanded EPS restrictions for food service and packaging applications, with New York’s expanded polystyrene ban taking effect in early 2026 and California imposing recycling-rate requirements on EPS food service ware producers. These measures create uncertainty for suppliers that rely heavily on conventional EPS, especially where recycled content alternatives are still maturing. At the same time, the industry is navigating raw material volatility and the cost implications of transitioning toward recycled, bio-based, or compostable formulations without compromising protective performance.
A second challenge lies in balancing customization with operational efficiency. Many end users require foam inserts, cushioning systems, and engineered packaging solutions tailored to specific product geometries and handling conditions. Yet highly customized production can strain margins and complicate scale operations. Suppliers must therefore decide how much to invest in flexible fabrication capabilities versus standardized, on-demand systems that can serve a broad customer base with minimal changeover. The tension between bespoke solutions and repeatable, efficient processes is reshaping product portfolios and capital allocation decisions across the sector.
Worldwide Mobile Phone Protective Cases Market
A third challenge is the growing expectation for sustainability credentials that do not sacrifice protection. Customers increasingly ask for packaging that reduces waste, supports recycling, or uses renewable content, but they still demand reliable shock protection and temperature assurance. Meeting both sets of requirements simultaneously forces manufacturers to refine material formulations, validate performance under real-world logistics conditions, and communicate environmental attributes transparently. In this environment, claims that are not backed by robust testing or verifiable supply-chain data can expose companies to reputational and compliance risk.
Key Drivers Shaping Market Dynamics
Technology innovation is a central force redefining what foam protective packaging can deliver. On-demand foam-in-place systems and semi-automated solutions are expanding the range of operations that can produce protective packaging close to the point of use, reducing storage needs and enabling faster response to order variability. Recent product updates, such as the launch of a semi-automated foam packaging system aimed at small-scale production with minimal maintenance, illustrate how equipment providers are lowering the threshold for adoption among smaller and mid-sized users. At the same time, advances in custom foam inserts and engineered cushioning continue to support high-value, sensitive applications where precision fit and shock performance are critical. These innovations are not merely incremental; they are changing the economics of how protection is produced, stored, and deployed across the supply chain.
Policy and regulatory developments are reshaping material choices and regional competitiveness. The expansion of EPS restrictions in multiple U.S. states is pushing manufacturers and brand owners to evaluate alternatives earlier in the product-design cycle, rather than treating regulatory compliance as a late-stage adjustment. In this context, recycled content strategies are gaining attention, with some formulations incorporating EPS recycled content at levels that vary by application and performance requirement. The availability of higher recycled-content options remains under development, but the direction of travel is clear: regulatory and customer pressure is accelerating the shift toward materials and designs that can demonstrate reduced environmental footprint while maintaining protective function. For suppliers, the ability to offer compliant, validated alternatives is becoming a competitive differentiator, especially in regions where mandates are already in force.
Demand-side behavior is also evolving as companies re-examine damage reduction, logistics efficiency, and sustainability goals together. Packaging damage is no longer viewed solely as a product-loss issue; it is increasingly treated as an operational and environmental problem that affects returns, replacements, and waste. Case examples in the market show how cushioning systems are being evaluated not just for protection but also for their contribution to broader operational and sustainability outcomes. This mindset is particularly relevant for high-volume distributors and e-commerce operators, where damage rates, labor time, and packaging waste all influence total cost. As a result, buyers are more likely to consider integrated cushioning solutions that combine reliable protection with compact storage, easier handling, and material attributes aligned with corporate sustainability targets.
Supply-chain and cost-structure changes are adding another layer of complexity. Energy inputs, resin pricing, and transportation costs all influence the competitiveness of foam-based solutions relative to alternative protective materials. Suppliers that can localize production, optimize material usage, and reduce changeover times are better positioned to manage cost variability. In parallel, consolidation among specialized manufacturers is altering the supply base, with acquisitions expanding capabilities from individual foam inserts to broader engineered packaging systems. These shifts are changing the bargaining dynamics between suppliers and large buyers, while also creating opportunities for partners that can offer end-to-end support across design, fabrication, and fulfillment.
Competitive Landscape and Leading Strategies
The competitive field in foam protective packaging spans large diversified providers, specialized foam manufacturers, and emerging players focused on sustainable or regenerative materials. Among the more prominent participants are companies with strong positions in foam-in-place systems, custom inserts, and engineered packaging solutions. Sealed Air Corporation has built recognition around on-demand cushioning systems, including expanding foam bags and equipment for blocking, bracing, and temperature assurance. Pregis LLC has emphasized foam-in-place cushioning platforms and custom foam inserts designed for shock protection and sustainability. Veritiv Corporation offers foam-in-place solutions for custom cushioning applications, while Foam Industries focuses on custom foam inserts, boxes, and complete engineered packaging systems. Specialty suppliers such as Foam Packaging Specialties and Protective Packaging Inc. concentrate on custom-fabricated foam packaging for delicate goods, semiconductor protection, and industrial or medical applications. Protective Packaging Solutions extends similar capabilities into industrial and medical shipping cases. Meanwhile, Cruz Foam has positioned itself around regenerative, compostable protective foam packaging for temperature-sensitive and fragile goods, and Storopack Hans Reichenecker GmbH offers protective foam solutions that include bio-based and high-performance options.
The strategic positioning of these leaders reflects different answers to the same underlying question: how to create value when protection, cost, and sustainability must be optimized together. Larger, more diversified players tend to compete on integrated systems, brand trust, and the ability to serve broad customer bases with standardized yet customizable solutions. Their recent activity underscores a push toward easier-to-deploy equipment and documented performance outcomes. For example, one major provider launched a semi-automated foam packaging system designed for smaller-scale production with low maintenance requirements, broadening the addressable market beyond large industrial users. Another leading player published a case study showing how a foam-in-place cushioning system helped convert packaging damage challenges into operational and sustainability gains for a major toilet distributor. These moves signal a focus on practical adoption, measurable outcomes, and the integration of protection with broader operational goals.
Specialized manufacturers, by contrast, often compete on depth of customization, material expertise, and the ability to serve technically demanding applications. The acquisition of one specialty supplier by another to expand from custom foam inserts to complete packaging systems illustrates how niche players are adding breadth to strengthen their value proposition. In high-sensitivity segments such as semiconductors, medical devices, and complex industrial components, the ability to engineer fit, cushioning density, and material behavior can matter more than scale alone. This creates a market structure in which both scale-oriented and specialty-oriented strategies can succeed, provided they are aligned with clear customer segments and validated performance claims.
Market evolution is likely to feature continued consolidation among smaller fabricators, alongside new entry from companies offering sustainable or regenerative foam alternatives. The regulatory environment and customer sustainability expectations are lowering barriers for innovators who can demonstrate credible environmental benefits without sacrificing protection. At the same time, established players are responding by expanding their own sustainable portfolios, including bio-based and high-performance options. The net effect is a competitive landscape that is becoming more pluralistic: scale players compete on system efficiency and reach, specialists compete on tailored performance, and sustainability-focused entrants compete on material differentiation. Companies that can bridge two or more of these positions—such as combining custom engineering with compliant, lower-impact materials—are likely to gain the strongest competitive traction.
Future Trends and Commercial Opportunities
Over the next three to five years, one clear trend is the accelerating integration of protection, sustainability, and operational efficiency into a single packaging decision. Buyers will increasingly favor solutions that reduce damage while also supporting waste reduction, recycling, or renewable content goals. This creates opportunities for suppliers that can provide validated, application-specific performance data alongside credible environmental attributes. Packaging decisions will be evaluated more holistically, with total cost of ownership—including damage, returns, labor, and disposal—becoming a central metric rather than unit price alone.
A second trend is the broadening adoption of on-demand and semi-automated foam systems across a wider range of operation sizes. As equipment becomes easier to deploy and maintain, smaller and mid-sized users can produce protective packaging closer to the point of use, reducing inventory and improving responsiveness. This opens new commercial avenues for equipment and material providers that can serve distributed production models, especially in regions where logistics complexity and order variability make centralized packaging less attractive. The opportunity here is not just in selling foam, but in enabling a more flexible protection model that aligns with changing fulfillment patterns.
A third trend is the continued material transition driven by regulation and customer preference, with recycled content, bio-based options, and compostable formulations gaining ground where performance allows. The direction of regulatory travel in multiple U.S. states suggests that compliance will increasingly be a baseline requirement rather than a differentiator. Suppliers that invest early in validated alternative materials and transparent documentation will be better positioned to retain customers through transitions. At the same time, uncertainty remains around the pace of recycled-content scaling, the performance trade-offs in certain applications, and the consistency of enforcement across jurisdictions. These uncertainties create both risk and opportunity: companies that can navigate material variation, demonstrate robust testing, and offer clear guidance will have an advantage in markets where buyers are under pressure to shift quickly.
PW Consulting
Strategic Actions for Decision Makers
For manufacturers and suppliers, the priority is to align product portfolios with the dual demands of protection and sustainability while improving operational flexibility. This means investing in material and equipment options that can serve both standard and custom applications, building validated performance data for alternative formulations, and reducing changeover complexity where possible. Companies should also evaluate where they can add value through integration—combining cushioning design, fabrication, and deployment support—rather than competing solely on material price. In a market where regulatory pressure and customer expectations are moving in the same direction, the ability to offer compliant, high-performing, and operationally efficient solutions will be a decisive advantage.
For investors, the most compelling opportunities lie in businesses that can demonstrate durable differentiation through either technical specialization, sustainable material leadership, or system-level efficiency. Given the moderate concentration of the market and the ongoing consolidation among specialty players, due diligence should focus on the durability of customer relationships, the credibility of sustainability claims, and the supplier’s ability to adapt to material and regulatory change. Investors should also watch for companies that are expanding from component supply into broader engineered packaging systems, as this shift can deepen customer lock-in and improve margin resilience. The key is to identify operators that are positioned not just for market growth, but for the more specific value shifts occurring within that growth.
For procurement and supply-chain leaders, the strategic imperative is to treat foam protective packaging as a total-cost and risk management decision rather than a commodity purchase. This involves comparing solutions on damage reduction, handling efficiency, storage footprint, and material compliance, while ensuring that sustainability claims are supported by verifiable data. Building partnerships with suppliers that can provide application-specific engineering, validated performance, and flexible production options can reduce exposure to damage-related losses and regulatory disruption. As mandates around EPS and other materials continue to expand, early engagement with alternative solutions will make it easier to manage transition risk without compromising protection standards.
The foam protective packaging market is entering a phase in which incremental growth is being reshaped by technology, regulation, and changing buyer expectations. Navigating this environment requires a clear understanding of where value is shifting—from straightforward material supply toward integrated, compliant, and operationally efficient protection solutions. For decision makers seeking detailed segmentation data, regional nuances, and tailored recommendations, a comprehensive market report provides the deeper intelligence needed to translate these strategic trends into concrete action.
Screen Protective Film Market
For detailed analysis of this topic, please visit the official page: Foam Protective Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com