

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
CMMS Software Market 2026: Beyond the 10.12% CAGR Story to $421M

The CMMS Software Market: Strategic Shifts and Commercial Opportunities in Asset Management
The computerized maintenance management system software market has entered a phase of accelerated evolution, driven by converging pressures around operational efficiency, technological maturity, and workforce constraints. From a base of approximately 215 million USD in 2025, the market is positioned to expand steadily through the end of the decade, reflecting a compound annual growth rate near 10.12 percent across the forecast horizon through 2032. This trajectory is not merely a function of incremental adoption; it signals a structural shift in how organizations approach asset lifecycle management, maintenance scheduling, and operational reliability. The transition from fragmented, paper-heavy workflows to integrated, data-driven maintenance platforms has reached a tipping point where scale, interoperability, and intelligent automation are becoming the baseline expectations rather than premium differentiators.
Behind the headline growth figures lie several inflection points that reshape how procurement teams, operations leaders, and investors should interpret the landscape. The market is no longer dominated by a single deployment paradigm or a narrow set of industrial verticals. Instead, organizations are navigating a complex trade-off between speed of implementation, long-term data sovereignty, and the ability to embed predictive capabilities into day-to-day maintenance routines. At the same time, labor cost dynamics continue to exert pressure on operational budgets, with maintenance technician labor representing a meaningful share of total operational expenses in manufacturing environments. These constraints are pushing organizations to seek software-enabled productivity gains, not simply digitization for its own sake. The result is a market where value creation depends less on feature checklists and more on how effectively platforms reduce unplanned downtime, standardize compliance workflows, and integrate with broader enterprise systems.
Market Snapshot: Scale, Structure, and Core Challenges
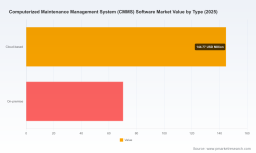
The overall market size has grown consistently from the early 2020s, with annual revenue progression reflecting broader enterprise software adoption cycles and the gradual normalization of cloud-first procurement. The 2025 baseline of 215 million USD serves as a reference point for understanding the pace of expansion into the late 2020s and early 2030s. Growth from 2026 onward accelerates as organizations complete initial migration waves and begin layering advanced functionality onto established maintenance workflows. The compound annual growth rate of 10.12 percent indicates a market that is expanding faster than general IT spending in many industrial sectors, but the growth is uneven across deployment models, use cases, and regional maturity levels.
Three core challenges define the current operating environment:
-
Deployment and data governance trade-offs. Organizations must balance the agility and lower upfront cost of cloud-based delivery against the control, latency, and regulatory requirements that still drive demand for on-premise or hybrid arrangements. The decision is no longer purely technical; it affects vendor lock-in, integration complexity, and long-term total cost of ownership.
-
Labor cost pressure and skills shortages. Rising labor expenses for maintenance technicians are forcing organizations to extract more output from existing teams. Software platforms that can standardize work orders, streamline scheduling, and reduce administrative overhead are increasingly viewed as operational necessities rather than optional tools.
-
Fragmented enterprise integration requirements. Maintenance does not operate in isolation. Asset data must connect with ERP, inventory, safety, and compliance systems. Platforms that fail to support clean data exchange or that require heavy customization struggle to scale beyond pilot deployments.
These challenges are not separate problems; they interact. A cloud-first deployment can reduce implementation friction, but only if the platform can integrate cleanly with existing enterprise systems and support the compliance posture of the organization. Likewise, labor cost pressures magnify the importance of usability and mobile access, since field technicians are unlikely to adopt tools that add complexity rather than reduce it. The market is therefore rewarding vendors that can simplify deployment while preserving flexibility, and penalizing those that force organizations into rigid implementation models.
Key Drivers Reshaping Demand and Value Creation
Technology Innovation and the Move Toward Intelligent Maintenance
The most consequential shift in the CMMS software market is the gradual embedding of advanced analytics, condition monitoring inputs, and AI-assisted decision support into maintenance workflows. Platforms are increasingly expected to move beyond scheduling and record-keeping toward predictive and prescriptive capabilities. This does not require every deployment to be fully AI-driven from day one, but it does raise the floor for what buyers consider viable. Solutions that can prioritize work orders based on asset criticality, surface recurring failure patterns, and reduce manual data entry are gaining preference over tools that simply digitize legacy processes. The practical impact is a narrowing gap between traditional CMMS functionality and broader enterprise asset management expectations, especially in environments where asset reliability directly affects production continuity and safety outcomes.
CMMS Software Market
Policy, Compliance, and Regulatory Expectations
Regulatory and standards-driven expectations continue to influence procurement decisions, particularly in sectors where equipment reliability intersects with safety, environmental compliance, or audit readiness. Maintenance records, inspection intervals, and corrective action tracking are increasingly subject to internal governance and external scrutiny. As a result, platforms that support documented workflows, traceability, and standardized reporting have an advantage in regulated contexts. This driver is less about sudden regulatory shocks and more about the cumulative effect of compliance becoming a permanent design requirement rather than a post-deployment add-on. Organizations are selecting platforms that can sustain auditable processes without heavy custom development, which in turn favors vendors with mature configuration options and clear data structures.
Demand-Side Behavior and the Operational Imperative
On the demand side, the dominant behavior change is the shift from reactive maintenance planning to more disciplined preventive and condition-informed approaches. This shift is being accelerated by the cost of unplanned downtime and the difficulty of scaling technician headcount quickly in tight labor markets. Maintenance teams are looking for systems that make it easier to standardize routines, capture asset history, and coordinate across shifts and sites. At the same time, executives are increasingly treating maintenance software as part of a broader operational resilience strategy. That means purchase decisions are less likely to be confined to the maintenance department alone and more likely to involve operations, finance, and IT stakeholders who evaluate the platform through the lens of total cost of ownership, uptime impact, and data usability.
Supply Chain and Cost Structure Dynamics
Cost structure changes in the broader industrial environment are also shaping purchasing behavior. Maintenance software buyers are more attentive to implementation effort, ongoing administration overhead, and the hidden costs of fragmented toolchains. In manufacturing and adjacent sectors, labor cost pressure has become a central consideration in vendor evaluation, since platforms that reduce coordination friction and improve first-time fix rates can meaningfully offset workforce expense. This is encouraging a preference for solutions that can be adopted incrementally, configured without extensive specialist dependence, and extended over time as organizational maturity grows. Cost is therefore not just a license or subscription question; it is increasingly a question of operational drag and change-management burden.
Competitive Landscape and Leading Strategies
The competitive environment reflects a mix of established enterprise players, specialist platforms, and vendors with strong positioning in particular deployment models or verticals. The market is moderately concentrated, with the largest firms holding meaningful but not overwhelming share. That structure leaves room for differentiation through product focus, deployment flexibility, vertical depth, and integration strategy rather than through price alone. Several strategic postures are visible across the field.
One clear pattern is the emphasis on AI-enabled asset operations and work order intelligence. Vendors in this group position their platforms as operational hubs that connect maintenance tasks, asset data, safety workflows, and integration points into a single interface. Their differentiation lies in reducing administrative effort, improving visibility into asset conditions, and making maintenance data more usable for planning and reliability teams. A second pattern centers on enterprise-grade mobility, compliance, and scale. These solutions target large operations where mobile access, standardized work orders, and auditable asset performance tracking matter as much as core scheduling functionality. Their value proposition is often tied to consistency across sites, support for complex organizational structures, and the ability to maintain governance over maintenance processes. A third pattern is cloud-native EAM/CMMS delivery aimed at multi-site and cross-industry use. These platforms emphasize accessibility, configuration breadth, and the ability to support asset and maintenance management without heavy on-premise infrastructure. They tend to compete on time-to-value, upgrade cadence, and the ease of scaling across locations.
Beyond these broad postures, several contextual shifts are shaping strategy. Recent product recognition for one of the incumbent platforms illustrates how analyst validation and sector reputation continue to influence buyer confidence, especially in procurement processes where risk aversion favors established names. At the same time, the market is not static. New entrants and adjacent platforms are expanding the definition of what a maintenance system can do, while larger portfolios are absorbing maintenance functionality into broader asset, facility, or workplace management offerings. IBM’s comprehensive CMMS/EAM orientation, for example, reflects the continued relevance of large-scale platforms that combine predictive maintenance emphasis with enterprise integration depth. Meanwhile, specialist vendors such as Aptean and AssetPoint highlight how tailored modules for manufacturers, scheduling, and supply chain linkage remain important in environments where maintenance cannot be separated from production planning or inventory dynamics.
The landscape is evolving along two simultaneous axes: consolidation and specialization. Consolidation is visible where buyers prefer fewer vendors, broader modules, and platforms that can cover maintenance, asset data, and adjacent workflows. Specialization persists where organizations need depth in particular verticals, mobile maintenance, or multi-site coordination. The most durable strategies appear to be those that combine a credible core maintenance experience with clear paths into integration, advanced analytics, and operational context. In practice, that means vendors must demonstrate not only that their system can manage work orders and assets, but also that it can fit into the way organizations actually run maintenance operations at scale.
Strategic Outlook: Three Trends Defining the Next Three to Five Years
Trend 1: Maintenance Platforms Become Reliability and Decision-Support Hubs
Over the next few years, CMMS software is likely to be evaluated less as a record-keeping system and more as an operational decision-support layer. The practical implication is that platforms will be expected to help prioritize interventions, connect maintenance data with asset performance indicators, and reduce the latency between issue detection and action. For commercial opportunities, this favors vendors that can make maintenance data immediately actionable without requiring extensive data science resources. It also creates room for solutions that can coordinate maintenance with inventory, parts availability, and scheduling constraints, since those factors often determine whether a work order is meaningful in practice.
Trend 2: Cloud-First Adoption Matures Into Integration-First Buying
Cloud adoption is already well underway, but the next phase of purchasing will increasingly emphasize integration quality, data portability, and fit with existing enterprise architecture. As organizations move past initial migration, the question shifts from where the software runs to how well it connects. This opens opportunities for platforms that offer clean APIs, prebuilt connectors, and configurable data models, especially for buyers who want to avoid prolonged customization cycles. It also raises the stakes for vendors that rely on heavy implementation services to make their tools viable, since integration friction can erode the cost and speed advantages that cloud delivery is supposed to provide.
Trend 3: Labor Economics Drive Productivity-Led Purchasing
Because maintenance labor represents a significant share of operational expenses in many industrial settings, buyers will continue to favor tools that directly improve technician productivity and reduce coordination waste. The commercial opportunity here is not simply selling software; it is proving that the platform can shorten administrative cycles, improve work order clarity, support mobile execution, and help teams manage more assets without proportionate headcount growth. This trend also raises the importance of change management and usability. Even strong platforms can underperform if they are difficult to adopt in daily field workflows, so vendors that invest in practical adoption paths are better positioned than those that rely on feature breadth alone.
These trends carry notable uncertainties. Adoption speed will depend on how quickly organizations can standardize asset data and overcome internal silos. The pace of advanced capability adoption may vary sharply between sectors, with some industries moving quickly toward predictive workflows while others remain focused on foundational discipline. Pricing pressure could intensify as buyers compare an expanding set of cloud options, and vendor differentiation may narrow if core maintenance features become commoditized. The organizations that benefit most will be those that treat CMMS software as part of a broader operating model transformation rather than a standalone IT purchase.
Actionable Implications for Decision Makers
For manufacturers and asset-intensive operators, the priority is to define maintenance maturity goals before evaluating tools. Platforms should be assessed against concrete operational outcomes such as reduced unplanned downtime, better work order closure quality, clearer asset history, and smoother coordination across sites or shifts. The most useful purchases are those that can be deployed incrementally, support mobile execution, and integrate with existing enterprise systems without extensive customization. Manufacturers should also weigh how well a solution can accommodate predictive and condition-informed workflows over time, since the platform selected today will shape how quickly advanced maintenance practices can be scaled tomorrow.
Preventive Maintenance Software Market
For investors and strategic analysts, the market rewards attention to integration strategy, deployment flexibility, and the ability to move upmarket without losing usability. The moderately concentrated structure suggests that share gains will likely come from clear product positioning and successful enterprise adoption rather than from broad commoditized competition. It is worth watching which vendors can convert cloud adoption into sticky, well-integrated deployments and which can demonstrate measurable productivity benefits in environments where labor costs and downtime risks are most acute. Differentiation in compliance support, multi-site coordination, and asset reliability workflows is likely to be more durable than differentiation in basic work order features alone.
PW Consulting
For procurement and IT leaders evaluating CMMS solutions, the practical question is whether the platform reduces operational friction or simply relocates it. Key evaluation criteria should include implementation burden, mobile usability for field staff, data model flexibility, integration readiness, and the vendor’s ability to support both immediate maintenance needs and longer-term reliability goals. Buyers should also consider how the vendor handles configuration, upgrades, and ongoing administration, since those factors often determine whether a deployment remains effective after the initial rollout. In markets where options are expanding, the differentiator is frequently not the presence of a feature but the ease with which the feature can be operationalized at scale.
For organizations seeking a more detailed view of segment-level dynamics, vendor positioning, and regional variation, a comprehensive market report can provide the granularity needed to translate these strategic themes into procurement plans, investment theses, and rollout roadmaps. Detailed breakdowns of deployment splits, application context, regional momentum, and vendor-specific developments help decision makers move from directional insight to execution-ready judgment. In a market where the pace of change is accelerating and the cost of poor selection is rising, the value of deeper intelligence lies in reducing uncertainty at the point of decision.
For detailed analysis of this topic, please visit the official page: Computerized Maintenance Management System (CMMS) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com