

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Thaumatin Market 2032: Beyond the 7.5% CAGR—Sweetener Shifts Reshaping Growth

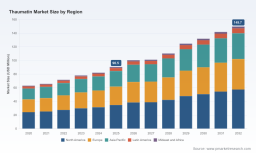
The Thaumatin Market: Strategic Trends and Commercial Opportunities Through 2032
The global thaumatin market has entered a phase of accelerating maturation, transitioning from a niche specialty ingredient to a strategically important component in the broader natural sweeteners and flavor modulation landscape. Valued at approximately $63.0 million in 2020, the market has expanded to $90.5 million by 2025, and forward projections indicate a trajectory toward $149.7 million by 2032. This expansion reflects a compound annual growth rate of 7.5 percent across the forecast period, a pace that signals sustained commercial momentum rather than a temporary cyclical upturn. The growth is not merely a function of volume expansion; it represents a structural shift in how manufacturers approach sugar reduction, flavor balancing, and clean-label formulation. Thaumatin's dual functionality as both a high-intensity sweetener and a taste-modifying agent positions it at the intersection of several converging demand forces, yet the market's evolution is shaped by constraints that require careful strategic navigation.
The current landscape is defined by a moderately concentrated competitive structure, with the top three players accounting for roughly 45 percent of combined revenue and the top five controlling just above half of the market. This concentration level suggests that while scale advantages exist, there remains meaningful room for specialized suppliers, regional distributors, and formulation-focused entrants to capture differentiated positions. The market's growth trajectory is not uniform across all segments; food-grade applications dominate the revenue mix, pharmaceutical-grade thaumatin commands a substantial secondary share, and a residual category supports niche industrial and specialty uses. Similarly, sweetening applications represent the largest end-use category, flavoring and taste-masking functions account for a significant portion, and a smaller share is distributed across auxiliary applications. These structural balances matter because they reveal where value creation is concentrated and where future margin opportunities are likely to emerge.
Market Dynamics and Structural Challenges
Despite the favorable growth outlook, the thaumatin market faces several interdependent challenges that will shape competitive outcomes over the next several years. The first and most fundamental constraint lies in raw material availability. Thaumatin is extracted from the katemfe fruit, which originates from a limited geographic base in West Africa. Total raw material exports from Ghana and Nigeria were approximately 210 metric tons in 2023, a volume that constrains the scale at which thaumatin can be produced and creates inherent supply elasticity limitations. This raw material bottleneck is not merely a logistical issue; it defines the ceiling for rapid volume expansion and makes supply chain resilience, farmer relationships, and extraction efficiency critical competitive variables. Companies that can secure stable katemfe access, optimize yield per ton of raw fruit, or develop blending strategies that reduce thaumatin intensity requirements will hold structural advantages in a supply-constrained environment.
A second challenge involves the tension between regulatory certainty and shifting nutritional labeling frameworks. Thaumatin benefits from a well-established regulatory foundation: it remains authorized as a sweetener and flavor enhancer in the European Union under Regulation (EC) No 1333/2008, and it is classified as generally recognized as safe by the FDA for use as a sweetener and flavor modifier in the United States. This regulatory clarity is a competitive asset that distinguishes thaumatin from newer or less-tested sweetener alternatives. However, regulatory approval alone does not guarantee commercial adoption. The European Commission's 2023 Nutri-Score algorithm, for instance, penalizes added sugars more heavily, which has accelerated reformulation efforts in beverages and cereal categories where thaumatin's role as a flavor enhancer and taste-balancing agent becomes commercially relevant. The challenge for manufacturers is that regulatory status and consumer perception do not always align; even authorized ingredients must navigate consumer skepticism around ultra-processed foods, label simplification expectations, and the broader clean-label movement that favors recognizable ingredient names.
A third structural challenge relates to cost and labor dynamics in the raw material supply chain. Small-scale farmers in West Africa handle cultivation and harvesting of the Thaumatococcus daniellii plant, and this labor-intensive model supports rural livelihoods but also introduces variability in yield quality, harvest timing, and supply consistency. Labor cost structures, weather variability, and the fragmented nature of smallholder cultivation can create fluctuations that ripple through extraction facilities and ultimately affect pricing stability for downstream customers. In a market where thaumatin already occupies a premium positioning relative to some bulk sweeteners, supply-side volatility can complicate long-term formulation commitments and contract negotiations. Addressing these constraints requires investment in farmer support programs, quality standardization initiatives, and potentially blended ingredient systems that reduce dependency on pure thaumatin volumes without sacrificing functional performance.
PW Consulting
Key Drivers Shaping the Market Trajectory
The market's expansion is being propelled by a combination of technological, regulatory, demand-side, and supply chain factors that reinforce one another. On the innovation front, formulation science has advanced significantly in using thaumatin not simply as a standalone sweetener but as part of blended systems designed to mitigate off-notes, enhance mouthfeel, and reduce the total sweetener load required to achieve target sensory profiles. Recent product launches illustrate this shift. In early 2025, Ingredion introduced a Reb M plus thaumatin blend developed for sugar-free yogurts, reporting a 38 percent reduction in aftertaste during European consumer trials. Around the same time, Natex UK Ltd launched the ThaumActive ready-to-use natural sweetener range tailored for flavored waters and protein beverages. These developments are meaningful because they demonstrate thaumatin's evolving commercial role: it is increasingly valued for its ability to improve the sensory quality of reduced-sugar and high-protein formats, rather than solely for its sweetness intensity.
Regulatory and policy dynamics provide another layer of momentum. The continued authorization of thaumatin across major markets gives formulators a predictable compliance pathway, which is especially valuable in categories such as beverages, dairy alternatives, and functional foods where ingredient scrutiny is high. At the same time, public health-oriented labeling and sugar taxation pressures are pushing manufacturers to reduce added sugar without sacrificing taste acceptance. Thaumatin's taste-modifying properties make it particularly useful in these reformulation scenarios, where it can soften bitterness from high-intensity sweeteners, improve the perceived sweetness profile at lower dosages, and support cleaner ingredient declarations when used in moderation. This regulatory and reformulation environment creates a durable demand pull, but it also favors suppliers who can offer technical support, application-specific guidance, and proven blend compatibility rather than bulk commodity pricing alone.
Consumer and enterprise behavior is shifting in ways that reinforce thaumatin's relevance. The broader sugar reduction trend is no longer confined to confectionery or soft drinks; it now extends to dairy, baked goods, RTD beverages, and sports nutrition formats. At the same time, the clean-label and natural ingredients movement favors plant-derived sweeteners with established regulatory histories over synthetic alternatives. Thaumatin's botanical origin and multi-functional profile align well with these preferences, particularly in premium and health-oriented product tiers where ingredient narrative matters. For large food and beverage manufacturers, thaumatin is increasingly evaluated not just on cost per unit of sweetness but on total formulation value, including taste modulation, label positioning, and compatibility with other natural ingredients.
Supply chain and cost structure changes are also reshaping competitive dynamics. Because katemfe supply is geographically concentrated and relatively limited, companies with integrated or closely coordinated sourcing arrangements are better positioned to manage price stability and supply continuity. At the same time, advancements in extraction efficiency, quality control, and downstream blending capabilities can improve the effective economics of thaumatin use. Suppliers that invest in application-focused formulation services, ready-to-use ingredient formats, and consistent batch quality can command stronger value capture even in a supply-limited environment. This dynamic is gradually rewarding capability-driven players over pure volume players, particularly as end-users seek to minimize formulation risk while navigating sugar reduction targets.
Competitive Landscape and Strategic Positioning
The competitive field features a mix of international ingredient companies, regional specialists, and distribution-focused suppliers. Tate & Lyle operates as a broad natural high-intensity sweetener producer, leveraging thaumatin within a wider portfolio that serves food and beverage applications. Its strategic advantage lies in scale, application breadth, and the ability to position thaumatin alongside complementary sweetening and texturizing ingredients. Naturex, now aligned with Givaudan, brings a natural ingredients and flavor expertise that supports thaumatin's use in taste-modulation contexts, especially where sensory balance and label-friendly positioning are priorities. Natex UK Ltd has carved out a specialist identity with a strong focus on natural thaumatin and formulated sweetening solutions, including its Sweetence brand, and its recent launch of ready-to-use formats for flavored waters and protein beverages reflects a deliberate move toward application-ready offerings that reduce customer formulation burden.
Van Wankum Ingredients and Silver Fern Chemical operate more on the supply and distribution side, connecting manufacturers with thaumatin supply for food and industrial applications, while Penta Manufacturing Company provides thaumatin as a natural sweetener and flavor enhancer with a U.S.-based commercial footprint. These companies illustrate a market where differentiation can come from multiple directions: portfolio breadth, technical formulation capability, regional supply reliability, or specialized customer segments. The presence of both established multinationals and focused specialists creates a competitive environment in which customer value is increasingly determined by service depth, application knowledge, and supply consistency rather than price alone.
The market structure is evolving along two parallel tracks. On one hand, there is consolidation pressure as larger ingredient groups seek to strengthen their natural sweetener portfolios and capture cross-selling opportunities across sweetening, flavor, and functional ingredients. On the other hand, there is room for fragmentation and specialization, particularly in application-tailored formats, regional market focus, and niche health-oriented categories. New entrants and smaller companies can compete by developing proprietary blends, securing reliable katemfe access through strong farmer relationships, or concentrating on underserved applications such as high-protein beverages, functional waters, or premium dairy alternatives. The strategic lesson is that thaumatin's market does not reward generic participation; it rewards companies that can link supply reliability with formulation utility and customer-specific technical support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, several trends are likely to define thaumatin's commercial trajectory. The first is the growth of blended, application-specific sweetening systems. As formulators continue to balance taste, cost, label clarity, and sugar reduction goals, thaumatin's value will increasingly be expressed in combination with other natural sweeteners and flavor modulators. Ready-to-use blends and pre-balanced formulations will become more important because they reduce development time and sensory risk for customers, especially smaller manufacturers and private-label producers who may lack extensive in-house formulation resources. This trend favors suppliers that can offer standardized, application-tested formats with documented sensory outcomes.
The second trend is the widening of thaumatin's application footprint beyond traditional sweetener uses. Its function as a flavor enhancer and taste-masking agent is becoming more commercially visible in categories such as high-protein beverages, sugar-reduced dairy, and functional drinks where off-note suppression is critical. If this trajectory continues, thaumatin's revenue mix could gradually shift toward more value-added application contexts, where pricing power is supported by technical differentiation rather than commodity positioning. The opportunity here is substantial for companies that invest in sensory research, category-specific formulation guidance, and collaboration with customers during product development.
Saccharin Market
The third trend involves supply chain maturation and potential geographic diversification. Given the current concentration of katemfe exports from Ghana and Nigeria, any initiative that improves cultivation practices, expands responsible sourcing, or enhances extraction yield could meaningfully affect market capacity and price stability. At the same time, efforts to standardize raw material quality and strengthen farmer partnerships may reduce supply variability and improve long-term planning for downstream users. However, uncertainty remains. Crop sensitivity, climate conditions, and the social and economic complexity of smallholder supply chains mean that supply expansion cannot be taken for granted. Companies should treat raw material resilience as a strategic priority rather than an operational detail.
These trends create clear commercial opportunities, but they also carry risk. If sugar reduction momentum slows in certain categories, or if alternative sweeteners gain stronger consumer acceptance at lower cost points, thaumatin's growth rate could face headwinds. If regulatory frameworks evolve in ways that alter labeling expectations or ingredient disclosure norms, manufacturers may need to adapt formulation strategies quickly. And if supply chain disruptions affect katemfe availability, price volatility could test customer relationships and margin structures. The businesses best positioned to navigate these uncertainties will be those that build flexible sourcing, maintain strong technical credibility, and differentiate through formulation value rather than price competition alone.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat thaumatin as a formulation enabler rather than a standalone sweetener. Integrating thaumatin into blended systems, investing in sensory validation early in the development cycle, and selecting suppliers with demonstrated application support can shorten time-to-market and improve taste outcomes in reduced-sugar formats. Companies should also evaluate ready-to-use and pre-blended options where they exist, especially for categories like flavored waters, protein beverages, and sugar-reduced dairy, where sensory balance is difficult to achieve with single-ingredient approaches.
For investors and strategic planners, thaumatin represents a market with steady structural growth and clear differentiation opportunities, but success depends on identifying players with credible supply relationships, formulation capabilities, and application-focused product architectures. Capital allocation and partnership decisions should weigh not only revenue trajectory but also raw material resilience, technical service depth, and the ability to capture value in higher-margin application segments. Companies that rely purely on commodity-style participation may face margin pressure, while those with specialty positioning and customer lock-in through formulation expertise are better placed to sustain value capture.
For procurement and supply chain leaders, securing predictable thaumatin supply requires a proactive approach. Long-term supplier relationships, quality consistency requirements, and contingency planning for raw material variability should be central to sourcing strategy. Where possible, procurement teams should collaborate with suppliers on traceable sourcing, batch standardization, and blended options that reduce exposure to pure thaumatin volume constraints. Building flexibility into specification and formulation parameters can also help mitigate the impact of supply fluctuations without compromising product quality or label commitments.
Understanding thaumatin's market trajectory at this level of detail is essential for companies making multi-year formulation, sourcing, and investment decisions. Broad growth figures provide useful context, but the real strategic value lies in segment-specific demand patterns, application-level performance data, regional sourcing dynamics, and competitor capability mapping. For decision-makers who need granular segmentation, scenario analysis, and customized recommendations tailored to specific product categories or markets, the complete PW Consulting research report offers a more detailed view of the data and strategic options that can inform next steps.
Thymol Market
For detailed analysis of this topic, please visit the official page: Thaumatin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com