

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Medical Shower Chairs Market: Why 5.6% CAGR and Home Care Demand Are Redefining Growth Through 2032

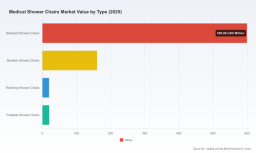
Strategic Trends and Commercial Opportunities in the Medical Shower Chairs Market
The medical shower chairs market is entering a phase of sustained expansion, driven by demographic shifts and evolving care delivery models. Market revenue climbed from approximately $605.2 million in 2020 to $800.0 million in 2025, reflecting steady year-over-year momentum. Forecasts indicate this trajectory will continue through 2032, with the market projected to surpass $1.1 billion. This growth translates to a compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. The sector’s expansion is not a simple continuation of historical patterns; it reflects structural changes in how mobility support equipment is designed, procured, and reimbursed. Understanding these underlying forces is essential for manufacturers, investors, and procurement leaders seeking to position themselves ahead of market shifts rather than react to them.
Shower Trolley Market
Market growth is being shaped by several concurrent pressures. Aging populations across developed economies are increasing the prevalence of conditions that impair safe bathing, including neurodegenerative diseases and post-surgical mobility limitations. At the same time, healthcare systems are shifting more rehabilitation and long-term care functions into community and home settings. This transition raises demand for equipment that is both clinically appropriate and adaptable to non-institutional environments. A second pressure comes from regulatory scrutiny. Device recalls and adverse event reporting have reinforced expectations around quality system compliance, material durability, and locking mechanism reliability. Manufacturers that treat these as routine compliance exercises risk reputational and operational exposure, while those that embed safety verification into product development cycles are strengthening market trust. A third challenge lies in reimbursement uncertainty. Coverage decisions increasingly hinge on documented medical necessity, functional assessments, and evidence that standard bathing alternatives cannot be used safely. This changes how suppliers must position products and how care providers justify procurement.
Lift Chair Market
Technology Innovation and Clinical Design Shifts
Product development is moving beyond basic seating platforms toward integrated mobility and positioning solutions. Manufacturers are incorporating narrow compact frames, slim wheels, and three hundred and sixty-degree access configurations that reduce caregiver strain and improve maneuverability in tight bathroom layouts. Tilt and recline mechanisms are becoming more refined, with manual and powered options tailored to varying levels of patient independence and caregiver assistance. Color variants and material finishes are also gaining attention, particularly for institutional procurement teams that balance clinical utility with environmental aesthetics and user dignity. These design choices are no longer cosmetic; they are functional differentiators that affect adoption in hospitals, rehabilitation centers, and private homes.
Powered models and modular configurations represent a meaningful breakpoint in the market. Equipment that supports complex positioning criteria for patients with significant physical disabilities is expanding the addressable population beyond users who only need static seating support. This shift aligns with broader trends in person-centered bathing solutions, where the objective is to preserve patient comfort while standardizing safe transfer and hygiene routines. For commercial players, the implication is clear: product portfolios that offer configurable height, tilt, and access features can capture demand across multiple care settings without requiring separate product lines for each segment.
Policy and Reimbursement Dynamics
Reimbursement frameworks are a decisive factor in purchase behavior. Bath and shower chairs are covered under Medicare and Medicaid plans when medically necessary, subject to standardized evaluation criteria that assess whether a patient cannot safely use regular bathtubs or showers. Documentation expectations now commonly include a face-to-face physician examination within a defined period and specialty evaluations from occupational or physical therapists. These requirements shape procurement timelines and influence which products proceed through approval workflows.
Recent policy activity underscores how coverage language can influence category access. In April 2026, a Medicare Advantage organization obtained a favorable ruling in an appeal for coverage of a rolling shower chair that met complex positioning criteria for significant physical disability. This outcome illustrates that coverage is not static; it can expand when clinical justification demonstrates functional need that conventional equipment cannot address. At the same time, supplier cost structures remain uneven. Medicare durable medical equipment supplier costs for rolling shower chairs can exceed four thousand dollars, with reimbursement limited to covered plans under complex positioning requirements. This gap between cost and reimbursement creates pressure on pricing strategies and emphasizes the importance of clear clinical documentation and appropriate coding practices.
Regulatory oversight continues to influence product reliability expectations. Adverse event reports and Class II device recalls involving certain shower chair models have drawn attention to quality system compliance, locking integrity, and load-bearing stability. These developments do not halt market growth, but they sharpen procurement risk assessment. Purchasers increasingly evaluate manufacturers on their ability to demonstrate consistent production controls, traceability, and post-market surveillance. Companies that can provide transparent quality records and rapid issue resolution gain a tangible advantage in institutional tenders and home-care distribution channels.
Demand-Side Behavior and Care Setting Transition
User demand is being reshaped by where care is delivered and who participates in equipment selection. Home care remains the dominant application area, reflecting patient preference, cost containment pressures, and the expansion of outpatient rehabilitation services. Families and home-health providers now prioritize equipment that is easy to install, clean, and store, while still meeting weight capacity and safety requirements. This is especially relevant as more households adapt bathrooms for aging-in-place use rather than relying exclusively on facility-based solutions.
Hospitals and rehabilitation centers continue to be important adopters, but their purchasing logic is evolving. Caregiver safety has become a more explicit procurement criterion, with facilities favoring powered options and designs that reduce manual handling risk during transfers. Long-term care facilities, while smaller in relative volume, provide stable recurring demand and tend to value standardization across units, ease of maintenance, and compatibility with existing hygiene workflows. The commercial implication is that product positioning should not assume a single buying profile. In home care, usability and storage often dominate; in institutional settings, caregiver ergonomics, durability, and documentation compatibility can outweigh other factors.
Supply Chain, Cost Structure, and Procurement Realities
Cost structure pressures are coming from multiple directions. Raw material volatility, component specialization, and the need for repeated safety testing contribute to higher baseline production costs for advanced models. At the same time, reimbursement ceilings and coverage limitations constrain the pricing flexibility of suppliers that depend heavily on public payment pathways. This dynamic is pushing manufacturers to differentiate through configuration rather than price competition alone. Modular designs, accessory ecosystems, and serviceable components can reduce total cost of ownership for facilities that must balance acquisition cost with maintenance and replacement cycles.
Procurement teams are also becoming more disciplined in their evaluation criteria. Safety-tested designs, adjustable height and tilt functions, and clearly documented weight capacities are increasingly treated as baseline expectations rather than premium features. Suppliers that fail to provide clear technical specifications or that rely on vague performance claims face longer approval cycles and greater scrutiny. For distributors, this environment favors inventory 전략의 that align with documented demand patterns in home care and institutional segments, reducing exposure to overstocked SKUs that do not match reimbursement realities or facility specifications.
Competitive Landscape and Leading Strategies
The market remains relatively fragmented, with the top three participants holding roughly twenty-five percent of share and the top five approaching thirty percent. This concentration indicates that no single manufacturer dominates the category, leaving room for differentiated positioning and targeted segment strategies. The market is large enough to support multiple product philosophies, but it is also demanding enough that generic offerings face increasing difficulty in securing both institutional contracts and sustained home-care distribution.
Several leading companies illustrate distinct strategic approaches. ActiveAid emphasizes modular, self-propelled shower and commode chairs with narrow compact frames, slim wheels, three hundred and sixty-degree access, and tilt or recline options. Its recent expansion into broader color variants reflects an effort to support hospital, institutional, and home use with a consistent platform. This approach signals a focus on adaptability and visual integration across environments, which can matter in facilities that value uniformity as well as in home settings where equipment appearance influences user acceptance.
Arjo positions itself around person-centered bathing solutions, offering shower systems, chairs, and trolleys with powered options and caregiver safety features. Its emphasis on diverse mobility levels and powered assistance aligns with the institutional trend toward reducing caregiver strain and standardizing safe bathing routines. By embedding safety and ergonomics into the product narrative, Arjo targets procurement teams that prioritize workforce protection and clinical workflow consistency.
PW Consulting Health Care Research Center
DHG focuses on shower chairs and transfer benches with adjustable features, defined weight capacities, and safety-tested designs for patient comfort in hospital and home settings. This positioning is practical and specification-driven, appealing to buyers who need clear performance parameters and repeatable configurations. DHG’s approach highlights the commercial value of transparent technical documentation and product consistency across settings.
Etac provides shower commodes such as Alto, Swift Mobil, and Swift Mobil Tilt-2, with powered or manual options, three hundred and sixty-degree access, ergonomic design, and adjustable height or tilt. Its portfolio supports both user and caregiver needs, which is particularly relevant where patient mobility varies widely within the same facility or household. Etac’s broader international heritage, combined with U.S. market presence, also illustrates how established design reputations can support credibility in a category where safety and usability are closely scrutinized.
Invacare offers the I-Fit shower chair and Ocean series with tilt or recline, powered models, and accessories for bariatric and standard users. Its breadth across weight classes and feature levels reflects a strategy of covering multiple patient profiles with interconnected product lines. This can simplify catalog management and cross-selling, but it also requires rigorous quality oversight given that shower chair models in this category have appeared in adverse event reporting and recall activity. The lesson for competitors is consistent: product variety must be matched by disciplined production and post-market controls.
The overall competitive pattern suggests a market that rewards specialization without sacrificing platform flexibility. Leaders are differentiating through powered access, modular framing, caregiver-centric safety features, and clearer documentation of use cases and capacities. At the same time, market evolution is likely to see continued consolidation pressure among smaller suppliers who cannot sustain compliance costs or distribution reach, while new entrants may focus on underserved niches such as compact home-use configurations, bariatric-specific designs, or equipment that integrates more smoothly with existing bathroom layouts.
Future Trends and Commercial Implications
Over the next three to five years, one major trend will be the continued expansion of powered and complex positioning solutions. As reimbursement pathways for advanced models become clearer through case-by-case appeals and updated clinical criteria, demand for tilt, recline, and powered mobility options should increase, particularly in rehabilitation and complex-disability settings. This opens commercial opportunities for manufacturers that can prove functional benefit and support documentation workflows, but it also raises the bar for engineering reliability and service support.
A second trend is the deepening alignment between product design and home-care adoption. As more bathing support equipment is procured for private residences, buyers will favor designs that combine safety with straightforward installation, cleaning, and storage. Manufacturers that offer compact frames, secure locking mechanisms, and materials suited to frequent sanitation will be better positioned in this channel. There is also room for bundled accessories and configuration guidance that help families and home-health providers match equipment to specific bathroom constraints.
A third trend is the growing influence of risk and compliance visibility in purchasing decisions. Given ongoing recalls and adverse event reporting, procurement teams are likely to place greater weight on quality system transparency, post-market monitoring, and documented testing. Suppliers that can communicate their compliance processes clearly and respond quickly to issues will gain trust. This creates an opportunity for companies to build reputation capital around reliability, not just product features. The associated risk is that regulatory attention may continue to affect specific models and production batches, requiring manufacturers to maintain agile quality controls and proactive communication.
Actionable Guidance for Decision Makers
Manufacturers should prioritize platform flexibility over narrow feature competition. Equipping product lines with modular tilt or recline options, clear weight classifications, and caregiver-friendly access designs can expand addressable demand across home care, hospitals, and long-term care facilities without fragmenting production. Equally important is investing in documentation that supports medical necessity pathways and procurement evaluation, since reimbursement clarity and specification transparency increasingly determine purchase speed.
Investors should evaluate exposure to advanced positioning and powered models, as well as the strength of each company’s quality and compliance infrastructure. Growth in the category is likely, but returns will be shaped by which participants can manage cost structure pressures, maintain reimbursement-relevant documentation, and respond effectively to safety scrutiny. Portfolio concentration in home-care-friendly configurations and bariatric-capable designs may provide resilience across economic and reimbursement cycles.
Procurement leaders should standardize evaluation criteria around safety-tested design, adjustable height and tilt, defined weight capacity, locking reliability, and documentation compatibility. Rather than selecting products on appearance or price alone, purchasing teams can reduce downstream risk by aligning acquisitions with caregiver workflow needs and patient positioning requirements. For facilities managing mixed user profiles, configurable platforms can reduce inventory complexity while preserving appropriate clinical support.
The commercial landscape in this market is evolving quickly enough that strategic decisions benefit from current segment definitions, regional demand patterns, and reimbursement detail. A deeper view of these dynamics can help organizations translate broad trends into product, pricing, and procurement choices that are better aligned with near-term reality. Readers seeking a more granular breakdown of market segments, share shifts, and actionable entry points can refer to the complete PW Consulting market research report for detailed segmentation data and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Medical Shower Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com