

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Reformer Unit Market to Hit $1,383.65M by 2032, 6.95% CAGR
By pmarketresearch, 2026-09-16
Global Reformer Unit Market Outlook 2026: Strategic Intelligence for Industrial Decision Makers
Market Trajectory and Structural Resilience
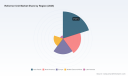
The Worldwide Reformer Unit Market represents a critical nexus in global industrial infrastructure, underpinning hydrogen generation, ammonia synthesis, methanol production, and oil refining operations. As organizations navigate capital allocation decisions through the late 2020s, understanding the revenue trajectory and structural drivers within this sector has become indispensable. Our latest market research delivers a comprehensive assessment of an industry that expanded from 620.5 Million USD in 2020 to an estimated 864.5 Million USD in 2025, reflecting consistent year-over-year momentum through evolving feedstock landscapes and shifting regulatory environments.
Worldwide Reformer Unit Market
Looking ahead, the forecast horizon spanning 2026 through 2032 projects sustained expansion with a compound annual growth rate of 6.95 percent. This trajectory points toward a market exceeding 1.3 Billion USD by the close of the forecast window. The underlying demand architecture is multifaceted, driven by expanding hydrogen economy initiatives, low-carbon ammonia ventures, and ongoing refinery modernization programs. Critically, this growth narrative is not a simplistic extrapolation of historical volumes. It reflects transformative shifts in reformer technology selection, geographic deployment patterns, and the commercial calculus surrounding decarbonization compliance.
For executives evaluating procurement strategies, capacity expansion plans, or technology licensing partnerships, the distinction between historical performance and forward-looking inflection points carries substantial financial weight. The market's acceleration trajectory is increasingly tied to regulatory timelines, feedstock flexibility requirements, and the competitive positioning of engineering firms that can deliver integrated, low-emission reformer solutions at commercial scale. Our research dissects these variables with granular precision while maintaining the analytical ambiguity necessary for proprietary advantage.
Segmentation Architecture and Demand Concentration
Reformer unit procurement decisions are inherently segmented across type, application, and geographic deployment zones, each carrying distinct technical specifications and commercial implications. The market ecosystem encompasses steam methane reforming configurations, catalytic reforming platforms, and autothermal reformer designs, with procurement volumes and revenue contribution varying across industrial end-uses including hydrogen production, ammonia manufacturing, methanol synthesis, and oil refining operations. Understanding the precise weighting of these segments informs everything from supplier negotiation leverage to long-term technology roadmapping.
Geographic distribution patterns further complicate strategic planning. Industrial development across Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America exhibits divergent pacing driven by localized energy transition mandates, feedstock availability, and infrastructure investment cycles. Buyers operating across multiple jurisdictions must reconcile these regional variances against centralized procurement targets, a complexity that standard industry summaries rarely capture with sufficient operational granularity.
Market concentration metrics offer additional insight into the competitive equilibrium. The industry remains moderately consolidated, with the top three firms commanding significant revenue share and the top five collectively representing a substantial majority of market activity. This concentration shapes pricing dynamics, licensing negotiations, and the strategic behavior of both incumbent technology providers and emerging equipment manufacturers. Organizations seeking to enter supplier relationships or evaluate partnership opportunities must account for the bargaining power embedded within this concentration structure.
Competitive Landscape: Major Players and Strategic Moves
The reformer unit market features a diversified competitive field spanning engineering contractors, technology licensors, catalyst specialists, and high-temperature component manufacturers. Each participant brings distinct capability profiles that influence procurement decisions across different application verticals and project scales.
Linde Engineering has established a formidable footprint through the delivery of over 250 reforming furnaces worldwide, offering top-fired, side-fired, and wall-fired configurations alongside its HYDROPRIME modular cylindrical and skid-mounted solutions. The company's emphasis on heat recovery optimization and low-emission revamps positions it favorably within hydrogen, syngas, ammonia, and methanol applications. Recent activity underscores this strategic direction: in February 2025, Linde Engineering secured a record number of small on-site solutions including hydrogen-related plants driven by decarbonization priorities, and in June 2025, Linde signed a long-term industrial gas supply agreement for a world-scale low-carbon ammonia facility incorporating autothermal reforming.
Honeywell UOP and Axens dominate the catalytic reforming segment, supplying process technologies, catalysts, and modular equipment for refinery reformer units. Honeywell UOP focuses on semi-regenerative and continuous catalytic reforming licensing with high-octane gasoline and aromatics as primary outputs. Axens contributes its Octanizing CCR processes and semi-regenerative solutions, supported by over 130 licenses globally, with integrated offerings spanning gasoline production, aromatics, and residue upgrading. Both firms remain central to refinery modernization strategies as operators seek to balance throughput targets against emissions constraints.
Worldwide Steam Reformers Market
KBR and Technip Energies provide complementary engineering and licensing capabilities across steam methane reforming and autothermal reforming for hydrogen and syngas applications, with Technip Energies also delivering comprehensive EPC services. Johnson Matthey addresses the catalyst layer through its KATALCO series and pre-reforming formulations optimized for ammonia, methanol, hydrogen, and gas-to-liquid production, directly influencing reformer efficiency and operational lifespan.
Component-level suppliers such as MetalTek International and Kubota Corporation supply centrifugally cast reformer tubes, outlet manifolds, and heat-resistant cast steel components designed for extended creep-resistant service life of 10 to 12 years or more in high-temperature and high-pressure environments. Wood plc and Larsen & Toubro Limited round out the competitive field through engineering, consulting, and construction engagements spanning refining and hydrogen production contexts. Topsoe's October 2025 conference presentation on electrifying steam reformers as a sustainable hydrogen pathway signals growing industry focus on next-generation process electrification, reinforcing the competitive imperative around innovation velocity.
Industry Dynamics Shaping 2026 Decision-Making
Several converging forces are reshaping procurement timelines and technology selection criteria across the reformer unit ecosystem. Energy efficiency mandates and decarbonization requirements are accelerating adoption of electrified steam reformer configurations capable of reducing direct flue gas carbon dioxide emissions by substantial margins while improving thermal efficiency in existing ammonia plant installations. Concurrently, stricter greenhouse gas emission regulations and carbon pricing mechanisms are exerting financial pressure on conventional fuel-fired reformer architectures, prompting operators to evaluate electrification pathways and carbon capture integration as viable compliance strategies.
Hydrogen economy initiatives and low-carbon ammonia and hydrogen project pipelines continue to sustain demand for advanced reformer designs characterized by enhanced efficiency metrics and carbon capture compatibility. These project-level drivers interact with macroeconomic variables, particularly raw material cost trajectories. Global steel prices, which serve as the primary input for reformer tubes and pressure vessels, are positioned at or near the bottom of the current price cycle entering 2026, with subdued recovery anticipated through the year and a more meaningful upturn projected from 2027 onward. This cost dynamic carries direct implications for equipment procurement budgets, contract timing, and vendor negotiation leverage.
The interplay between regulatory pressure, technology availability, and input cost cycles creates a decision environment where timing and specificity matter enormously. Organizations that delay evaluation of electrified or hybrid reformer configurations risk exposure to rising compliance costs and potential capacity constraints as supplier order books fill. Conversely, premature commitment without accurate segment-level intelligence can result in suboptimal capital deployment, misaligned technology selection, or unfavorable commercial terms.
Research Methodology and Report Scope
Our Worldwide Reformer Unit Market research is structured to deliver actionable intelligence across multiple decision dimensions. The report integrates quantitative market sizing with qualitative technology and competitive analysis, providing a single reference point for strategic planning teams. Key components include detailed segmentation breakdowns by type, application, and region, with revenue estimates and growth trajectories mapped across the historical 2020 through 2025 period and the forecast 2026 through 2032 window.
The competitive profiling section delivers individualized company assessments encompassing headquarters location, core technology offerings, recent project activity, and strategic positioning within specific reformer sub-markets. These profiles are supplemented by a curated timeline of recent industry developments, capturing conference presentations, project award milestones, long-term supply agreements, and regulatory announcements that signal near-term market direction.
Demand-side analysis examines application-specific drivers across hydrogen, ammonia, methanol, and oil refining verticals, while regional assessments contextualize deployment pacing against localized policy frameworks, infrastructure investment cycles, and feedstock economics. The report further integrates upstream cost dynamics, including steel and alloy material trends, to inform procurement timing strategies and budget forecasting. Market concentration metrics and competitive equilibrium analysis support supplier evaluation and partnership structuring decisions.
Strategic Implications for Corporate Planning
The reformer unit market sits at the intersection of energy transition imperatives, refinery modernization requirements, and industrial gas demand growth. For executives navigating 2026 planning cycles, the strategic question is no longer whether this market will grow, but how the growth will be distributed across technologies, geographies, and supplier ecosystems. Our research provides the depth required to answer that question with confidence.
Organizations evaluating new capacity investments must weigh the technical trade-offs between steam methane, catalytic, and autothermal configurations against localized regulatory timelines and feedstock economics. Procurement teams negotiating with engineering contractors and component suppliers must incorporate steel price cycle projections and concentration-driven pricing dynamics into cost models. Technology strategists assessing electrification and carbon capture integration pathways require precise benchmarks on efficiency gains, emission reduction potential, and commercial availability timelines.
Contact our research team to access the full Worldwide Reformer Unit Market report and secure the granular data, segmentation breakdowns, and competitive intelligence necessary to sharpen your 2026 strategic positioning. The complete dataset, detailed regional and application-level analysis, and extended company profiles are available exclusively through our direct research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cake Pans Market Hits $1.59B in 2025, Forecasted to Reach $2.46B by 2032
By pmarketresearch, 2026-09-16
Navigating the Global Cake Pans Market: Strategic Intelligence for 2026 and Beyond
The global kitchenware sector is experiencing a renaissance, driven by a resurgence in home baking, the expansion of artisanal bakery chains, and evolving consumer preferences for specialized cookware. At the heart of this ecosystem lies the cake pans market, a foundational segment that bridges raw material manufacturing, retail distribution, and end-user culinary performance. As we move further into the mid-2020s, understanding the trajectory, competitive architecture, and regulatory contours of this market is no longer optional for stakeholders. It is a prerequisite for resilient growth.
PW Consulting is pleased to introduce our latest comprehensive study: the Worldwide Cake Pans Market. This report is engineered to convert macro-level industry signals into actionable strategic intelligence. Designed for executives in manufacturing, supply chain management, retail leadership, and investment analysis, our research provides a rigorous, data-driven foundation for navigating the forecast period from 2026 to 2032.
Market Trajectory and the 2026 Inflection Point
The cake pans market has demonstrated remarkable resilience and growth over the past half-decade. Drawing on historical data from 2020 through 2025 and projecting forward, our analysis reveals a sector moving from a global valuation of approximately 1.1 billion USD in 2020 to a substantial 1.58 billion USD by 2025. This expansion underscores a consistent upward demand curve, influenced by heightened culinary engagement, the proliferation of baking content across digital platforms, and steady commercial bakery investments.
Looking ahead, the forecast period from 2026 to 2032 is positioned for sustained momentum. The market is projected to continue its growth trajectory, reaching a valuation that will underscore the segment's increasing strategic weight within the broader houseware and specialty retail categories. A compound annual growth rate of 6.48 percent reflects not only steady consumer demand but also the ongoing maturation of distribution networks and product innovation cycles. For decision-makers, this CAGR is more than a numerical indicator; it represents the pace at which capital allocation, inventory planning, and product development strategies must be calibrated to maintain competitive parity.
Structural Dynamics: Material, Channel, and Regional Interplay
The evolution of the cake pans market is fundamentally shaped by three intersecting forces: material innovation, channel transformation, and regional divergence in purchasing behavior. Our research dissects these dimensions to reveal how value is created, captured, and contested across the supply chain.
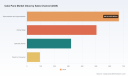
Material composition remains a critical battleground. The market is anchored by a diverse array of substrates, each offering distinct performance profiles, cost structures, and end-user value propositions. Metal-based solutions continue to dominate a significant portion of total revenue, driven by their thermal conductivity, durability, and compatibility with both home and commercial baking environments. Within this category, aluminum-based products, including anodized variants, command a prominent share, reflecting their widespread adoption among professional bakeries and discerning home users alike. Carbon steel and aluminum-composite alternatives further expand the material landscape, offering manufacturers flexible pathways to balance performance, weight, and production costs. Meanwhile, non-metallic categories such as silicone, glass, and ceramic have cultivated dedicated followings, appealing to consumers and artisans who prioritize non-stick convenience, aesthetic presentation, and specialized heat-retention properties. This multi-material ecosystem creates a complex value matrix where product positioning, price tiering, and target-user segmentation are inextricably linked.
Worldwide Cake Pans Market
The distribution architecture is undergoing a parallel transformation. Traditional brick-and-mortar formats, particularly supermarkets and hypermarkets, remain powerful engines of volume, leveraging their broad foot traffic and one-stop shopping appeal. At the same time, online retail channels have matured into formidable growth vectors, accelerated by improved logistics infrastructure, social commerce integration, and the consumer shift toward digital discovery and direct purchasing. Specialty stores and direct-to-consumer models further enrich the channel mix, offering niche products, curated assortments, and brand storytelling opportunities that resonate with premium and enthusiast segments. The interplay between these channels dictates not only revenue allocation but also the strategic priorities around brand visibility, inventory velocity, and customer acquisition cost management.
Regionally, the market exhibits distinct demand characteristics that reflect local baking traditions, economic conditions, retail maturity, and import-export dynamics. North America and Europe together represent mature, high-value arenas where brand differentiation, product quality, and regulatory compliance are paramount. Asia Pacific presents a compelling growth narrative, fueled by urbanization, rising disposable incomes, and the expanding footprint of modern retail and e-commerce. Latin America and the Middle East and Africa, while representing more nascent but promising spaces, offer long-term potential tied to the gradual formalization of retail channels and the growing visibility of global baking culture. Our report maps these regional nuances without reducing them to static snapshots, instead providing the contextual intelligence necessary to prioritize market entry, expansion, or resource reallocation with confidence.
Competitive Architecture: Incumbents, Innovation, and Strategic Positioning
The global cake pans market is characterized by a moderately concentrated competitive landscape, with a handful of leading players capturing a meaningful portion of total industry revenue, while a broader tier of specialized and regional manufacturers competes on differentiation, pricing, and channel access. Our analysis identifies a diverse set of enterprises that collectively define the market's strategic contours.
Established North American manufacturers such as Nordic Ware and Wilton Brands LLC have long been synonymous with reliable, design-forward bakeware, serving both professional decorators and home bakers through iconic product lines that span round layer pans, Bundt varieties, and seasonal formats. USA Pan and Fat Daddio's compete in the commercial-grade and performance-oriented segments, emphasizing aluminized steel and anodized aluminum constructions engineered for even heating, non-stick efficacy, and durability under repeated professional use. Calphalon LLC extends this premium logic into the broader consumer space, leveraging its reputation for high-end non-stick bakeware to capture users who prioritize longevity and consistent results.
International manufacturers contribute critical depth to the competitive field. Emile Henry and Le Creuset, rooted in French craftsmanship traditions, offer ceramic and enameled cast iron alternatives that appeal to artisanal and premium home baking audiences seeking superior heat retention and distinctive culinary aesthetics. Kaiser Bakeware, based in Germany, reinforces the market's emphasis on engineered quality, supplying bakeware designed for both home and professional environments. On the industrial and supply-chain side, American Pan and Parrish Magic Line focus on the commercial bakery and stock-pan segment, providing scalable aluminum and coated solutions for high-volume production. China-based Wuxi Hongbei Bakeware Co., Ltd. represents the growing presence of industrial-scale manufacturers capable of delivering custom and stock configurations for bakery operations that prioritize cost efficiency and production flexibility.
This competitive mosaic is neither static nor frictionless. Recent market events underscore the volatility that can ripple through adjacent product categories and influence broader consumer confidence. In February 2026, for instance, regulatory actions escalated a product recall involving certain cake mix varieties due to undeclared allergens, highlighting the critical importance of stringent quality control, transparent labeling, and supply chain traceability for any company operating in the baked goods ecosystem. Although such recalls originate within the mix segment, they send ripple effects across the entire value chain, reinforcing the need for pan manufacturers and distributors to align their quality assurance protocols, packaging integrity, and compliance frameworks with the highest industry standards.
Regulatory Pressures, Input Costs, and the External Environment
Strategic decision-making in the cake pans market cannot be divorced from the external environment in which it operates. Raw material economics, regulatory mandates, and trade policy dynamics all exert direct or indirect pressure on manufacturing costs, pricing strategies, and market access.
Input cost volatility remains a persistent consideration. Global wheat prices, for example, have experienced notable fluctuations, reflecting broader agricultural market conditions that influence the economics of baking at large. While cake pans are not directly derived from agricultural commodities, their demand is closely tied to the overall baking activity of households, bakeries, and foodservice operators. When input costs for core baking ingredients rise or become unpredictable, end-users may adjust purchasing frequency, recipe complexity, or equipment investment cycles. Manufacturers and channel partners must therefore anticipate these demand-side elasticity effects when forecasting volume, planning production runs, and setting price architectures.
Regulatory compliance represents another layer of strategic complexity. Food safety authorities in major markets, including the U.S. FDA, mandate clear labeling of major food allergens such as wheat, eggs, and milk for packaged baked goods. For cottage food operations and small-scale producers, labeling requirements extend to producer identification, product naming, and applicable allergen declarations. Although these mandates primarily target food products rather than cookware, they shape the broader operating environment in which cake pans are purchased, used, and evaluated. Manufacturers that supply professional bakeries or partner with commercial food producers must ensure their product documentation, coating specifications, and material disclosures support rigorous compliance workflows downstream.
Trade policy developments further complicate the landscape. The implementation of broad additional ad valorem import tariffs, beginning at a baseline of 10 percent on goods from a range of trading partners, introduces new cost and sourcing considerations for an industry that relies on international supply chains, cross-border component flows, and globally distributed manufacturing footprints. Companies must evaluate how tariff exposure affects landed costs, supplier diversification strategies, inventory positioning, and final price pass-through to consumers. In this environment, the ability to model tariff scenarios, stress-test margin assumptions, and identify alternative sourcing pathways becomes a core competitive capability rather than a peripheral administrative function.
What the Report Delivers: A Toolkit for Strategic Action
Our Worldwide Cake Pans Market report is structured to move beyond descriptive analysis and toward executive-grade decision support. It is designed to be a practical reference for shaping product roadmaps, refining market entry tactics, optimizing channel strategies, and anticipating competitive responses. The report's scope encompasses, but is not limited to, the following areas of actionable insight:
- Comprehensive market sizing and historical tracking from 2020 through 2025, establishing a validated baseline for assessing growth momentum and structural shifts.
- Forward-looking revenue projections through 2032, enabling scenario planning, target setting, and investment prioritization across the forecast horizon.
- Deep segmentation analysis across material types, sales channels, and geographic regions, revealing where value concentrates, where growth accelerates, and where differentiation is most defensible.
- Competitive profiling of leading manufacturers, including product positioning, brand strategy cues, channel emphasis, and capabilities relevant to commercial and consumer segments.
- Assessment of market concentration dynamics, providing context on the balance of power between dominant incumbents and emerging or niche players.
- Evaluation of external drivers and constraints, including raw material economics, regulatory frameworks, import tariff implications, and consumer behavior trends that influence demand cycles.
- Strategic implications and strategic recommendations tailored to manufacturers, distributors, retail operators, and investors seeking to align their portfolios with the most promising growth vectors.
By integrating quantitative rigor with qualitative industry intelligence, the report equips readers to answer the questions that directly affect enterprise performance: Which segments offer the most favorable risk-adjusted growth? Where should product innovation and material investment be focused? How should channel strategies evolve in response to shifting retail dynamics and digital commerce acceleration? What competitive moves are likely from incumbents and smaller challengers? And how should organizations prepare for regulatory and trade-policy scenarios that could reshape cost structures and market access?
Non-Stick Pans Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window will be defined by organizations that can translate market signals into disciplined execution. As the global cake pans market continues to expand at a measured but meaningful pace, stakeholders face a dual mandate: capture share in high-potential segments while defending against cost pressures, competitive intensification, and external shocks that can erode margin and disrupt planning cycles. Success in this environment requires more than intuition; it requires a structured understanding of market size, growth rate, segmentation patterns, competitor capabilities, and the macro forces shaping the operating terrain.
Our research is built to serve that need. It provides the evidentiary foundation for strategic choices, from long-range capacity planning and product development investment to pricing architecture, channel mix optimization, and market prioritization. It also highlights the operational discipline required to navigate an environment where input costs fluctuate, regulatory expectations intensify, and trade policy introduces new uncertainty into cross-border commerce.
Access the Full Intelligence Suite
This article offers a strategic preview of the landscape, but the complete analytical depth, detailed segmentation breakdowns, granular competitive assessments, and forward-looking scenario analysis reside within the full Worldwide Cake Pans Market report. For executives and analysts who require precise data, comprehensive segmentation detail, and actionable strategic guidance to inform 2026 planning and beyond, the full study is essential.
To explore the complete findings, access detailed market size trajectories, review in-depth competitor profiles, and unlock the strategic recommendations designed to support informed decision-making, we invite you to visit the source webpage and obtain the full report. Equip your organization with the intelligence needed to navigate the market's next phase of growth with clarity, confidence, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Cake Pans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Acute Care EHR Market to Hit $50.57B by 2032, Growing at 6.52% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Acute Care EHR Landscape: Strategic Imperatives for 2026 Decision-Makers
The worldwide acute care electronic health record market stands at a critical inflection point. As health systems allocate multi-year capital budgets and navigate shifting regulatory frameworks, the choice of EHR platform has evolved from an IT procurement decision into a foundational strategic maneuver. Our latest Worldwide Acute Care Electronic Health Recorder Market research synthesizes historical performance, forward-looking projections, and granular competitive intelligence to equip executives with the analytical clarity required for 2026 and beyond.
Acute Care Telemedicine Services Market
This report is designed as a decision-support instrument rather than a static market snapshot. It maps the structural forces shaping procurement cycles, evaluates the competitive positioning of dominant and emerging vendors, and benchmarks operational priorities against real-world spending behavior. The objective is straightforward: translate complex market signals into actionable intelligence for hospital administrators, health system strategists, technology investors, and policy advisors who must justify capital allocation in an environment of compressed margins and accelerated digital transformation.
Market Trajectory and Structural Growth Drivers
The global acute care EHR market has demonstrated consistent expansion over the past half-decade, reflecting the industry-wide imperative to digitize clinical workflows, strengthen interoperability, and support value-based care models. From a 2020 baseline of USD 24,500 million, the market advanced through 2021 at USD 26,878.16 million, reached USD 28,211.83 million in 2022, and climbed to USD 29,500.61 million in 2023. Growth momentum continued as 2024 recorded USD 31,923.36 million, followed by a 2025 valuation of USD 32,500.0 million.
These historical figures establish a clear trajectory of sustained adoption, but the forward-looking data is where strategic planning gains its most practical utility. Our forecast period spans 2026 through 2032, anchored by a compound annual growth rate of 6.52 percent. This growth profile translates to a 2026 estimate of USD 33,762.2 million, progressing to USD 37,576.93 million in 2027, USD 37,960.9 million in 2028, USD 41,469.16 million in 2029, USD 45,333.3 million in 2030, USD 47,227.17 million in 2031, and a projected 2032 valuation of USD 50,570.0 million.
The persistence of this growth curve is not merely a function of technological modernization. It reflects deeper structural pressures: ongoing interoperability mandates, the integration of AI-enabled clinical decision support, heightened cybersecurity requirements, and the financial volatility that forces health systems to optimize operational efficiency without sacrificing care quality. Our forecast methodology isolates these drivers and models their cumulative impact on procurement cycles, upgrade timelines, and platform migration activity across diverse facility profiles.
Capital expenditure patterns confirm this strategic prioritization. Enterprise technology investments, including EHR implementations and upgrades, remain embedded in multi-year capital budgets that routinely reach billions of dollars. At the same time, spending priorities are recalibrating. AI-based clinical technology solutions have emerged as the leading planned technology initiative for health systems at 57 percent for the 2026-2027 horizon, while EHR optimization spending share has shifted to 43 percent. This rebalancing does not diminish the EHR's centrality; rather, it signals a maturation phase in which foundational digital infrastructure must interoperate seamlessly with next-generation clinical tools.
Competitive Landscape and Vendor Positioning
Market concentration remains pronounced, with the top three players commanding 72.5 percent of total market share and the top five collectively holding 84.2 percent. This concentration shapes negotiation leverage, integration roadmaps, and the risk-reward calculus of platform selection. The competitive field is anchored by organizations with distinct operational philosophies, deployment footprints, and target constituencies.
Epic Systems Corporation, headquartered in Verona, Wisconsin, provides a comprehensive acute care EHR platform distinguished by deep inpatient, surgical, emergency department, and enterprise-wide integration functionality. Its dominance in large hospital systems and academic medical centers is reinforced by a strong focus on seamless clinical documentation and interoperability. Epic's market momentum remains significant, having recorded its largest net gain in US acute care EHR market share by adding 176 multispecialty hospitals and nearly 30,000 beds in 2024 decisions. This trajectory underscores the vendor's ability to capture large-scale migrations and consolidate complex enterprise workflows.
Oracle Health, formerly operating under the Cerner brand and now integrated within Oracle's Austin, Texas headquarters, offers the Millennium platform with strong acute care capabilities spanning inpatient, surgical, and emergency department functionality. The platform serves hospitals of varying sizes with an emphasis on cloud infrastructure integration and large-scale deployments. Recent independent analysis positions Oracle Health at a critical juncture, highlighting ongoing product developments in acute care EHR alongside complex partnership dynamics that warrant close monitoring by organizations evaluating long-term vendor stability and roadmap alignment.
Medical Information Technology, Inc., known as MEDITECH, is based in Westwood, Massachusetts and delivers the Expanse platform as a full acute care EHR suited for community hospitals, rural facilities, and smaller organizations. Its value proposition centers on cost-effective inpatient solutions with stable support for 1-200 bed facilities. For health systems seeking predictable total cost of ownership without sacrificing core clinical functionality, MEDITECH's positioning remains a strategically relevant benchmark.
Evident, operating under CPSI in Mobile, Alabama, specializes in TruBridge and Thrive acute care EHR platforms targeted at community hospitals with fewer than 400 beds. Its focus on comprehensive solutions for smaller acute care organizations and affiliated clinics addresses a segment where workflow simplicity, integration with ambulatory networks, and administrative efficiency often outweigh the complexities of enterprise-scale architectures.
Altera Digital Health, formerly known as the Allscripts Hospitals and Large Physician Practice business and based in Chicago, Illinois, provides the Sunrise Enterprise suite for acute care EHR including clinical and financial solutions. The platform targets hospitals and health systems with flexible, open architectures supporting inpatient workflows. Its design philosophy appeals to organizations that prioritize modularity and third-party interoperability within a unified clinical and financial framework.
Veradigm, also headquartered in Chicago and formerly Allscripts, offers ambulatory and select acute care EHR solutions with a focused emphasis on interoperability and integration with third-party applications. It maintains a presence across hospital and practice settings following its strategic divestiture, serving use cases where cross-continuum data exchange and application extensibility are paramount.
Beyond individual vendor profiles, the market exhibits sustained migration activity. Throughout 2025 and into 2026, multiple hospitals and health systems have announced EHR platform changes and migrations in acute care settings. These migrations are rarely purely technical exercises; they are strategic re-alignments driven by cost pressures, workflow dissatisfaction, interoperability gaps, and the desire to future-proof infrastructure against emerging clinical technology requirements.
Operational and Financial Dynamics Shaping Procurement Decisions
Strategic procurement cannot be evaluated in isolation from the financial and operational environment in which it occurs. Total hospital expenses grew 7.5 percent in 2025, a pace more than twice the rate of growth in hospital prices, driven by labor, drugs, and supplies. This expense compression forces executive teams to scrutinize every capital deployment for measurable return on investment, workflow efficiency gains, and risk mitigation potential.
Simultaneously, cybersecurity has become a non-negotiable line item. Hospitals spent roughly USD 30 billion in 2025 on technology and services to protect systems, data, and operations from cyber threats. This expenditure directly intersects with EHR strategy, as clinical platforms operate at the center of protected health information flows, device integrations, and network-dependent care delivery. Procurement decisions increasingly require explicit evaluation of security architecture, vendor incident response capabilities, and alignment with enterprise-wide resilience frameworks.
Regulatory and reimbursement dynamics add further complexity. The Medicare IPPS proposed rule for acute care hospitals revises inpatient prospective payment systems for operating and capital-related costs, influencing how health systems budget for technology investments and evaluate reimbursement alignment. These changes modulate the financial rationale behind platform upgrades, particularly when capital-related cost structures intersect with depreciation schedules, implementation timelines, and long-term total cost of ownership models.
Under these conditions, the decision to standardize on a platform, migrate to a new environment, or optimize an existing deployment becomes a multi-variable optimization problem. Executives must weigh clinical workflow compatibility, interoperability roadmaps, cloud versus on-premise deployment economics, vendor stability, integration readiness for AI-based clinical tools, and the financial implications of migration downtime. Each of these variables carries distinct risk profiles depending on hospital type, facility size, regional regulatory exposure, and existing technology debt.
Depth of Report Coverage and Strategic Application
This market research is structured to support applied decision-making rather than abstract market observation. The analysis integrates historical performance data with forward-looking projections and contextualizes them within the operational realities that govern purchasing behavior. The report examines deployment model dynamics, hospital type segmentation, regional adoption patterns, and competitive concentration to reveal where growth is concentrated and where strategic opportunity lies.
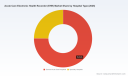
Deployment architecture remains a central axis of evaluation. Cloud-based implementations and on-premise deployments each present distinct governance, cost, scalability, and control trade-offs that influence how health systems structure multi-year technology roadmaps. The relative share of these deployment models provides insight into shifting infrastructure preferences, particularly as organizations balance capital efficiency against data sovereignty, integration complexity, and long-term scalability requirements.
Hospital type segmentation further clarifies demand patterns. General acute care hospitals and specialty hospitals exhibit differentiated clinical workflows, financial structures, and interoperability priorities, which in turn shape platform fit and procurement rationale. Understanding how market value distributes across these facility categories enables more precise targeting of implementation strategies, vendor negotiations, and optimization investments.
Regional analysis adds an additional strategic layer. Geographic variation in regulatory mandates, reimbursement environments, digital maturity, and competitive intensity affects both the pace of adoption and the vendor mix favored in each territory. The report contextualizes these regional dynamics without reducing them to simplistic rankings, instead highlighting how local market structures influence migration patterns, partnership opportunities, and implementation risk.
Competitive monitoring is embedded throughout the analysis. Recent developments indicate that Epic continues to expand its footprint in large-scale acute care environments, Oracle Health is executing product advancements amid partnership complexities that require careful vendor diligence, MEDITECH maintains strong relevance for smaller and community-based settings, Evident addresses niche acute care configurations, and Altera and Veradigm sustain differentiated positions around open-platform flexibility and interoperability-focused integration. These dynamics are evaluated not as static profiles but as evolving strategic postures that affect procurement leverage and long-term vendor reliability.
Strategic Implications for 2026 Planning Cycles
As health systems finalize 2026 capital plans and extend technology roadmaps into the late decade, several strategic implications emerge from the market structure.
- Platform selection must be evaluated against migration risk and total cost of ownership, not only initial functionality. The concentration of market share among leading vendors means that organizations can benefit from mature interoperability networks and broader implementation experience, but they must also assess vendor dependency, contract flexibility, and long-term roadmap alignment.
- AI-enabled clinical technology is becoming the planning anchor for health system innovation. With AI-based clinical solutions leading planned technology initiatives, EHR platforms must demonstrate readiness for integration, data structuring, and workflow augmentation. Optimization spending remains substantial, but its role is increasingly defined by how well the platform supports adjacent clinical intelligence investments.
- Cybersecurity and regulatory alignment are procurement prerequisites, not add-ons. The significant expenditure on cyber protection and the evolving IPPS reimbursement environment mean that security architecture, compliance readiness, and capital cost modeling belong at the center of evaluation frameworks.
- Migration activity is a strategic signal, not merely an operational event. Continued announcements of EHR platform changes reflect structural dissatisfaction, expansion ambitions, and the pursuit of interoperability and workflow efficiency. Organizations monitoring these migrations can extract benchmarks for negotiation, implementation sequencing, and risk mitigation.
- Capital allocation discipline will separate durable strategies from reactive purchases. Expense growth outpacing price growth, combined with multi-year budget commitments, requires executives to justify EHR investments through measurable efficiency gains, reduced rework, improved documentation quality, and enhanced integration with enterprise technology objectives.
Conclusion
The worldwide acute care EHR market is expanding along a defined growth trajectory while simultaneously undergoing strategic recalibration in how platforms are evaluated, integrated, and defended against evolving operational and financial pressures. The convergence of sustained adoption, competitive concentration, migration momentum, cybersecurity imperatives, and AI-centric planning priorities creates a market environment where informed decision-making offers tangible competitive advantage.
Our research provides the depth and structure needed to navigate that environment. It translates historical performance into forward-looking perspective, situates vendor dynamics within broader market concentration patterns, and aligns procurement considerations with real-world financial and regulatory forces. For executives responsible for 2026 capital planning, platform strategy, and long-term digital transformation, the report offers a framework for reducing uncertainty and increasing the strategic precision of technology investment decisions.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
To access the complete segmentation analysis, regional breakdowns, deployment model comparisons, hospital type distributions, competitive intelligence detail, and full forecast tables, we invite you to explore the source page for the complete Worldwide Acute Care Electronic Health Recorder Market research. The full dataset and methodological documentation are available there for teams that require granular intelligence to support executive briefings, vendor evaluations, and capital allocation decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Care Electronic Health Recorder (EHR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Foot Traffic Market Hits $8.62B in 2025, Poised to Reach $26.9B by 2032
By pmarketresearch, 2026-09-16
Unlocking Customer Location Intelligence: Strategic Imperatives for the 2026 Market Landscape
Introduction: The Evolution of Physical-Digital Convergence
The boundary between digital strategy and physical presence has dissolved. In 2026, organizations that operate solely on online engagement metrics while ignoring in-person footfall dynamics are operating with half a map. The Worldwide Foot Traffic and Customer Location Intelligence Solution Market has matured rapidly from a niche analytics supplement into a core infrastructure layer for retail, real estate, transportation, healthcare, and smart city operations. This article serves as an executive preview of our latest market research, designed to illuminate the strategic vectors that will define enterprise decision-making through 2032. Readers seeking granular segmentation matrices, proprietary survey findings, and competitor benchmarking tables are invited to explore the full report via the source portal.
The modern enterprise must answer questions that were once dismissed as anecdotal: Where do consumers originate before visiting a store? How do seasonal mobility shifts alter trade area profitability? Which physical touchpoints deliver measurable conversion lift versus dead weight? Location intelligence answers these questions with precision. It fuses anonymized mobility data, sensor-derived counts, geospatial mapping, and behavioral modeling into operational intelligence that directly informs site selection, staffing allocation, inventory planning, marketing spend optimization, and asset valuation.
Macro Trajectory: Why the Growth Curve Matters for Decision-Makers
The market has demonstrated sustained expansion across the historical observation window and is positioned for an accelerated trajectory in the forthcoming forecast horizon. From a base exceeding four billion USD in 2020, revenue climbed past 8.6 billion USD by 2025, reflecting heightened enterprise demand for actionable proximity insights. This momentum carries forward sharply, with the projected annual growth rate of approximately 15.65 percent driving valuation toward nearly 10.2 billion USD in 2026 and surpassing 26.8 billion USD by 2032.
The implications are clear. Capital is flowing into location intelligence not as an experimental capability but as a structural requirement for competitive resilience. Procurement leaders must evaluate vendor ecosystems with long-term scalability in mind. Strategy teams should anticipate that early-mover advantages in foot traffic analytics will compound as data networks deepen and AI-driven inference models become more sophisticated. Investors and board members need visibility into whether their organization's current data architecture can absorb the kind of continuous, high-frequency spatial insights that the market trajectory implies will become table stakes within half a decade.
Crowd Management Solution Market
Solution Architecture and Technology Interplay
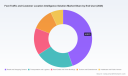
Location intelligence solutions are delivered through a layered stack that combines software and analytics platforms, hardware and sensor systems, and professional and managed services. The software layer typically anchors the value proposition: it ingests multi-source data, normalizes disparate formats, applies machine learning models, and surfaces dashboards that translate raw observations into decision-ready intelligence. Hardware components range from in-store sensors and computer-vision counters to environmental and proximity detection units that feed ground-truth signals into broader platforms. Managed services bridge the gap between tool deployment and business outcomes, offering implementation guidance, custom modeling, and ongoing analytical support.
Technology selection is no longer a binary choice between beacon-based tracking and satellite positioning. Wi-Fi and Bluetooth/BLE frameworks continue to provide accurate micro-level presence detection within controlled environments. GPS and satellite positioning supply macro-mobility context, enabling organizations to understand catchment areas, route behaviors, and regional visitation flows. AI-powered video analytics represent a fast-evolving frontier, converting visual streams into demographic, dwell-time, and pathing insights while raising distinct considerations around privacy-by-design architecture. Infrared and thermal sensor approaches complement these methods where lighting conditions, occlusion, or data governance constraints make optical processing less practical. The sophisticated buyer evaluates not single technologies but the interoperability of heterogeneous signals, seeking platforms that can triangulate insights rather than rely on a single sensing modality.
End-User Demand: How Different Verticals Convert Location Data into Operating Leverage
Foot traffic intelligence is not a monolithic use case. Demand patterns diverge considerably across sectors, each extracting a distinct form of economic value from spatial data.
- Retail and shopping centers use location analytics to optimize store layouts, calibrate promotional calendars, evaluate cannibalization risk, and refine trade area definitions. Site selection teams increasingly treat footfall velocity and visitation composition as non-negotiable inputs for new openings and lease negotiations.
- Transportation and logistics operators leverage movement intelligence to align service frequency with passenger and freight flows, reduce idle capacity, and improve last-mile planning. The discipline of matching supply to actual demand patterns rather than assumed averages is a direct productivity driver.
- Real estate and smart buildings apply occupancy metrics to manage tenant mix, forecast amenity utilization, and enhance property-level operational efficiency. As commercial portfolios adapt to evolving work and consumption habits, asset managers increasingly require visitation evidence to validate pricing and leasing strategies.
- Tourism and entertainment venues utilize flow analytics to manage crowd density, time-entry pacing, and experiential offerings, aligning throughput with guest satisfaction and safety tolerances.
- Healthcare and public venues deploy people counting and zone-level occupancy insights to improve patient flow, staff allocation, and space utilization, especially in environments where congestion directly affects service quality and safety.
What unites these verticals is the realization that spatial behavior is a lagging indicator of past planning assumptions and a leading indicator of future performance. The enterprises that institutionalize location intelligence treat it as an operational thermostat rather than a periodic dashboard.
Competitive Landscape: Differentiated Approaches in a Consolidating Field
The vendor ecosystem spans data aggregators, analytics platform builders, sensor manufacturers, GIS specialists, and managed-services providers. Market concentration remains moderate, meaning that no single vendor dominates the entire value chain, but a cadre of well-capitalized public and private players is actively extending their stack depth and ecosystem reach.
Several archetypes have emerged. Platform-first analytics providers construct multi-source data pipelines and partner networks to deliver visitation trends, trade area modeling, and consumer behavior insights. GIS and spatial analysis specialists contribute foundational mapping, spatial statistics, and site-performance evaluation capabilities that complement mobility datasets. Sensor and in-store analytics vendors focus on ground-truth measurement within physical environments, converting visual or proximity signals into people counts, heatmaps, pathing, and conversion metrics. Data infrastructure and mobility data firms supply anonymized movement records and points-of-interest context that feed third-party platforms. The most competitive vendors increasingly differentiate through ecosystem integrations, privacy-compliant data sourcing, and domain-specific model tuning rather than raw data volume alone.
Recent market activity underscores this orientation toward integration, thought leadership, and product deepening. In early 2026, major platform participants continued to emphasize the bifurcation of retail performance and the need for nuanced consumer behavior interpretation in economic development and commercial strategy forums. Simultaneously, data integrations between foot traffic intelligence providers and commercial real estate platforms have accelerated, reflecting demand for asset- and REIT-level consumer behavior insights that connect physical visitation patterns to valuation, leasing, and asset management workflows. Parallel product enhancements in retail site selection tooling have introduced more rigorous cannibalization rate calculations and trade area overlap modeling, signaling that the market is moving from descriptive footfall reporting to prescriptive optimization.
Regulatory and Structural Dynamics Shaping Deployment Strategy
The commercial upside of location intelligence is inseparable from the regulatory environment in which it operates. Data sovereignty and localization requirements in certain jurisdictions mandate that mobility and location data be stored and processed within national borders, constraining cross-border intelligence architectures and forcing vendors and buyers to design regional data residency strategies. In parallel, cross-jurisdictional legal frameworks such as the U.S. CLOUD Act affect how international enterprises evaluate data-handling practices, particularly when platform providers operate under multiple legal exposures simultaneously. These forces are not peripheral compliance footnotes; they influence vendor selection, contractual data processing terms, and architecture decisions around where analytics workloads run.
Spectrum management policy also intersects with the sensing layer. Ongoing regulatory and technical efforts to improve wireless spectrum sharing and utilization have relevance for the transmission reliability and density of Bluetooth, Wi-Fi, and other proximity sensing modalities that underpin parts of the location intelligence stack. While these developments may appear abstract, they affect real-world signal quality, deployment cost curves, and the long-term robustness of sensor-dependent installations in dense urban and indoor environments.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Forward-looking enterprises are therefore embedding regulatory diligence into procurement cycles. They are asking vendors about data provenance, anonymization standards, retention policies, regional processing options, and the governance audits available to support compliance teams. In this market, trust is a competitive asset, and privacy-preserving design is increasingly a purchasing requirement rather than a desirability factor.
Strategic Implications for Enterprise Decision-Makers in 2026
For executives shaping 2026 plans, the central question is not whether to use location intelligence but how to operationalize it at the right scale and with the right governance.
- Align foot traffic intelligence with core KPIs. Location data should be wired into the metrics that already drive board-level attention: sales per square foot, conversion rates, labor productivity, asset occupancy, site cannibalization, and customer lifetime value. Insights that live in isolated analytics sandboxes do not inform capital allocation.
- Adopt a layered sensing strategy. No single data source captures the full picture. Combining macro-mobility context with in-store or in-venue sensing, and supplementing both with geospatial analytics, produces more resilient inference than any standalone feed.
- Invest in integration before customization. Platforms that connect cleanly to existing CRM, ERP, lease management, and workforce scheduling systems deliver faster time-to-value than bespoke models that require permanent specialized maintenance.
- Treat privacy and compliance as architecture, not add-ons. Evaluate vendors on data sourcing transparency, anonymization rigor, regional processing capability, and auditability. In a market with rising regulatory scrutiny, procurement documentation should reflect these dimensions explicitly.
- Plan for compounding data network effects. As more entities adopt location intelligence, benchmark data, model accuracy, and comparative context improve. Organizations that deploy early and steadily expand usage will benefit from richer baselines and more refined predictive signals than those who defer.
Conclusion: From Market Intelligence to Operational Advantage
The Worldwide Foot Traffic and Customer Location Intelligence Solution Market is moving from rapid expansion to functional maturation. Revenue scales, technology diversification, and ecosystem integration all point toward a market where spatial insight becomes embedded in everyday operational decision-making rather than treated as a specialized analytics project. The strategic winners in 2026 and beyond will be those who translate location intelligence into measurable operating improvements: sharper site selection, more efficient staffing and space utilization, better trade area understanding, and more defensible asset valuation supported by empirical visitation evidence.
This executive overview has outlined the market trajectory, solution architecture, vertical demand patterns, competitive archetypes, and regulatory dynamics that frame the decision environment. It is necessarily a high-level synthesis. The full market research report provides the detailed segmentation analysis, granular segmentation breakdowns, vendor profiling depth, regional dynamics, technology adoption patterns, and forward scenarios required for precise procurement, investment, and strategic planning decisions. Readers seeking that complete intelligence should access the source report to obtain the full dataset, segmentation matrices, and actionable end-user profiles that accompany this analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Solar Laser Drilling Market Hits $692.47M in 2025, Projected to Surpass $1.6B by 2032
By pmarketresearch, 2026-09-16
Unlocking Precision: Strategic Insights into the Worldwide Solar Laser Drilling Market (2026-2032)
Executive Summary: The Imperative for Precision Scaling
The global photovoltaic manufacturing landscape is undergoing a fundamental transformation. As cell efficiencies approach theoretical limits, the burden of performance improvement shifts from material science alone to the precision of manufacturing processes. In this context, laser drilling has evolved from a niche capability into a cornerstone of high-throughput solar cell production. Our latest market research, Worldwide Solar Laser Drilling Market, offers a definitive analysis of this critical sector, providing the intelligence necessary for strategic decision-making in 2026 and beyond.
This study is not merely a collection of statistics; it is a strategic roadmap designed to help stakeholders navigate the convergence of technological innovation, macroeconomic volatility, and shifting regional demands. By synthesizing historical performance with rigorous forecasting, we illuminate the path toward sustainable growth in an industry defined by rapid iteration.
Market Trajectory and Magnitude: A Decade of Acceleration
The financial trajectory of the solar laser drilling sector signals robust confidence in the long-term viability of photovoltaic expansion. We have observed a steady compounding of value over the historical review period, reflecting the industry's transition toward more sophisticated module architectures. Starting from a foundation of approximately $372 million in 2020, the market has scaled significantly to reach an estimated $692 million by 2025. This growth underscores the essential role laser technology plays in meeting global energy targets.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. We anticipate the market to breach the $780 million threshold in 2026, accelerating toward a peak valuation exceeding $1.6 billion by the end of the decade. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 13.66 percent. Such consistent growth indicates that laser drilling is not susceptible to the transient fluctuations affecting broader manufacturing equipment sectors. Instead, it is driven by permanent shifts in cell design requirements, specifically the need for high-precision contact opening and glass processing in double-glass modules.
These figures represent more than just revenue; they reflect the capital intensity required to maintain competitive parity. Manufacturers who fail to integrate advanced laser solutions risk yield penalties and throughput bottlenecks, particularly as wafer thicknesses decrease and cell architectures become more complex. Our research quantifies this investment requirement, allowing CAPEX planners to align their budgets with realistic market demands.
Strategic Segmentation: Technology and Application Drivers
To understand where value is created, one must dissect the market into its core operational components. Our analysis categorizes the landscape by laser type and solar cell technology, revealing distinct pockets of opportunity that require tailored strategic approaches.
Laser Technology Evolution
The market is currently defined by a spectrum of laser technologies, each serving specific process requirements. Nanosecond lasers continue to hold a substantial share of the market, driven by their established role in high-throughput processes such as laser contact opening and dicing. These systems offer a balance of speed and cost-effectiveness that remains vital for high-volume PERC cell production.
However, the frontier of innovation lies in ultrafast processing. Picosecond and femtosecond laser segments are gaining traction as manufacturers seek to minimize thermal damage and improve edge quality in advanced cell designs. The adoption of these technologies is closely tied to the transition toward higher efficiency cell architectures. While nanosecond systems provide the workhorse capacity for current generation manufacturing, ultrafast sources are becoming critical for next-generation prototypes and specialized applications where precision outweighs pure throughput speed. Understanding the cost-benefit analysis of migrating from nanosecond to picosecond or femtosecond sources is a key component of our report, helping engineering leaders justify technology upgrades.
Worldwide Laser Drilling Device Market
Cell Technology Alignment
Market demand is inextricably linked to the prevailing solar cell technologies being deployed globally. PERC cell processing remains a dominant driver of laser drilling demand, particularly for laser contact opening procedures that define cell efficiency. As the industry matures, the volume of PERC production ensures a stable baseline for equipment manufacturers.
Simultaneously, the rise of TOPCon cell processing is reshaping the demand profile. TOPCon architectures require precise laser doping and contact formation steps that differ significantly from PERC workflows. Our research details the specific laser process requirements for TOPCon, enabling equipment suppliers to tailor their solutions and manufacturers to optimize their line configurations. Furthermore, the emerging sector of IBC and next-generation cells presents high-value opportunities. Although currently smaller in volume, these technologies demand the highest levels of precision, creating a premium market segment for specialized laser solutions that can handle complex back-contact structures.
Regional Dynamics and Supply Chain Realities
Geographic distribution of demand is another critical vector for strategic planning. The Asia Pacific region continues to exhibit the strongest gravitational pull on market volume, reflecting its status as the global hub for solar manufacturing capacity. The concentration of production facilities in this region means that logistics, local support, and regional pricing strategies are paramount for equipment providers.
Europe and North America represent mature markets with distinct characteristics. In these regions, demand is often driven by high-value niche applications, R&D infrastructure, and specific regulatory environments regarding manufacturing localization. The Rest of World segment, while smaller in current volume, holds latent potential as emerging economies develop their own photovoltaic supply chains. Our report analyzes the risk and opportunity associated with each region without relying on simplistic percentage splits, focusing instead on the qualitative drivers such as local content requirements, trade policies, and infrastructure development that dictate regional growth.
Worldwide Solar Laser Drilling Market
Competitive Landscape: Navigating a Concentrated Ecosystem
The solar laser drilling market is characterized by a moderate-to-high level of concentration. With the top three players accounting for over 40 percent of the market and the top five capturing nearly 60 percent, barriers to entry remain significant. Success in this environment requires not only technological superiority but also strong channel partnerships and localized service capabilities.
Leading equipment manufacturers such as 3D-Micromac AG have entrenched themselves by providing high-throughput micromachining systems tailored for photovoltaics, including specialized solutions for laser contact opening and thermal laser separation. Their focus on process integration demonstrates how vendors are moving beyond selling hardware to offering complete process solutions. Similarly, industrial giants like TRUMPF leverage their broad laser portfolio to support high-efficiency cell production, benefiting from brand trust and extensive application engineering support.
In the source material segment, companies like Coherent Corp. and IPG Photonics Corporation provide the foundational laser sources that enable precision drilling and structuring. Their competitive position depends on wavelength performance, reliability, and total cost of ownership. Meanwhile, specialized players like Laserax and Novanta Photonics focus on specific niches such as laser cleaning, material removal, and beam delivery systems, carving out defensible positions through deep application expertise.
Regional specialists also play a crucial role. Han's Laser Technology Industry Group Co., Ltd. addresses the specific needs of double-glass modules with high-precision glass drilling machines, capitalizing on the rising demand for photovoltaic back glass processing. ScanLAB GmbH contributes enabling scan systems that facilitate back-side contacts in advanced designs like Metal Wrap-Through and Emitter Wrap-Through. Other entities such as Rache Corp and Laserod Technologies round out the ecosystem by offering solutions for cutting, welding, scribing, and ablation processes that complement primary drilling applications.
Recent developments highlight the dynamism of this competitive field. For instance, advancements announced in late 2025 by BY Photonics demonstrated multi-dimensional breakthroughs in laser glass drilling, achieving significant reductions in drilling time with enhanced chipping control. These technical milestones set new benchmarks that competitors must match. Conversely, market disclosures from early 2026 by companies like LPKF Laser & Electronics SE reveal the impact of macroeconomic headwinds, including investment caution attributed to tariff policy uncertainties. Such reports underscore the importance of agility and long-term technology roadmapping, as some players pivot toward emerging opportunities like perovskite solar technology to leverage existing laser expertise.
Market Dynamics: Headwinds, Tailwinds, and Technological Transitions
The operational environment for solar laser drilling is shaped by a complex interplay of regulatory, technological, and demand-side factors. A primary tailwind is the increasing adoption of double-glass photovoltaic modules. This structural shift drives sustained demand for drilled back glass, necessitating high-precision, low-cost laser drilling capabilities. As module designs evolve to enhance durability and bifacial performance, the processing requirements for glass become more stringent, favoring vendors who can deliver speed without compromising integrity.
On the technology front, processes like laser contact opening and thermal laser separation are now established standards for high-efficiency PERC cells and cell cutting into half or shingle formats. These processes maximize throughput and yield, making them indispensable for large-scale production. However, the industry is also witnessing a technological shift toward perovskite coatings. This transition creates a dual dynamic: it currently holds back some immediate investments due to uncertainty and the need for new processing protocols, yet it offers long-term opportunities for laser processing specialists who can adapt their technology to handle perovskite layers and hybrid architectures.
Macroeconomic factors also exert pressure. Global investment caution observed in the first half of 2025, partly linked to uncertainties surrounding trade policy and tariffs, led to postponed orders in certain regions. This environment demands that suppliers diversify their customer base and offer flexible financing or leasing models to mitigate customer risk. Furthermore, the push for localization in key markets may alter supply chain configurations, favoring vendors with manufacturing footprints aligned to end-market production hubs.
The Strategic Value of Our Research for 2026 Decision-Making
In a market moving at the speed of technological innovation, information latency is a competitive disadvantage. Our Worldwide Solar Laser Drilling Market report is designed to eliminate this lag. For 2026, strategic planners face a unique set of challenges: balancing CAPEX against uncertain demand cycles, selecting the right laser technology mix for evolving cell architectures, and positioning for emerging segments like perovskites without neglecting the cash flow from established PERC and TOPCon lines.
This report provides the granularity needed to address these challenges. It goes beyond top-line numbers to offer actionable insights on process requirements, regional supply chain nuances, and competitive benchmarking. We analyze the cost structures associated with different laser types, the yield implications of process choices, and the service models that determine long-term customer satisfaction. By integrating these insights, executives can make informed decisions about product portfolio development, market entry strategies, and partnership opportunities.
For equipment manufacturers, the report highlights gaps in the market where specialized solutions can command premium pricing. For component suppliers, it identifies the leading manufacturers whose capacity expansion signals future demand for laser sources and optics. For investors, it profiles the companies with the technological agility and financial resilience to thrive amidst regulatory shifts and technological transitions.
Conclusion: Positioning for Sustainable Growth
The Worldwide Solar Laser Drilling Market stands at the intersection of energy transition imperatives and high-tech manufacturing capabilities. The projected growth to nearly $1.7 billion by 2032 reflects the critical role that precision laser processing plays in unlocking higher efficiencies and lower levelized costs of energy. However, capturing this growth requires more than just capital investment; it requires strategic clarity.
Stakeholders must navigate a landscape where established processes coexist with disruptive technologies, where regional dynamics influence procurement decisions, and where competitive concentration demands differentiation. Our comprehensive analysis equips you with the intelligence to navigate these complexities. By understanding the deep drivers of demand, the capabilities of key competitors, and the operational realities of cell production, you can align your strategy with the trajectory of the market.
We invite you to explore the full depth of our findings. The complete report contains detailed segmentation data, proprietary forecasts, and extensive company profiles that provide the full picture necessary for high-stakes decision-making. In the solar industry, the margin for error is shrinking, and the value of accurate intelligence has never been higher. Secure your strategic advantage with the insights found in our Worldwide Solar Laser Drilling Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Telescopic Cylinder Market to Hit $3.1B by 2032, CAGR 5.12%
By pmarketresearch, 2026-09-16
Navigating the Future of Motion Control: Why the 2026 Telescopic Cylinder Market Demands Strategic Clarity
In the rapidly evolving landscape of industrial hydraulics, telescopic cylinders remain a critical enabler of motion control across heavy-duty sectors. From construction machinery operating in space-constrained urban environments to agricultural equipment demanding reliable long-stroke performance, these components bridge the gap between compact retracted lengths and extended operational reach. As we move into 2026, understanding the trajectory of this market is no longer optional for executives and strategic planners. It is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
This article introduces our latest comprehensive research release, the Worldwide Telescopic Cylinder Market study, which provides decision-makers with the granular intelligence needed to navigate a sector undergoing steady structural growth, shifting cost dynamics, and intensifying competitive maneuvering. Below, we outline the strategic rationale behind this analysis, preview the depth of coverage within the report, and explain how the findings can directly inform enterprise decisions throughout the 2026 to 2032 forecast horizon.
The Macro Trajectory: Sustained Growth Embedded in Infrastructure and Industrial Expansion
The telescopic cylinder market has demonstrated a consistent pattern of expansion over the past half-decade, driven by long-term investments in construction, material handling, and agricultural mechanization. Historical data from 2020 through 2025 reveals a revenue base that grew from approximately 1,725 million USD to 2,185 million USD, reflecting both post-pandemic industrial recovery and the compounding effect of sustained capital expenditure in mobile and stationary hydraulic systems. The year 2024 marked a notable inflection point, with market revenue reaching 2,149 million USD, before stabilizing at 2,185 million USD in 2025 as supply chain normalization and raw material price volatility settled into a new equilibrium.
Looking forward, our base forecast projects the global market to reach 2,299 million USD in 2026, representing a measured acceleration as manufacturing output scales and demand from key end-use verticals stabilizes. The growth momentum continues through the forecast window, with the market anticipated to expand to 2,527 million USD by 2027, 2,536 million USD by 2028, and 2,614 million USD by 2029. By 2030, revenue is projected to approach 2,799 million USD, ultimately reaching an estimated 3,100 million USD by 2032. This progression translates to a compound annual growth rate of 5.12 percent across the 2026 to 2032 period, signaling a market characterized by steady, compounding expansion rather than episodic spikes.
For strategic planners, this trajectory carries important implications. A CAGR of this magnitude suggests that demand will reliably track broader industrial activity, but the path to capturing that growth will depend on product differentiation, regional supply chain optimization, and the ability to hedge against input cost volatility. The forecast window also highlights the need to plan for multi-year capacity decisions, supplier diversification, and customer segment prioritization well before market conditions shift.
Segmentation Intelligence: How Type, Application, and Geography Shape Competitiveness
Few market analyses deliver as much actionable value as a rigorous segmentation breakdown. Our research dissects the worldwide telescopic cylinder market along three primary axes: product type, application vertical, and geographic region. Rather than presenting surface-level totals, the report maps how revenue distributes across these segments and what that distribution means for pricing power, production prioritization, and channel strategy.
From a product standpoint, the single-acting and double-acting categories serve distinctly different operational profiles. Single-acting designs continue to dominate in terms of absolute market share, favored for their structural simplicity, reduced maintenance burden, and suitability for applications where gravity or external loads assist retraction. Double-acting variants, while representing a smaller share of total revenue, command strategic importance in scenarios requiring controlled extension and retraction under variable load conditions, making them essential for advanced machinery architectures and precision actuation requirements.
The application landscape further illustrates the diversity of demand drivers. Construction and mining remain the largest application vertical, leveraging telescopic cylinders for dump bodies, excavator booms, and heavy lifting frameworks that must operate under extreme duty cycles. Material handling represents the next major pillar, where telescopic designs are integral to lifts, platforms, and hydraulic stacking systems that require reliable extension under repeated load cycles. Agriculture follows as a significant consumer, with telescopic cylinders deployed in spray booms, seeding equipment, and harvesting platforms where long reach and field durability are non-negotiable. Aviation and other specialized segments round out the demand mix, utilizing high-reliability designs for aircraft servicing platforms and niche industrial applications that prize precision and customized performance envelopes.
Regionally, the report examines how market maturity, industrial policy, and infrastructure investment patterns create distinct competitive arenas. Asia Pacific stands out as the largest revenue-generating region, reflecting the concentration of manufacturing activity, urban construction density, and broad-based agricultural mechanization. North America and Europe follow as mature, high-value markets where performance specifications, compliance standards, and customization requirements shape procurement decisions. Latin America and the Middle East and Africa collectively represent smaller but strategically relevant demand pools, often driven by resource extraction, infrastructure upgrades, and selective industrial modernization projects. While absolute segment values and regional splits are fully disaggregated within the full report, the strategic takeaway is clear: geographic diversification, localized support capabilities, and segment-specific engineering investments will separate market leaders from the rest of the field.
Competitive Landscape: Convergence, Customization, and the Battle for Specialization
The telescopic cylinder market is populated by a mix of global hydraulic powerhouses, specialized mid-tier manufacturers, and regional specialists that compete on engineering depth, lead time, and application-specific customization. Our research profiles a broad set of key companies, mapping their headquarters, product capabilities, and strategic positioning to help readers understand who competes where, and why.
Parker Hannifin Corporation, based in Cleveland, Ohio, remains a defining presence in the space, offering both single-acting and double-acting telescopic hydraulic cylinders through product lines such as its Series SAT. The company serves a wide spectrum of end markets, including truck, mining, material handling, refuse, construction, and industrial sectors, delivering standard and custom solutions that reflect its scale and engineering breadth. In mid-2025, Parker Hannifin expanded its smart cylinder portfolio with new IoT-enabled actuators featuring sensor-integrated rods and advanced sealing systems, innovations that are directly applicable to telescopic designs intended for harsh environments. This move signals a broader industry trend toward intelligent actuation, where embedded sensing, predictive maintenance capabilities, and higher reliability standards are becoming competitive differentiators rather than optional enhancements.
Bosch Rexroth AG, headquartered in Lohr am Main, Germany, provides telescopic cylinders as part of its broader hydraulic cylinder portfolio, with a pronounced focus on industrial, mobile, and heavy-duty applications. Its emphasis on smart solutions and large-bore capability positions it well for customers who require integrated system-level performance rather than isolated component procurement. Eaton Corporation, based in Dublin, Ireland, manufactures telescopic cylinders within its hydraulics division and serves mobile equipment, construction, and industrial sectors, reinforcing the importance of global supply footprints and cross-division engineering synergies in a market where application support and service networks influence purchasing decisions.
HYDAC International GmbH, located in Sulzbach, Germany, supplies telescopic hydraulic cylinders for various industrial and mobile hydraulic systems, adding to the European engineering presence that values precision, filtration integration, and system reliability. On the North American side, Mailhot Industries, based in Saint-Jacques, Quebec, has established itself as a long-standing leader in hydraulic telescopic cylinders since 1956, specializing in reliable, durable nitrided telescopic cylinders engineered for harsh and extreme conditions. Its historical depth and reputation for ruggedness underscore the enduring premium placed on proven performance in demanding duty cycles.
Other notable participants illustrate the breadth of specialization available to buyers. HSI Corporation, headquartered in Pekin, Illinois, focuses on custom single and double-acting multi-stage telescopic cylinders with large bore capabilities designed for precise application fit. Custom Hoist, Inc., in Huron, Ohio, produces telescopic cylinders widely used in dump trucks and heavy-duty applications, with multiple stage models stocked by distributors to support rapid deployment requirements. JARP Industries, based in the United States, manufactures custom hydraulic cylinder solutions including telescopic designs and operates as an acquired entity within the Mailhot Industries ecosystem, highlighting the consolidation dynamics that continue to reshape the competitive map. Texas Hydraulics, Inc., in Temple, Texas, offers rugged high-duty-cycle cylinders including telescopic and piggyback designs for demanding mobile equipment, while Aggressive Hydraulics, in Cedar, Minnesota, concentrates on fully custom-engineered telescopic hydraulic cylinders for agriculture, mining, and other specialized applications. In Asia, Yancheng Haite Machinery Technology Co., Ltd., in Yancheng, China, specializes in customizable telescopic hydraulic cylinders for global markets, and Wipro Enterprises, in Bangalore, India, produces hydraulic cylinders including telescopic models for construction and industrial use. Jiangsu Hengli Hydraulic Co., Ltd., also based in China, manufactures hydraulic cylinders with telescopic offerings for mobile and industrial equipment, reflecting the growing role of Asian manufacturers in both domestic and export-facing supply chains.
Collectively, these companies demonstrate that the competitive landscape is not a monolith. Market leadership is often defined by the ability to combine scale with specialization, standard products with custom engineering, and regional responsiveness with global manufacturing consistency. Our report examines concentration dynamics within the sector, noting that the top three players account for approximately 38.45 percent of market revenue, while the top five represent about 52.6 percent. This level of concentration suggests a market where scale advantages, brand recognition, and established distribution relationships matter, but where meaningful differentiation remains possible for firms that deliver superior application engineering, faster customization cycles, and robust quality assurance.
Industry Dynamics: Cost Pressures, Standards, and the Urban Construction Imperative
Beyond segment structures and competitor maps, the market environment itself is shaped by forces that directly affect margins, lead times, and product strategy. Raw material economics sit at the center of these dynamics. Steel constitutes nearly half of a hydraulic cylinder's production cost, and price fluctuations in high-grade steel and aluminum have a direct bearing on manufacturing margins. Dependence on volatile raw material prices has become a persistent challenge for telescopic cylinder producers, influencing not only unit economics but also final product pricing strategies, inventory planning, and the timing of long-term customer contracts.
Regulatory and trade dynamics add another layer of complexity. Tariffs on imported steel tubes, precision rods, seals, and machining components have increased production costs and extended lead times for manufacturers operating in North America and Europe. For companies that rely on global sourcing footprints, these trade-related frictions require careful supplier diversification, regional inventory buffering, and strategic negotiations with downstream customers to share or absorb cost pressures. In a market where customization cycles and application-specific engineering extend development timelines, even modest increases in component costs or delivery delays can erode profitability and weaken competitive responsiveness.
At the same time, the functional advantages of telescopic cylinders continue to reinforce demand in specific operating environments. Urban construction, in particular, favors telescopic designs because they deliver long strokes in compact retracted lengths required by space-constrained machinery. As cities intensify infrastructure development and equipment must navigate narrower job sites, elevators, and confined staging areas, the ability to achieve extended reach without sacrificing maneuverability becomes a decisive operational benefit. This demand driver is not merely a technical preference; it shapes procurement priorities, influences machinery design requirements, and reinforces the strategic value of manufacturers who can reliably deliver long-stroke performance in rugged, compact form factors.
Quality standards further define the market's baseline expectations. ISO 9001 certification serves as the foundational benchmark for quality in telescopic hydraulic cylinder manufacturing, and competitive differentiation increasingly depends on what lies beyond that baseline: advanced sealing systems, nitrided surface treatments, sensor integration, and application-specific validation. Recent industry activity reflects this evolution. For example, Hydreco Hydraulics showcased customized hydraulic cylinder solutions, including those for heavy-duty applications, at Bauma 2025 in Munich, illustrating how trade-show exposure and technical demonstrations continue to influence buyer expectations and supplier positioning across the heavy equipment ecosystem.
Worldwide Telescopic Cylinder Market
What the Report Delivers: Building a Decision-Ready Intelligence Foundation
The Worldwide Telescopic Cylinder Market study is designed to move beyond high-level forecasts and equip strategic, commercial, and operational leaders with the specific intelligence required to act. The report includes a detailed market overview anchored to a base year of 2025, with historical analysis spanning 2020 through 2025 and a forecast period extending from 2026 through 2032. All monetary values are presented in USD millions, providing a consistent framework for comparing revenue evolution, growth rates, and segment contributions across time.
Readers will find a structured segmentation analysis by region, product type, and application, with revenue distributions and strategic interpretations that support portfolio planning, capacity allocation, and market-entry evaluation. The competitive landscape section offers detailed company profiles, outlining headquarters, product offerings, application focus, and recent developments for leading participants. This includes coverage of product launches, trade-show activity, and other milestones that reveal how competitors are adjusting their portfolios in response to market conditions and technological expectations.
The research also integrates supply-side and demand-side dynamics, including raw material cost sensitivity, trade and tariff impacts, standards and certification baselines, and macro-level application drivers such as space-constrained urban construction. These insights are presented not as isolated facts but as interconnected forces that affect pricing, sourcing, product design, and market timing. The report further examines market concentration and competitive structure, enabling readers to assess the balance between scale-driven incumbents and specialized challengers, as well as the strategic implications of consolidation and portfolio expansion.
Strategic Value for 2026 Decision-Making
For executives planning 2026 initiatives, this research serves as a decision-support framework across multiple business functions. Commercial leaders can use the segmentation and application data to prioritize high-value verticals, tailor value propositions to specific end-use requirements, and identify where customization capabilities can command premium positioning. Operations and supply chain teams can integrate raw material sensitivity, tariff exposure, and regional cost structures into sourcing strategies, inventory planning, and contract terms that protect margin while maintaining delivery reliability. Product and engineering teams can align development priorities with the market's emphasis on long-stroke compact designs, durability for harsh environments, and the growing importance of embedded sensing and intelligent actuation features.
Corporate development and strategy functions will also benefit from the competitive mapping and concentration analysis. Understanding which players hold scale advantages, which specialize in rugged or custom designs, and how recent product and trade-show developments are reshaping buyer expectations can inform partnership considerations, geographic expansion plans, and portfolio gap analysis. In a market where the top five companies account for slightly more than half of total revenue, there remains meaningful room for firms that can combine dependable standard offerings with differentiated custom engineering and application-specific support.
Importantly, the study is structured to support both near-term tactical decisions and longer-term capital planning. The 2026 to 2032 forecast horizon gives leaders a multi-year view of expected market expansion, enabling more disciplined investment timing, scenario planning for demand fluctuations, and alignment of manufacturing or service capacity with projected revenue growth. The inclusion of historical performance from 2020 through 2025 further strengthens the analytical foundation by contextualizing current market size within a recent period of disruption, recovery, and recalibration.
Access the Full Intelligence
The market overview, segmentation logic, competitive analysis, and industry dynamics described here reflect only a portion of what the full report offers. Core regional splits, application-level revenue distribution, type-level breakdowns, detailed company profiles, and the complete multi-year forecast are presented in full within the study to support precise quantification and scenario modeling. Readers seeking the granular data required for budget planning, market-entry analysis, supply chain optimization, or competitive benchmarking will find the complete dataset essential.
Telescopic Jack Market
To explore the full Worldwide Telescopic Cylinder Market research and access the underlying figures, segmentation tables, and company-level intelligence in their entirety, visit the source page for the complete report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Telescopic Cylinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Medicine Packaging Adhesive Market to Hit $2.58B by 2032, Growing at 6.68% CAGR
By pmarketresearch, 2026-09-16
Navigating the Future of Medicine Packaging Adhesives: Strategic Insights from the 2026 Global Market Intelligence
By the PW Consulting Strategic Advisory Team
The global pharmaceutical industry stands at a critical intersection of innovation, regulatory complexity, and sustainability imperatives. As drug delivery systems evolve and consumer expectations around safety shift, the adhesives that hold medical packaging together are no longer mere afterthoughts. They are enablers of compliance, guardians of product integrity, and increasingly, focal points for environmental stewardship. In this context, our newly released Worldwide Medicine Packaging Adhesive Market report arrives at a decisive moment for strategic planning. Anchored in historical performance from 2020 through 2025 and projecting forward across the 2026-2032 forecast horizon, this intelligence is engineered to convert market ambiguity into executable strategy.
For executives navigating capital allocation, supply chain partnerships, or product development roadmaps in 2026, the adhesive layer represents a high-leverage decision point. Understanding where value is accumulating, which material technologies are gaining favor, and how regulatory waves are reshaping compliance pathways is no longer optional. This market analysis does not simply chart revenue trajectories. It dissects the operational realities, competitive maneuvers, and substitution dynamics that will separate resilient organizations from those caught flat-footed as the decade unfolds.
A Market Expanding Beyond Steady Growth
The overall market has demonstrated consistent expansion over the historical window, reflecting the compounding influence of chronic disease prevalence, heightened cold-chain and sterile packaging requirements, and broader distribution footprints across emerging and developed economies. From a baseline exceeding $1.18 billion in 2020, the sector has progressed through successive annual increments, reaching approximately $1.64 billion by 2025. Moving into the forecast period, the trajectory continues its upward course, with the market projected to surpass the $1.77 billion mark in 2026 and climb toward roughly $2.58 billion by 2032. The compound annual growth rate across this entire forecast horizon rests at 6.68 percent, signaling durable demand rather than a temporary surge.
This momentum, however, does not distribute evenly across all technology families, application formats, or geographic corridors. The aggregate figures mask meaningful divergence in regional maturity, material substitution cycles, and application-specific performance thresholds. Decision-makers must look beyond the headline trajectory to understand where procurement flexibility, regulatory headwinds, and performance trade-offs are actively reshaping purchasing behavior. Our full study decodes these divergences with granular segmentation detail, enabling teams to benchmark their exposure against the pockets of highest volumetric growth and the segments facing the steepest margin pressure.
Core Components and Actionable Intelligence Within the Report
This publication is structured for immediate enterprise application rather than passive review. Each section has been designed to feed directly into sourcing strategy, product architecture, and risk mitigation workflows. Below is a structured overview of the operational content that decision-makers can deploy once they access the full dataset.
- Technology Landscape Evaluation: A detailed comparison of water-based, hot melt, solvent-based, UV-cured, and other adhesive variants, examining cure speeds, substrate compatibility, regulatory alignment, and total cost of ownership across high-speed packaging environments.
- Application-Specific Demand Mapping: In-depth coverage of blister packaging, flexible packaging, labels and tapes, and bottles and containers, including format shift trends, tamper-evident requirements, and performance sensitivities tied to pharmaceutical product classes.
- Regional Opportunity and Compliance Frameworks: A geographically segmented view that pairs demand concentration with local regulatory trajectories, enabling multi-market procurement strategies that balance cost efficiency against jurisdictional requirements.
- Competitive Positioning and Share Dynamics: Analysis of concentration patterns and strategic posturing among leading suppliers, including product roadmap signals, capacity investments, and partnership or acquisition behaviors that indicate where the market is heading.
- Raw Material Sensitivity and Margin Risk: An exploration of input price volatility, particularly around petrochemical-derived acrylics, synthetic rubbers, and tackifying resins, alongside mitigations such as formulation diversification, contract structuring, and dual-sourcing architectures.
- Regulatory and Sustainability Scenario Planning: Practical guidance on navigating FDA food-contact provisions, EMA-aligned European requirements, and the evolving patchwork of Extended Producer Responsibility laws, including considerations for exemptions, fee modulation, and recycled-content expectations.
- Strategic Recommendations and Growth Playbooks: Actionable pathways for adhesive manufacturers seeking to expand their pharmaceutical footprint, as well as for pharmaceutical packaging buyers evaluating supplier consolidation, qualification timelines, and future-proofing against regulatory change.
Each of these modules is supported by proprietary data cuts and forward-looking scenario analysis. The complete segmentation breakdowns, regional revenue detail, application share distributions, and concentration metrics are reserved for the full report, ensuring that only clients with access to the complete intelligence can operationalize the numbers at the level required for board-level planning.
The Competitive Arena: Leaders Shaping the Adhesive Ecosystem
Market concentration offers a clear signal of where influence is currently consolidated. The sector exhibits a moderate-but-firm leading position among top suppliers, with the three largest players holding roughly 38.45 percent combined share and the top five reaching approximately 52.1 percent. This concentration does not indicate a closed door for disruptors; rather, it highlights the premium placed on validated pharmaceutical-grade performance, regulatory documentation, and high-speed line compatibility. The leaders profiled in this research demonstrate how targeted formulation engineering and application-specific credentialing can sustain both volume growth and pricing resilience.
Worldwide Medicine Packaging Adhesive Market
Henkel AG & Co. KGaA has reinforced its position through hot melt systems engineered for high-speed pharmaceutical packaging lines, including carton-closing solutions and tamper-evident bonding formulations designed for difficult substrates. Recent activity underscores a continued push into faster curing and regulatory-aligned technologies, including LED-curable lines intended to improve throughput and compliance in device and packaging assembly. H.B. Fuller Company contributes medical-grade adhesive portfolios tailored to pharmaceutical surfaces and flexible medicine packaging, with biocompatible options that address bonding requirements across overwraps and specialty formats. 3M Company continues to supply packaging adhesives and hot melt solutions that support structural bonding and labeling needs across pharmaceutical applications. Arkema S.A., through its Bostik division, develops laminating adhesives and hot melt platforms optimized for medical and pharmaceutical packaging, with particular emphasis on flexible structures and high-barrier configurations. Avery Dennison Corporation extends its pressure-sensitive materials expertise into pharmaceutical labeling and secure packaging identification, supporting closure integrity and traceability requirements.
Dow Inc. rounds out the broader technology base with laminating adhesives and heat-sealable coatings designed for medicine blister and flexible packaging architectures. Alongside these global players, more specialized or regionally focused contributors such as artimelt AG, Jowat SE, Capital Adhesives, and BC Adhesives illustrate how product focus, line-speed compatibility, and tamper-evident or medical-grade credentials can create defensible niches even within a moderately concentrated market. artimelt AG, for example, has built meaningful relevance around hot melt solutions for tablet blister packs, security pouches, and tamper-proof labels. Jowat SE has emphasized formulations applicable to carton closing and pharmaceutical packaging line environments, while Capital Adhesives and BC Adhesives underscore the importance of supply continuity and medical-grade tamper-evident solutions for carton and overall packaging assemblies.
Recent corporate activity further illustrates the direction of travel. In late 2025, Henkel introduced LED-curable adhesives for medical applications with an emphasis on fast curing and regulatory compliance, reinforcing a shift toward process efficiency and precision bonding. That same year, Henkel Adhesive Technologies highlighted the TECHNOMELT SUPRA PRO 301 PLUS hot melt adhesive for pharmaceutical packaging, connecting tamper-evident bonding with sustainability objectives on high-speed lines. At the start of 2026, Dymax Corporation exhibited light-curable, CMR- and TPO-free adhesives for medical device assembly at MD&M West, drawing attention to low-risk formulation strategies in precision bonding for pharmaceutical packaging components. These moves collectively point toward a sector where regulatory confidence, curing efficiency, and formulation clarity are becoming competitive differentiators rather than table-stakes features.
Market Dynamics: Regulations, Materials, and Substitution Pressures
No strategic plan for this market can ignore the regulatory environment. Across multiple U.S. states, Extended Producer Responsibility frameworks for packaging have been implemented or passed, requiring producers to fund recycling programs, establish recycled-content minimums, and adopt fee structures that reward recyclability and post-consumer content. At the same time, several of these programs exempt certain pharmaceutical and medical packaging or products due to patient safety considerations, federal oversight, and regulatory duplication concerns. The practical implication for adhesive decision-makers is a bifurcated landscape: in some corridors, packaging producers face escalating recycling and content obligations; in others, medical and pharmaceutical exemptions create more stable compliance paths, but still demand rigorous documentation and safety alignment. Understanding where exemption boundaries sit and how fee modulation could evolve is essential for multi-state packaging strategies.
On the materials side, pressure-sensitive adhesives commonly depend on acrylic polymers supplied as aqueous emulsions, alongside synthetic rubber and tackifying resins such as hydrogenated hydrocarbon resins derived from petrochemical sources. This composition links performance, cost, and compliance directly to upstream volatility. Raw material pricing for these components remains sensitive to oil market fluctuations and monomer supply dynamics, meaning procurement teams cannot rely on static cost assumptions when modeling margins or negotiating long-term supply agreements. The full report incorporates scenario-based sensitivity views that connect input volatility to formulation choices, supplier diversification, and contract structures, enabling risk teams to stress-test sourcing plans rather than react after prices move.
Regulatory coherence across jurisdictions also remains a central concern. Pharmaceutical packaging adhesives and associated materials must align with FDA food-contact adhesive provisions under 21 CFR 175.105 and EMA-oriented European food-contact expectations under Regulation (EC) No 1935/2004 to support safety in medicine packaging applications. Even as exemptions exist in certain packaging EPR regimes, adhesive suppliers and packaging converters still need robust compliance documentation and formulation controls to satisfy customer audits, labeling integrity requirements, and health-safety expectations. This dual pressure of raw material volatility and regulatory documentation creates a market where formulation transparency and supplier credibility increasingly determine vendor selection.
Worldwide Powder Adhesive Market
Strategic Priorities for 2026 Decision-Making
As organizations prepare for the 2026 operating environment, several strategic imperatives emerge from the interplay of growth, concentration, regulation, and material risk.
- Align adhesive selection with line-speed realities and format performance: Prioritize formulations that can withstand high-speed pharmaceutical packaging operations without sacrificing tamper-evident integrity or substrate compatibility.
- Audit regulatory exposure across packaging corridors: Map where pharmaceutical or medical packaging exemptions apply, where recycled-content and EPR obligations intensify, and how fee structures could influence total packaging cost in different regions.
- Quantify raw material exposure early: Treat petrochemical-driven price variability as a planning variable, not an exception, by testing dual-sourcing options, formulation alternatives, and contract mechanisms before disruption arrives.
- Evaluate supplier concentration strategically: Recognize that market leadership is concentrated, but not prohibitive. Use detailed share and capability data to decide when to consolidate for validation efficiency and when to diversify to preserve continuity and negotiation leverage.
- Plan for curing and sustainability differentiation: Track product launches that emphasize fast curing, regulatory-aligned formulations, and lower-risk ingredient profiles, as these are becoming signals of where the market is heading beyond incremental performance gains.
The value of this market intelligence lies in its ability to connect these imperatives to specific, decision-ready data rather than broad narrative. Full regional breakdowns, application share distributions, technology revenue detail, and concentration metrics are intentionally reserved for the complete report so that only engaged stakeholders gain access to the numbers needed for board-level planning, sourcing review, and product roadmap decisions.
Accessing the Complete Intelligence
The Worldwide Medicine Packaging Adhesive Market study is designed to function as a decision-support asset rather than a static overview. It provides the segmentation depth, competitive profiling, regulatory context, and scenario framing necessary to transform market growth into a structured advantage. The summary presented here offers a credible window into the scope and rigor of the analysis while preserving the core segment data that makes the full publication actionable.
For executives seeking regional revenue clarity, application-specific demand splits, technology-level revenue comparisons, and detailed supplier positioning, the complete report delivers the missing pieces. These elements are built to support sourcing strategy, market entry evaluation, competitive benchmarking, and regulatory-aligned packaging planning. The full dataset can be accessed through the project page, where the complete segmentation, forecast tables, and company profiles are available for immediate operational use.
In a market increasingly shaped by compliance calibration, material volatility, and formulation differentiation, timely access to precise segment intelligence can determine whether a team responds reactively or plans proactively. The detailed figures and strategic readouts within the full analysis are intended to give decision-makers exactly that advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Medicine Packaging Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Glycopeptide Antibiotics Market to Reach $2.72B by 2032 at 4.6% CAGR
By pmarketresearch, 2026-09-16
Global Glycopeptide Antibiotics Market Outlook 2026: Navigating Growth, Concentration, and Supply Complexity
The worldwide glycopeptide antibiotics market stands at a pivotal inflection point as healthcare systems balance rising antimicrobial resistance with evolving manufacturing economics and regulatory frameworks. For pharmaceutical executives, hospital procurement strategists, and investment analysts, the 2026-2032 forecast window demands a clear-eyed assessment of where durable revenue will originate and where structural friction will reshape competitive positioning. This market intelligence briefing distills the core trajectories, operational realities, and strategic implications captured in our Worldwide Glycopeptide Antibiotics Market research, providing decision-makers with a framework to allocate capital, optimize supply contracts, and anticipate policy shifts with precision.
Worldwide Glycopeptide Antibiotics Market
Beginning from a base year of 2025, the sector has demonstrated a measured but consistent expansion trajectory. Historical tracking from 2020 through 2025 reveals how the market navigated pandemic-era procurement volatility, shifts in hospital formulary preferences, and persistent demand for Gram-positive coverage. The forecast horizon extending to 2032 projects a compound annual growth rate of 4.6 percent, anchoring expectations around steady volume growth, continued reliance on established glycopeptide backbones, and gradual penetration of next-generation lipoglycopeptide options. Revenue is tracked in USD millions, and the forward curve highlights years of incremental build followed by periods of accelerated expansion as clinical adoption, reimbursement clarity, and supply chain stabilization converge. For executives planning multi-year portfolios, the essential takeaway is that growth will not be linear; it will be shaped by the interplay of regional procurement cycles, formulation innovation, and cost pressures across the active pharmaceutical ingredient supply base.
Structural Foundations Shaping the Forecast
The composition of demand across drug types underscores a market anchored by high-volume legacy molecules while newer lipoglycopeptide candidates carve out differentiated clinical niches. Vancomycin continues to serve as the therapeutic and commercial cornerstone, reflecting its entrenched role in hospital protocols and broad-spectrum Gram-positive coverage. Teicoplanin maintains a meaningful presence in specific geographies and treatment pathways, while dalbavancin, oritavancin, and telavancin represent the long-acting and specialized segments where dosing convenience, outpatient administration potential, and stewardship considerations influence adoption. The interplay among these categories is not merely a clinical story; it is a commercial one, because product mix decisions affect inventory planning, hospital purchasing patterns, and the strategic calculus of manufacturers investing in differentiated formulations or lifecycle extensions.
From an application perspective, skin and soft tissue infections and hospital-acquired pneumonia represent the highest-demand treatment settings, where empiric and targeted therapy for resistant organisms drives consistent utilization. Bacteremia and endocarditis add a critical dimension to the demand profile, given the severity of illness, the need for reliable serum exposure, and the consequential role of glycopeptides in saving lives when alternatives are limited. Clostridioides difficile-associated disease further reinforces the market's breadth, as oral and adjunctive glycopeptide strategies remain part of the therapeutic toolkit in specific care environments. The commercial implication is that successful market participation requires far more than volume production; it demands an understanding of ordering rhythms by indication, treatment duration variability, and the operational realities of inpatient versus outpatient delivery.
Price and cost dynamics form a third structural pillar. Between 2022 and 2025, global antibiotic API production costs increased by an estimated 25-30 percent due to higher energy inputs, chemical feedstock pressures, and wage inflation across key manufacturing locations. For glycopeptides, this cost environment has filtered through formulation economics, inventory carrying decisions, and contract negotiations. At the same time, supply concentration risks merit close attention, particularly given that China accounted for more than 60 percent of recent US antibiotic API import volume, contributing to a concentrated supply base for glycopeptide precursors and finished dosage forms. These realities elevate the strategic importance of dual sourcing, regional redundancy, and long-term framework agreements that can absorb cost fluctuations without compromising continuity of care.
Competitive Landscape and Differentiation Themes
The competitive architecture of this market is defined by a combination of branded specialty positioning, mature generic supply, and API-centric manufacturing capabilities. Market concentration data indicates a moderately consolidated environment, with the top three competitors accounting for a substantial share of revenue and the top five firms representing the majority of commercial activity. This structure rewards scale, regulatory proficiency, and distribution reach, but it also leaves room for specialized players that offer formulation advantages, stable supply commitments, or differentiated service models to capture meaningful share in targeted segments.
Pfizer's presence in the space is anchored by dalbavancin, a lipoglycopeptide positioned for acute bacterial skin and skin structure infections caused by susceptible Gram-positive organisms. Its commercial profile benefits from long-acting dosing characteristics that can reduce treatment frequency and support outpatient transition strategies, especially where reimbursement pathways and administration logistics align. Hikma Pharmaceuticals has strengthened its standing with FDA-approved vancomycin injection products, including a ready-to-infuse, room-temperature stable formulation cleared in 2025 for serious Gram-positive infections such as septicemia, endocarditis, and skin structure infections. This type of formulation innovation addresses practical hospital pain points: reduced preparation time, simplified bedside administration, and storage flexibility that can matter in high-throughput clinical environments.
ANI Pharmaceuticals reinforces the oral vancomycin segment through a branded capsule offering indicated for C. difficile-associated diarrhea and staphylococcal enterocolitis, reflecting a niche where formulation specificity and clinician familiarity support sustained demand. Fresenius, through its Kabi division, supplies generic vancomycin and other injectable glycopeptide formulations for hospital use, emphasizing dependable supply and integration into institutional purchasing systems. Xellia Pharmaceuticals maintains a specialized focus on anti-infective APIs and finished dosage forms, with vancomycin API and related formulations supporting critical care applications where supply reliability is paramount. Aurobindo Pharma and Zhejiang Hisun Pharmaceutical contribute broad generic vancomycin and glycopeptide API capabilities for global markets, underscoring the importance of internationally competitive manufacturing footprints. Mylan, now operating under Viatris, offers generic vancomycin hydrochloride injection for serious infections caused by susceptible methicillin-resistant staphylococci, reinforcing the breadth of the generic supply layer that hospitals and distributors rely on for cost management and continuity.
Taken together, these players illustrate a market where differentiation is increasingly tied to formulation practicality, regulatory milestones, supply resilience, and commercial execution rather than first-in-class novelty alone. For buyers, this landscape creates leverage through supplier diversification. For manufacturers, it demands disciplined lifecycle planning, rigorous quality systems, and clear value propositions that extend beyond molecule-level competition.
Operational Realities and Policy Signals That Matter
Beyond molecule-level competition, several operational and regulatory developments shape how the market will function across the forecast period. Updated antimicrobial susceptibility testing systems have received clearance with revised breakpoints for telavancin and daptomycin against Enterococcus faecalis, including vancomycin-resistant strains. While this primarily affects laboratory interpretation and stewardship workflows, it also influences prescribing confidence, formulary positioning, and downstream utilization patterns for related glycopeptide therapies. The broader lesson for commercial teams is that diagnostic and susceptibility updates can shift treatment selection at the margin, making it essential to monitor laboratory guidance as part of market sensing.
Reimbursement architecture also plays an outsized role in adoption decisions. For example, specific long-acting glycopeptide therapies are reimbursed under designated injection codes in hospital outpatient and related settings for acute bacterial skin and skin structure infections. Such coding clarity can accelerate uptake where administration efficiency, patient throughput, and cost-per-episode economics favor outpatient transition. The practical implication is that market access strategy cannot be separated from supply strategy; formulation characteristics, administration setting, and payer coding must be evaluated in concert.
Regulatory continuity remains reassuring for core glycopeptide indications. Vancomycin continues to be indicated for serious infections due to susceptible Gram-positive bacteria, including MRSA, and there is no widespread market discontinuation or recall of core glycopeptide products. This stability supports baseline demand visibility, but it does not eliminate the need to manage supply risk, quality compliance, and procurement timing, especially as hospital budgets remain under pressure and purchasing groups consolidate volumes to extract efficiency.
On the cost and supply side, the combination of API cost inflation and concentrated sourcing patterns argues for a more deliberate approach to procurement architecture. Facilities that depend heavily on single-source inputs or geographically concentrated supply chains face heightened exposure to disruption, price volatility, and lead-time uncertainty. Leading organizations are increasingly pairing demand forecasting with supplier qualification, inventory buffering where clinically appropriate, and contractual structures that provide transparency around cost drivers. In this market, resilience is becoming a competitive advantage as much as a risk control measure.
How This Research Converts Into Decision-Ready Intelligence
Our Worldwide Glycopeptide Antibiotics Market study is designed to move beyond high-level trend summaries and equip teams with actionable detail across market sizing, segmentation, competitive profiling, and dynamic drivers. The analysis covers historical performance from 2020 through the 2025 base year and extends across the full 2026-2032 forecast period, giving stakeholders a continuous view of how market momentum is expected to evolve. Revenue is presented in USD millions, with growth rates and trajectory indicators structured to support scenario planning, budgeting, and internal benchmarking.
The segmentation framework provides separate lenses on region, drug type, and application, allowing readers to isolate where growth is being generated, which product categories are expanding or stabilizing, and how indication-level demand differs by care setting and clinical pathway. Rather than treating the market as a single aggregate, the study breaks down demand behavior so that commercial leaders can align product strategy, inventory planning, and sales coverage with the realities of each segment. Competitive profiling goes beyond corporate descriptions to map positioning, formulation differentiation, supply roles, and recent moves that affect market share dynamics. This includes attention to regulatory approvals, formulation advancements, and product availability milestones that can shift buyer preferences in specific hospital and outpatient environments.
The study also integrates industry dynamics that influence execution risk and commercial potential. That includes regulatory updates affecting susceptibility testing and breakpoint interpretation, API cost trends and their implications for formulation economics, supply chain concentration patterns and their impact on continuity planning, and reimbursement structures that affect adoption in outpatient and hospital-based settings. By connecting these forces to market outcomes, the research supports more credible forecasting, more informed sourcing decisions, and more resilient commercial plans.
Strategic Priorities for 2026 and Beyond
For executives entering 2026, the most valuable use of this intelligence is to translate market structure into prioritized action. First, clarify where your portfolio aligns with durable demand. Skin and soft tissue infections, hospital-acquired pneumonia, bacteremia and endocarditis, and C. difficile-related care all contribute meaningfully to utilization, but each carries distinct procurement rhythms, treatment duration profiles, and service-delivery requirements. Segmentation insight helps avoid overgeneralizing demand and enables targeted investment in the categories and channels where adoption is most likely to hold or accelerate.
Second, treat supply resilience as a strategic asset. With API cost inflation and concentrated sourcing patterns reshaping cost-to-serve, organizations should evaluate sourcing redundancy, contractual transparency, and inventory logic in relation to clinical criticality. For manufacturers and distributors, differentiated value may come from formulation convenience, storage flexibility, or reliable supply performance that reduces operational friction for hospitals. For buyers, it may come from structured supplier diversification and clear visibility into cost drivers.
Third, monitor the policy and reimbursement environment as a growth enabler or constraint. Susceptibility breakpoint changes, coding frameworks for injectable therapies, and institutional formulary review cycles can influence adoption trajectories at the margin. Early awareness of these shifts allows commercial and market access teams to prepare communication, evidence, and contracting strategies before demand signals fully materialize.
Finally, use competitive intelligence to sharpen positioning. In a market where the top five players hold a substantial share and the top three command an even larger portion, smaller or more specialized participants can still win by focusing on formulation advantages, supply reliability, and service responsiveness. The research provides the context needed to identify where differentiation is credible and where head-on volume competition should be approached with caution.
Closing Perspective
The glycopeptide antibiotics market is not defined by dramatic disruption, but by the cumulative effect of clinical reliance, formulation innovation, cost pressure, and supply concentration. That combination makes disciplined analysis especially valuable for 2026 decision-making. Growth is projected at a steady pace, demand is anchored in serious Gram-positive infections, and competitive advantage increasingly depends on execution quality as much as product portfolio. For organizations seeking to allocate resources with confidence, understand where share is being created, and anticipate the operational factors that will shape performance across 2026-2032, the full Worldwide Glycopeptide Antibiotics Market research provides the depth required to move from awareness to action.
Antimicrobial Peptides Market
For detailed analysis of this topic, please visit the official page: Worldwide Glycopeptide Antibiotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com