

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Acute Care EHR Market to Hit $50.57B by 2032, Growing at 6.52% CAGR

Navigating the Global Acute Care EHR Landscape: Strategic Imperatives for 2026 Decision-Makers
The worldwide acute care electronic health record market stands at a critical inflection point. As health systems allocate multi-year capital budgets and navigate shifting regulatory frameworks, the choice of EHR platform has evolved from an IT procurement decision into a foundational strategic maneuver. Our latest Worldwide Acute Care Electronic Health Recorder Market research synthesizes historical performance, forward-looking projections, and granular competitive intelligence to equip executives with the analytical clarity required for 2026 and beyond.
Acute Care Telemedicine Services Market
This report is designed as a decision-support instrument rather than a static market snapshot. It maps the structural forces shaping procurement cycles, evaluates the competitive positioning of dominant and emerging vendors, and benchmarks operational priorities against real-world spending behavior. The objective is straightforward: translate complex market signals into actionable intelligence for hospital administrators, health system strategists, technology investors, and policy advisors who must justify capital allocation in an environment of compressed margins and accelerated digital transformation.
Market Trajectory and Structural Growth Drivers
The global acute care EHR market has demonstrated consistent expansion over the past half-decade, reflecting the industry-wide imperative to digitize clinical workflows, strengthen interoperability, and support value-based care models. From a 2020 baseline of USD 24,500 million, the market advanced through 2021 at USD 26,878.16 million, reached USD 28,211.83 million in 2022, and climbed to USD 29,500.61 million in 2023. Growth momentum continued as 2024 recorded USD 31,923.36 million, followed by a 2025 valuation of USD 32,500.0 million.
These historical figures establish a clear trajectory of sustained adoption, but the forward-looking data is where strategic planning gains its most practical utility. Our forecast period spans 2026 through 2032, anchored by a compound annual growth rate of 6.52 percent. This growth profile translates to a 2026 estimate of USD 33,762.2 million, progressing to USD 37,576.93 million in 2027, USD 37,960.9 million in 2028, USD 41,469.16 million in 2029, USD 45,333.3 million in 2030, USD 47,227.17 million in 2031, and a projected 2032 valuation of USD 50,570.0 million.
The persistence of this growth curve is not merely a function of technological modernization. It reflects deeper structural pressures: ongoing interoperability mandates, the integration of AI-enabled clinical decision support, heightened cybersecurity requirements, and the financial volatility that forces health systems to optimize operational efficiency without sacrificing care quality. Our forecast methodology isolates these drivers and models their cumulative impact on procurement cycles, upgrade timelines, and platform migration activity across diverse facility profiles.
Capital expenditure patterns confirm this strategic prioritization. Enterprise technology investments, including EHR implementations and upgrades, remain embedded in multi-year capital budgets that routinely reach billions of dollars. At the same time, spending priorities are recalibrating. AI-based clinical technology solutions have emerged as the leading planned technology initiative for health systems at 57 percent for the 2026-2027 horizon, while EHR optimization spending share has shifted to 43 percent. This rebalancing does not diminish the EHR's centrality; rather, it signals a maturation phase in which foundational digital infrastructure must interoperate seamlessly with next-generation clinical tools.
Competitive Landscape and Vendor Positioning
Market concentration remains pronounced, with the top three players commanding 72.5 percent of total market share and the top five collectively holding 84.2 percent. This concentration shapes negotiation leverage, integration roadmaps, and the risk-reward calculus of platform selection. The competitive field is anchored by organizations with distinct operational philosophies, deployment footprints, and target constituencies.
Epic Systems Corporation, headquartered in Verona, Wisconsin, provides a comprehensive acute care EHR platform distinguished by deep inpatient, surgical, emergency department, and enterprise-wide integration functionality. Its dominance in large hospital systems and academic medical centers is reinforced by a strong focus on seamless clinical documentation and interoperability. Epic's market momentum remains significant, having recorded its largest net gain in US acute care EHR market share by adding 176 multispecialty hospitals and nearly 30,000 beds in 2024 decisions. This trajectory underscores the vendor's ability to capture large-scale migrations and consolidate complex enterprise workflows.
Oracle Health, formerly operating under the Cerner brand and now integrated within Oracle's Austin, Texas headquarters, offers the Millennium platform with strong acute care capabilities spanning inpatient, surgical, and emergency department functionality. The platform serves hospitals of varying sizes with an emphasis on cloud infrastructure integration and large-scale deployments. Recent independent analysis positions Oracle Health at a critical juncture, highlighting ongoing product developments in acute care EHR alongside complex partnership dynamics that warrant close monitoring by organizations evaluating long-term vendor stability and roadmap alignment.
Medical Information Technology, Inc., known as MEDITECH, is based in Westwood, Massachusetts and delivers the Expanse platform as a full acute care EHR suited for community hospitals, rural facilities, and smaller organizations. Its value proposition centers on cost-effective inpatient solutions with stable support for 1-200 bed facilities. For health systems seeking predictable total cost of ownership without sacrificing core clinical functionality, MEDITECH's positioning remains a strategically relevant benchmark.
Evident, operating under CPSI in Mobile, Alabama, specializes in TruBridge and Thrive acute care EHR platforms targeted at community hospitals with fewer than 400 beds. Its focus on comprehensive solutions for smaller acute care organizations and affiliated clinics addresses a segment where workflow simplicity, integration with ambulatory networks, and administrative efficiency often outweigh the complexities of enterprise-scale architectures.
Altera Digital Health, formerly known as the Allscripts Hospitals and Large Physician Practice business and based in Chicago, Illinois, provides the Sunrise Enterprise suite for acute care EHR including clinical and financial solutions. The platform targets hospitals and health systems with flexible, open architectures supporting inpatient workflows. Its design philosophy appeals to organizations that prioritize modularity and third-party interoperability within a unified clinical and financial framework.
Veradigm, also headquartered in Chicago and formerly Allscripts, offers ambulatory and select acute care EHR solutions with a focused emphasis on interoperability and integration with third-party applications. It maintains a presence across hospital and practice settings following its strategic divestiture, serving use cases where cross-continuum data exchange and application extensibility are paramount.
Beyond individual vendor profiles, the market exhibits sustained migration activity. Throughout 2025 and into 2026, multiple hospitals and health systems have announced EHR platform changes and migrations in acute care settings. These migrations are rarely purely technical exercises; they are strategic re-alignments driven by cost pressures, workflow dissatisfaction, interoperability gaps, and the desire to future-proof infrastructure against emerging clinical technology requirements.
Operational and Financial Dynamics Shaping Procurement Decisions
Strategic procurement cannot be evaluated in isolation from the financial and operational environment in which it occurs. Total hospital expenses grew 7.5 percent in 2025, a pace more than twice the rate of growth in hospital prices, driven by labor, drugs, and supplies. This expense compression forces executive teams to scrutinize every capital deployment for measurable return on investment, workflow efficiency gains, and risk mitigation potential.
Simultaneously, cybersecurity has become a non-negotiable line item. Hospitals spent roughly USD 30 billion in 2025 on technology and services to protect systems, data, and operations from cyber threats. This expenditure directly intersects with EHR strategy, as clinical platforms operate at the center of protected health information flows, device integrations, and network-dependent care delivery. Procurement decisions increasingly require explicit evaluation of security architecture, vendor incident response capabilities, and alignment with enterprise-wide resilience frameworks.
Regulatory and reimbursement dynamics add further complexity. The Medicare IPPS proposed rule for acute care hospitals revises inpatient prospective payment systems for operating and capital-related costs, influencing how health systems budget for technology investments and evaluate reimbursement alignment. These changes modulate the financial rationale behind platform upgrades, particularly when capital-related cost structures intersect with depreciation schedules, implementation timelines, and long-term total cost of ownership models.
Under these conditions, the decision to standardize on a platform, migrate to a new environment, or optimize an existing deployment becomes a multi-variable optimization problem. Executives must weigh clinical workflow compatibility, interoperability roadmaps, cloud versus on-premise deployment economics, vendor stability, integration readiness for AI-based clinical tools, and the financial implications of migration downtime. Each of these variables carries distinct risk profiles depending on hospital type, facility size, regional regulatory exposure, and existing technology debt.
Depth of Report Coverage and Strategic Application
This market research is structured to support applied decision-making rather than abstract market observation. The analysis integrates historical performance data with forward-looking projections and contextualizes them within the operational realities that govern purchasing behavior. The report examines deployment model dynamics, hospital type segmentation, regional adoption patterns, and competitive concentration to reveal where growth is concentrated and where strategic opportunity lies.
Deployment architecture remains a central axis of evaluation. Cloud-based implementations and on-premise deployments each present distinct governance, cost, scalability, and control trade-offs that influence how health systems structure multi-year technology roadmaps. The relative share of these deployment models provides insight into shifting infrastructure preferences, particularly as organizations balance capital efficiency against data sovereignty, integration complexity, and long-term scalability requirements.
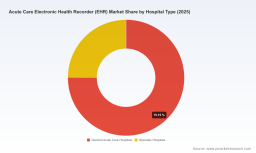
Hospital type segmentation further clarifies demand patterns. General acute care hospitals and specialty hospitals exhibit differentiated clinical workflows, financial structures, and interoperability priorities, which in turn shape platform fit and procurement rationale. Understanding how market value distributes across these facility categories enables more precise targeting of implementation strategies, vendor negotiations, and optimization investments.
Regional analysis adds an additional strategic layer. Geographic variation in regulatory mandates, reimbursement environments, digital maturity, and competitive intensity affects both the pace of adoption and the vendor mix favored in each territory. The report contextualizes these regional dynamics without reducing them to simplistic rankings, instead highlighting how local market structures influence migration patterns, partnership opportunities, and implementation risk.
Competitive monitoring is embedded throughout the analysis. Recent developments indicate that Epic continues to expand its footprint in large-scale acute care environments, Oracle Health is executing product advancements amid partnership complexities that require careful vendor diligence, MEDITECH maintains strong relevance for smaller and community-based settings, Evident addresses niche acute care configurations, and Altera and Veradigm sustain differentiated positions around open-platform flexibility and interoperability-focused integration. These dynamics are evaluated not as static profiles but as evolving strategic postures that affect procurement leverage and long-term vendor reliability.
Strategic Implications for 2026 Planning Cycles
As health systems finalize 2026 capital plans and extend technology roadmaps into the late decade, several strategic implications emerge from the market structure.
- Platform selection must be evaluated against migration risk and total cost of ownership, not only initial functionality. The concentration of market share among leading vendors means that organizations can benefit from mature interoperability networks and broader implementation experience, but they must also assess vendor dependency, contract flexibility, and long-term roadmap alignment.
- AI-enabled clinical technology is becoming the planning anchor for health system innovation. With AI-based clinical solutions leading planned technology initiatives, EHR platforms must demonstrate readiness for integration, data structuring, and workflow augmentation. Optimization spending remains substantial, but its role is increasingly defined by how well the platform supports adjacent clinical intelligence investments.
- Cybersecurity and regulatory alignment are procurement prerequisites, not add-ons. The significant expenditure on cyber protection and the evolving IPPS reimbursement environment mean that security architecture, compliance readiness, and capital cost modeling belong at the center of evaluation frameworks.
- Migration activity is a strategic signal, not merely an operational event. Continued announcements of EHR platform changes reflect structural dissatisfaction, expansion ambitions, and the pursuit of interoperability and workflow efficiency. Organizations monitoring these migrations can extract benchmarks for negotiation, implementation sequencing, and risk mitigation.
- Capital allocation discipline will separate durable strategies from reactive purchases. Expense growth outpacing price growth, combined with multi-year budget commitments, requires executives to justify EHR investments through measurable efficiency gains, reduced rework, improved documentation quality, and enhanced integration with enterprise technology objectives.
Conclusion
The worldwide acute care EHR market is expanding along a defined growth trajectory while simultaneously undergoing strategic recalibration in how platforms are evaluated, integrated, and defended against evolving operational and financial pressures. The convergence of sustained adoption, competitive concentration, migration momentum, cybersecurity imperatives, and AI-centric planning priorities creates a market environment where informed decision-making offers tangible competitive advantage.
Our research provides the depth and structure needed to navigate that environment. It translates historical performance into forward-looking perspective, situates vendor dynamics within broader market concentration patterns, and aligns procurement considerations with real-world financial and regulatory forces. For executives responsible for 2026 capital planning, platform strategy, and long-term digital transformation, the report offers a framework for reducing uncertainty and increasing the strategic precision of technology investment decisions.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
To access the complete segmentation analysis, regional breakdowns, deployment model comparisons, hospital type distributions, competitive intelligence detail, and full forecast tables, we invite you to explore the source page for the complete Worldwide Acute Care Electronic Health Recorder Market research. The full dataset and methodological documentation are available there for teams that require granular intelligence to support executive briefings, vendor evaluations, and capital allocation decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Care Electronic Health Recorder (EHR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com