

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Reformer Unit Market to Hit $1,383.65M by 2032, 6.95% CAGR

Global Reformer Unit Market Outlook 2026: Strategic Intelligence for Industrial Decision Makers
Market Trajectory and Structural Resilience
The Worldwide Reformer Unit Market represents a critical nexus in global industrial infrastructure, underpinning hydrogen generation, ammonia synthesis, methanol production, and oil refining operations. As organizations navigate capital allocation decisions through the late 2020s, understanding the revenue trajectory and structural drivers within this sector has become indispensable. Our latest market research delivers a comprehensive assessment of an industry that expanded from 620.5 Million USD in 2020 to an estimated 864.5 Million USD in 2025, reflecting consistent year-over-year momentum through evolving feedstock landscapes and shifting regulatory environments.
Worldwide Reformer Unit Market
Looking ahead, the forecast horizon spanning 2026 through 2032 projects sustained expansion with a compound annual growth rate of 6.95 percent. This trajectory points toward a market exceeding 1.3 Billion USD by the close of the forecast window. The underlying demand architecture is multifaceted, driven by expanding hydrogen economy initiatives, low-carbon ammonia ventures, and ongoing refinery modernization programs. Critically, this growth narrative is not a simplistic extrapolation of historical volumes. It reflects transformative shifts in reformer technology selection, geographic deployment patterns, and the commercial calculus surrounding decarbonization compliance.
For executives evaluating procurement strategies, capacity expansion plans, or technology licensing partnerships, the distinction between historical performance and forward-looking inflection points carries substantial financial weight. The market's acceleration trajectory is increasingly tied to regulatory timelines, feedstock flexibility requirements, and the competitive positioning of engineering firms that can deliver integrated, low-emission reformer solutions at commercial scale. Our research dissects these variables with granular precision while maintaining the analytical ambiguity necessary for proprietary advantage.
Segmentation Architecture and Demand Concentration
Reformer unit procurement decisions are inherently segmented across type, application, and geographic deployment zones, each carrying distinct technical specifications and commercial implications. The market ecosystem encompasses steam methane reforming configurations, catalytic reforming platforms, and autothermal reformer designs, with procurement volumes and revenue contribution varying across industrial end-uses including hydrogen production, ammonia manufacturing, methanol synthesis, and oil refining operations. Understanding the precise weighting of these segments informs everything from supplier negotiation leverage to long-term technology roadmapping.
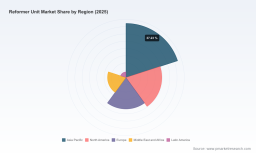
Geographic distribution patterns further complicate strategic planning. Industrial development across Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America exhibits divergent pacing driven by localized energy transition mandates, feedstock availability, and infrastructure investment cycles. Buyers operating across multiple jurisdictions must reconcile these regional variances against centralized procurement targets, a complexity that standard industry summaries rarely capture with sufficient operational granularity.
Market concentration metrics offer additional insight into the competitive equilibrium. The industry remains moderately consolidated, with the top three firms commanding significant revenue share and the top five collectively representing a substantial majority of market activity. This concentration shapes pricing dynamics, licensing negotiations, and the strategic behavior of both incumbent technology providers and emerging equipment manufacturers. Organizations seeking to enter supplier relationships or evaluate partnership opportunities must account for the bargaining power embedded within this concentration structure.
Competitive Landscape: Major Players and Strategic Moves
The reformer unit market features a diversified competitive field spanning engineering contractors, technology licensors, catalyst specialists, and high-temperature component manufacturers. Each participant brings distinct capability profiles that influence procurement decisions across different application verticals and project scales.
Linde Engineering has established a formidable footprint through the delivery of over 250 reforming furnaces worldwide, offering top-fired, side-fired, and wall-fired configurations alongside its HYDROPRIME modular cylindrical and skid-mounted solutions. The company's emphasis on heat recovery optimization and low-emission revamps positions it favorably within hydrogen, syngas, ammonia, and methanol applications. Recent activity underscores this strategic direction: in February 2025, Linde Engineering secured a record number of small on-site solutions including hydrogen-related plants driven by decarbonization priorities, and in June 2025, Linde signed a long-term industrial gas supply agreement for a world-scale low-carbon ammonia facility incorporating autothermal reforming.
Honeywell UOP and Axens dominate the catalytic reforming segment, supplying process technologies, catalysts, and modular equipment for refinery reformer units. Honeywell UOP focuses on semi-regenerative and continuous catalytic reforming licensing with high-octane gasoline and aromatics as primary outputs. Axens contributes its Octanizing CCR processes and semi-regenerative solutions, supported by over 130 licenses globally, with integrated offerings spanning gasoline production, aromatics, and residue upgrading. Both firms remain central to refinery modernization strategies as operators seek to balance throughput targets against emissions constraints.
Worldwide Steam Reformers Market
KBR and Technip Energies provide complementary engineering and licensing capabilities across steam methane reforming and autothermal reforming for hydrogen and syngas applications, with Technip Energies also delivering comprehensive EPC services. Johnson Matthey addresses the catalyst layer through its KATALCO series and pre-reforming formulations optimized for ammonia, methanol, hydrogen, and gas-to-liquid production, directly influencing reformer efficiency and operational lifespan.
Component-level suppliers such as MetalTek International and Kubota Corporation supply centrifugally cast reformer tubes, outlet manifolds, and heat-resistant cast steel components designed for extended creep-resistant service life of 10 to 12 years or more in high-temperature and high-pressure environments. Wood plc and Larsen & Toubro Limited round out the competitive field through engineering, consulting, and construction engagements spanning refining and hydrogen production contexts. Topsoe's October 2025 conference presentation on electrifying steam reformers as a sustainable hydrogen pathway signals growing industry focus on next-generation process electrification, reinforcing the competitive imperative around innovation velocity.
Industry Dynamics Shaping 2026 Decision-Making
Several converging forces are reshaping procurement timelines and technology selection criteria across the reformer unit ecosystem. Energy efficiency mandates and decarbonization requirements are accelerating adoption of electrified steam reformer configurations capable of reducing direct flue gas carbon dioxide emissions by substantial margins while improving thermal efficiency in existing ammonia plant installations. Concurrently, stricter greenhouse gas emission regulations and carbon pricing mechanisms are exerting financial pressure on conventional fuel-fired reformer architectures, prompting operators to evaluate electrification pathways and carbon capture integration as viable compliance strategies.
Hydrogen economy initiatives and low-carbon ammonia and hydrogen project pipelines continue to sustain demand for advanced reformer designs characterized by enhanced efficiency metrics and carbon capture compatibility. These project-level drivers interact with macroeconomic variables, particularly raw material cost trajectories. Global steel prices, which serve as the primary input for reformer tubes and pressure vessels, are positioned at or near the bottom of the current price cycle entering 2026, with subdued recovery anticipated through the year and a more meaningful upturn projected from 2027 onward. This cost dynamic carries direct implications for equipment procurement budgets, contract timing, and vendor negotiation leverage.
The interplay between regulatory pressure, technology availability, and input cost cycles creates a decision environment where timing and specificity matter enormously. Organizations that delay evaluation of electrified or hybrid reformer configurations risk exposure to rising compliance costs and potential capacity constraints as supplier order books fill. Conversely, premature commitment without accurate segment-level intelligence can result in suboptimal capital deployment, misaligned technology selection, or unfavorable commercial terms.
Research Methodology and Report Scope
Our Worldwide Reformer Unit Market research is structured to deliver actionable intelligence across multiple decision dimensions. The report integrates quantitative market sizing with qualitative technology and competitive analysis, providing a single reference point for strategic planning teams. Key components include detailed segmentation breakdowns by type, application, and region, with revenue estimates and growth trajectories mapped across the historical 2020 through 2025 period and the forecast 2026 through 2032 window.
The competitive profiling section delivers individualized company assessments encompassing headquarters location, core technology offerings, recent project activity, and strategic positioning within specific reformer sub-markets. These profiles are supplemented by a curated timeline of recent industry developments, capturing conference presentations, project award milestones, long-term supply agreements, and regulatory announcements that signal near-term market direction.
Demand-side analysis examines application-specific drivers across hydrogen, ammonia, methanol, and oil refining verticals, while regional assessments contextualize deployment pacing against localized policy frameworks, infrastructure investment cycles, and feedstock economics. The report further integrates upstream cost dynamics, including steel and alloy material trends, to inform procurement timing strategies and budget forecasting. Market concentration metrics and competitive equilibrium analysis support supplier evaluation and partnership structuring decisions.
Strategic Implications for Corporate Planning
The reformer unit market sits at the intersection of energy transition imperatives, refinery modernization requirements, and industrial gas demand growth. For executives navigating 2026 planning cycles, the strategic question is no longer whether this market will grow, but how the growth will be distributed across technologies, geographies, and supplier ecosystems. Our research provides the depth required to answer that question with confidence.
Organizations evaluating new capacity investments must weigh the technical trade-offs between steam methane, catalytic, and autothermal configurations against localized regulatory timelines and feedstock economics. Procurement teams negotiating with engineering contractors and component suppliers must incorporate steel price cycle projections and concentration-driven pricing dynamics into cost models. Technology strategists assessing electrification and carbon capture integration pathways require precise benchmarks on efficiency gains, emission reduction potential, and commercial availability timelines.
Contact our research team to access the full Worldwide Reformer Unit Market report and secure the granular data, segmentation breakdowns, and competitive intelligence necessary to sharpen your 2026 strategic positioning. The complete dataset, detailed regional and application-level analysis, and extended company profiles are available exclusively through our direct research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com