

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Solar Laser Drilling Market Hits $692.47M in 2025, Projected to Surpass $1.6B by 2032

Unlocking Precision: Strategic Insights into the Worldwide Solar Laser Drilling Market (2026-2032)
Executive Summary: The Imperative for Precision Scaling
The global photovoltaic manufacturing landscape is undergoing a fundamental transformation. As cell efficiencies approach theoretical limits, the burden of performance improvement shifts from material science alone to the precision of manufacturing processes. In this context, laser drilling has evolved from a niche capability into a cornerstone of high-throughput solar cell production. Our latest market research, Worldwide Solar Laser Drilling Market, offers a definitive analysis of this critical sector, providing the intelligence necessary for strategic decision-making in 2026 and beyond.
This study is not merely a collection of statistics; it is a strategic roadmap designed to help stakeholders navigate the convergence of technological innovation, macroeconomic volatility, and shifting regional demands. By synthesizing historical performance with rigorous forecasting, we illuminate the path toward sustainable growth in an industry defined by rapid iteration.
Market Trajectory and Magnitude: A Decade of Acceleration
The financial trajectory of the solar laser drilling sector signals robust confidence in the long-term viability of photovoltaic expansion. We have observed a steady compounding of value over the historical review period, reflecting the industry's transition toward more sophisticated module architectures. Starting from a foundation of approximately $372 million in 2020, the market has scaled significantly to reach an estimated $692 million by 2025. This growth underscores the essential role laser technology plays in meeting global energy targets.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. We anticipate the market to breach the $780 million threshold in 2026, accelerating toward a peak valuation exceeding $1.6 billion by the end of the decade. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 13.66 percent. Such consistent growth indicates that laser drilling is not susceptible to the transient fluctuations affecting broader manufacturing equipment sectors. Instead, it is driven by permanent shifts in cell design requirements, specifically the need for high-precision contact opening and glass processing in double-glass modules.
These figures represent more than just revenue; they reflect the capital intensity required to maintain competitive parity. Manufacturers who fail to integrate advanced laser solutions risk yield penalties and throughput bottlenecks, particularly as wafer thicknesses decrease and cell architectures become more complex. Our research quantifies this investment requirement, allowing CAPEX planners to align their budgets with realistic market demands.
Strategic Segmentation: Technology and Application Drivers
To understand where value is created, one must dissect the market into its core operational components. Our analysis categorizes the landscape by laser type and solar cell technology, revealing distinct pockets of opportunity that require tailored strategic approaches.
Laser Technology Evolution
The market is currently defined by a spectrum of laser technologies, each serving specific process requirements. Nanosecond lasers continue to hold a substantial share of the market, driven by their established role in high-throughput processes such as laser contact opening and dicing. These systems offer a balance of speed and cost-effectiveness that remains vital for high-volume PERC cell production.
However, the frontier of innovation lies in ultrafast processing. Picosecond and femtosecond laser segments are gaining traction as manufacturers seek to minimize thermal damage and improve edge quality in advanced cell designs. The adoption of these technologies is closely tied to the transition toward higher efficiency cell architectures. While nanosecond systems provide the workhorse capacity for current generation manufacturing, ultrafast sources are becoming critical for next-generation prototypes and specialized applications where precision outweighs pure throughput speed. Understanding the cost-benefit analysis of migrating from nanosecond to picosecond or femtosecond sources is a key component of our report, helping engineering leaders justify technology upgrades.
Worldwide Laser Drilling Device Market
Cell Technology Alignment
Market demand is inextricably linked to the prevailing solar cell technologies being deployed globally. PERC cell processing remains a dominant driver of laser drilling demand, particularly for laser contact opening procedures that define cell efficiency. As the industry matures, the volume of PERC production ensures a stable baseline for equipment manufacturers.
Simultaneously, the rise of TOPCon cell processing is reshaping the demand profile. TOPCon architectures require precise laser doping and contact formation steps that differ significantly from PERC workflows. Our research details the specific laser process requirements for TOPCon, enabling equipment suppliers to tailor their solutions and manufacturers to optimize their line configurations. Furthermore, the emerging sector of IBC and next-generation cells presents high-value opportunities. Although currently smaller in volume, these technologies demand the highest levels of precision, creating a premium market segment for specialized laser solutions that can handle complex back-contact structures.
Regional Dynamics and Supply Chain Realities
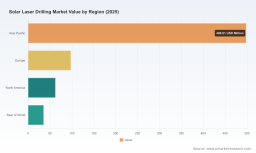
Geographic distribution of demand is another critical vector for strategic planning. The Asia Pacific region continues to exhibit the strongest gravitational pull on market volume, reflecting its status as the global hub for solar manufacturing capacity. The concentration of production facilities in this region means that logistics, local support, and regional pricing strategies are paramount for equipment providers.
Europe and North America represent mature markets with distinct characteristics. In these regions, demand is often driven by high-value niche applications, R&D infrastructure, and specific regulatory environments regarding manufacturing localization. The Rest of World segment, while smaller in current volume, holds latent potential as emerging economies develop their own photovoltaic supply chains. Our report analyzes the risk and opportunity associated with each region without relying on simplistic percentage splits, focusing instead on the qualitative drivers such as local content requirements, trade policies, and infrastructure development that dictate regional growth.
Worldwide Solar Laser Drilling Market
Competitive Landscape: Navigating a Concentrated Ecosystem
The solar laser drilling market is characterized by a moderate-to-high level of concentration. With the top three players accounting for over 40 percent of the market and the top five capturing nearly 60 percent, barriers to entry remain significant. Success in this environment requires not only technological superiority but also strong channel partnerships and localized service capabilities.
Leading equipment manufacturers such as 3D-Micromac AG have entrenched themselves by providing high-throughput micromachining systems tailored for photovoltaics, including specialized solutions for laser contact opening and thermal laser separation. Their focus on process integration demonstrates how vendors are moving beyond selling hardware to offering complete process solutions. Similarly, industrial giants like TRUMPF leverage their broad laser portfolio to support high-efficiency cell production, benefiting from brand trust and extensive application engineering support.
In the source material segment, companies like Coherent Corp. and IPG Photonics Corporation provide the foundational laser sources that enable precision drilling and structuring. Their competitive position depends on wavelength performance, reliability, and total cost of ownership. Meanwhile, specialized players like Laserax and Novanta Photonics focus on specific niches such as laser cleaning, material removal, and beam delivery systems, carving out defensible positions through deep application expertise.
Regional specialists also play a crucial role. Han's Laser Technology Industry Group Co., Ltd. addresses the specific needs of double-glass modules with high-precision glass drilling machines, capitalizing on the rising demand for photovoltaic back glass processing. ScanLAB GmbH contributes enabling scan systems that facilitate back-side contacts in advanced designs like Metal Wrap-Through and Emitter Wrap-Through. Other entities such as Rache Corp and Laserod Technologies round out the ecosystem by offering solutions for cutting, welding, scribing, and ablation processes that complement primary drilling applications.
Recent developments highlight the dynamism of this competitive field. For instance, advancements announced in late 2025 by BY Photonics demonstrated multi-dimensional breakthroughs in laser glass drilling, achieving significant reductions in drilling time with enhanced chipping control. These technical milestones set new benchmarks that competitors must match. Conversely, market disclosures from early 2026 by companies like LPKF Laser & Electronics SE reveal the impact of macroeconomic headwinds, including investment caution attributed to tariff policy uncertainties. Such reports underscore the importance of agility and long-term technology roadmapping, as some players pivot toward emerging opportunities like perovskite solar technology to leverage existing laser expertise.
Market Dynamics: Headwinds, Tailwinds, and Technological Transitions
The operational environment for solar laser drilling is shaped by a complex interplay of regulatory, technological, and demand-side factors. A primary tailwind is the increasing adoption of double-glass photovoltaic modules. This structural shift drives sustained demand for drilled back glass, necessitating high-precision, low-cost laser drilling capabilities. As module designs evolve to enhance durability and bifacial performance, the processing requirements for glass become more stringent, favoring vendors who can deliver speed without compromising integrity.
On the technology front, processes like laser contact opening and thermal laser separation are now established standards for high-efficiency PERC cells and cell cutting into half or shingle formats. These processes maximize throughput and yield, making them indispensable for large-scale production. However, the industry is also witnessing a technological shift toward perovskite coatings. This transition creates a dual dynamic: it currently holds back some immediate investments due to uncertainty and the need for new processing protocols, yet it offers long-term opportunities for laser processing specialists who can adapt their technology to handle perovskite layers and hybrid architectures.
Macroeconomic factors also exert pressure. Global investment caution observed in the first half of 2025, partly linked to uncertainties surrounding trade policy and tariffs, led to postponed orders in certain regions. This environment demands that suppliers diversify their customer base and offer flexible financing or leasing models to mitigate customer risk. Furthermore, the push for localization in key markets may alter supply chain configurations, favoring vendors with manufacturing footprints aligned to end-market production hubs.
The Strategic Value of Our Research for 2026 Decision-Making
In a market moving at the speed of technological innovation, information latency is a competitive disadvantage. Our Worldwide Solar Laser Drilling Market report is designed to eliminate this lag. For 2026, strategic planners face a unique set of challenges: balancing CAPEX against uncertain demand cycles, selecting the right laser technology mix for evolving cell architectures, and positioning for emerging segments like perovskites without neglecting the cash flow from established PERC and TOPCon lines.
This report provides the granularity needed to address these challenges. It goes beyond top-line numbers to offer actionable insights on process requirements, regional supply chain nuances, and competitive benchmarking. We analyze the cost structures associated with different laser types, the yield implications of process choices, and the service models that determine long-term customer satisfaction. By integrating these insights, executives can make informed decisions about product portfolio development, market entry strategies, and partnership opportunities.
For equipment manufacturers, the report highlights gaps in the market where specialized solutions can command premium pricing. For component suppliers, it identifies the leading manufacturers whose capacity expansion signals future demand for laser sources and optics. For investors, it profiles the companies with the technological agility and financial resilience to thrive amidst regulatory shifts and technological transitions.
Conclusion: Positioning for Sustainable Growth
The Worldwide Solar Laser Drilling Market stands at the intersection of energy transition imperatives and high-tech manufacturing capabilities. The projected growth to nearly $1.7 billion by 2032 reflects the critical role that precision laser processing plays in unlocking higher efficiencies and lower levelized costs of energy. However, capturing this growth requires more than just capital investment; it requires strategic clarity.
Stakeholders must navigate a landscape where established processes coexist with disruptive technologies, where regional dynamics influence procurement decisions, and where competitive concentration demands differentiation. Our comprehensive analysis equips you with the intelligence to navigate these complexities. By understanding the deep drivers of demand, the capabilities of key competitors, and the operational realities of cell production, you can align your strategy with the trajectory of the market.
We invite you to explore the full depth of our findings. The complete report contains detailed segmentation data, proprietary forecasts, and extensive company profiles that provide the full picture necessary for high-stakes decision-making. In the solar industry, the margin for error is shrinking, and the value of accurate intelligence has never been higher. Secure your strategic advantage with the insights found in our Worldwide Solar Laser Drilling Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com