

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Glycopeptide Antibiotics Market to Reach $2.72B by 2032 at 4.6% CAGR

Global Glycopeptide Antibiotics Market Outlook 2026: Navigating Growth, Concentration, and Supply Complexity
The worldwide glycopeptide antibiotics market stands at a pivotal inflection point as healthcare systems balance rising antimicrobial resistance with evolving manufacturing economics and regulatory frameworks. For pharmaceutical executives, hospital procurement strategists, and investment analysts, the 2026-2032 forecast window demands a clear-eyed assessment of where durable revenue will originate and where structural friction will reshape competitive positioning. This market intelligence briefing distills the core trajectories, operational realities, and strategic implications captured in our Worldwide Glycopeptide Antibiotics Market research, providing decision-makers with a framework to allocate capital, optimize supply contracts, and anticipate policy shifts with precision.
Worldwide Glycopeptide Antibiotics Market
Beginning from a base year of 2025, the sector has demonstrated a measured but consistent expansion trajectory. Historical tracking from 2020 through 2025 reveals how the market navigated pandemic-era procurement volatility, shifts in hospital formulary preferences, and persistent demand for Gram-positive coverage. The forecast horizon extending to 2032 projects a compound annual growth rate of 4.6 percent, anchoring expectations around steady volume growth, continued reliance on established glycopeptide backbones, and gradual penetration of next-generation lipoglycopeptide options. Revenue is tracked in USD millions, and the forward curve highlights years of incremental build followed by periods of accelerated expansion as clinical adoption, reimbursement clarity, and supply chain stabilization converge. For executives planning multi-year portfolios, the essential takeaway is that growth will not be linear; it will be shaped by the interplay of regional procurement cycles, formulation innovation, and cost pressures across the active pharmaceutical ingredient supply base.
Structural Foundations Shaping the Forecast
The composition of demand across drug types underscores a market anchored by high-volume legacy molecules while newer lipoglycopeptide candidates carve out differentiated clinical niches. Vancomycin continues to serve as the therapeutic and commercial cornerstone, reflecting its entrenched role in hospital protocols and broad-spectrum Gram-positive coverage. Teicoplanin maintains a meaningful presence in specific geographies and treatment pathways, while dalbavancin, oritavancin, and telavancin represent the long-acting and specialized segments where dosing convenience, outpatient administration potential, and stewardship considerations influence adoption. The interplay among these categories is not merely a clinical story; it is a commercial one, because product mix decisions affect inventory planning, hospital purchasing patterns, and the strategic calculus of manufacturers investing in differentiated formulations or lifecycle extensions.
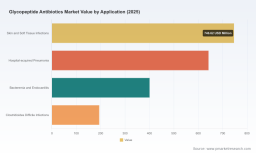
From an application perspective, skin and soft tissue infections and hospital-acquired pneumonia represent the highest-demand treatment settings, where empiric and targeted therapy for resistant organisms drives consistent utilization. Bacteremia and endocarditis add a critical dimension to the demand profile, given the severity of illness, the need for reliable serum exposure, and the consequential role of glycopeptides in saving lives when alternatives are limited. Clostridioides difficile-associated disease further reinforces the market's breadth, as oral and adjunctive glycopeptide strategies remain part of the therapeutic toolkit in specific care environments. The commercial implication is that successful market participation requires far more than volume production; it demands an understanding of ordering rhythms by indication, treatment duration variability, and the operational realities of inpatient versus outpatient delivery.
Price and cost dynamics form a third structural pillar. Between 2022 and 2025, global antibiotic API production costs increased by an estimated 25-30 percent due to higher energy inputs, chemical feedstock pressures, and wage inflation across key manufacturing locations. For glycopeptides, this cost environment has filtered through formulation economics, inventory carrying decisions, and contract negotiations. At the same time, supply concentration risks merit close attention, particularly given that China accounted for more than 60 percent of recent US antibiotic API import volume, contributing to a concentrated supply base for glycopeptide precursors and finished dosage forms. These realities elevate the strategic importance of dual sourcing, regional redundancy, and long-term framework agreements that can absorb cost fluctuations without compromising continuity of care.
Competitive Landscape and Differentiation Themes
The competitive architecture of this market is defined by a combination of branded specialty positioning, mature generic supply, and API-centric manufacturing capabilities. Market concentration data indicates a moderately consolidated environment, with the top three competitors accounting for a substantial share of revenue and the top five firms representing the majority of commercial activity. This structure rewards scale, regulatory proficiency, and distribution reach, but it also leaves room for specialized players that offer formulation advantages, stable supply commitments, or differentiated service models to capture meaningful share in targeted segments.
Pfizer's presence in the space is anchored by dalbavancin, a lipoglycopeptide positioned for acute bacterial skin and skin structure infections caused by susceptible Gram-positive organisms. Its commercial profile benefits from long-acting dosing characteristics that can reduce treatment frequency and support outpatient transition strategies, especially where reimbursement pathways and administration logistics align. Hikma Pharmaceuticals has strengthened its standing with FDA-approved vancomycin injection products, including a ready-to-infuse, room-temperature stable formulation cleared in 2025 for serious Gram-positive infections such as septicemia, endocarditis, and skin structure infections. This type of formulation innovation addresses practical hospital pain points: reduced preparation time, simplified bedside administration, and storage flexibility that can matter in high-throughput clinical environments.
ANI Pharmaceuticals reinforces the oral vancomycin segment through a branded capsule offering indicated for C. difficile-associated diarrhea and staphylococcal enterocolitis, reflecting a niche where formulation specificity and clinician familiarity support sustained demand. Fresenius, through its Kabi division, supplies generic vancomycin and other injectable glycopeptide formulations for hospital use, emphasizing dependable supply and integration into institutional purchasing systems. Xellia Pharmaceuticals maintains a specialized focus on anti-infective APIs and finished dosage forms, with vancomycin API and related formulations supporting critical care applications where supply reliability is paramount. Aurobindo Pharma and Zhejiang Hisun Pharmaceutical contribute broad generic vancomycin and glycopeptide API capabilities for global markets, underscoring the importance of internationally competitive manufacturing footprints. Mylan, now operating under Viatris, offers generic vancomycin hydrochloride injection for serious infections caused by susceptible methicillin-resistant staphylococci, reinforcing the breadth of the generic supply layer that hospitals and distributors rely on for cost management and continuity.
Taken together, these players illustrate a market where differentiation is increasingly tied to formulation practicality, regulatory milestones, supply resilience, and commercial execution rather than first-in-class novelty alone. For buyers, this landscape creates leverage through supplier diversification. For manufacturers, it demands disciplined lifecycle planning, rigorous quality systems, and clear value propositions that extend beyond molecule-level competition.
Operational Realities and Policy Signals That Matter
Beyond molecule-level competition, several operational and regulatory developments shape how the market will function across the forecast period. Updated antimicrobial susceptibility testing systems have received clearance with revised breakpoints for telavancin and daptomycin against Enterococcus faecalis, including vancomycin-resistant strains. While this primarily affects laboratory interpretation and stewardship workflows, it also influences prescribing confidence, formulary positioning, and downstream utilization patterns for related glycopeptide therapies. The broader lesson for commercial teams is that diagnostic and susceptibility updates can shift treatment selection at the margin, making it essential to monitor laboratory guidance as part of market sensing.
Reimbursement architecture also plays an outsized role in adoption decisions. For example, specific long-acting glycopeptide therapies are reimbursed under designated injection codes in hospital outpatient and related settings for acute bacterial skin and skin structure infections. Such coding clarity can accelerate uptake where administration efficiency, patient throughput, and cost-per-episode economics favor outpatient transition. The practical implication is that market access strategy cannot be separated from supply strategy; formulation characteristics, administration setting, and payer coding must be evaluated in concert.
Regulatory continuity remains reassuring for core glycopeptide indications. Vancomycin continues to be indicated for serious infections due to susceptible Gram-positive bacteria, including MRSA, and there is no widespread market discontinuation or recall of core glycopeptide products. This stability supports baseline demand visibility, but it does not eliminate the need to manage supply risk, quality compliance, and procurement timing, especially as hospital budgets remain under pressure and purchasing groups consolidate volumes to extract efficiency.
On the cost and supply side, the combination of API cost inflation and concentrated sourcing patterns argues for a more deliberate approach to procurement architecture. Facilities that depend heavily on single-source inputs or geographically concentrated supply chains face heightened exposure to disruption, price volatility, and lead-time uncertainty. Leading organizations are increasingly pairing demand forecasting with supplier qualification, inventory buffering where clinically appropriate, and contractual structures that provide transparency around cost drivers. In this market, resilience is becoming a competitive advantage as much as a risk control measure.
How This Research Converts Into Decision-Ready Intelligence
Our Worldwide Glycopeptide Antibiotics Market study is designed to move beyond high-level trend summaries and equip teams with actionable detail across market sizing, segmentation, competitive profiling, and dynamic drivers. The analysis covers historical performance from 2020 through the 2025 base year and extends across the full 2026-2032 forecast period, giving stakeholders a continuous view of how market momentum is expected to evolve. Revenue is presented in USD millions, with growth rates and trajectory indicators structured to support scenario planning, budgeting, and internal benchmarking.
The segmentation framework provides separate lenses on region, drug type, and application, allowing readers to isolate where growth is being generated, which product categories are expanding or stabilizing, and how indication-level demand differs by care setting and clinical pathway. Rather than treating the market as a single aggregate, the study breaks down demand behavior so that commercial leaders can align product strategy, inventory planning, and sales coverage with the realities of each segment. Competitive profiling goes beyond corporate descriptions to map positioning, formulation differentiation, supply roles, and recent moves that affect market share dynamics. This includes attention to regulatory approvals, formulation advancements, and product availability milestones that can shift buyer preferences in specific hospital and outpatient environments.
The study also integrates industry dynamics that influence execution risk and commercial potential. That includes regulatory updates affecting susceptibility testing and breakpoint interpretation, API cost trends and their implications for formulation economics, supply chain concentration patterns and their impact on continuity planning, and reimbursement structures that affect adoption in outpatient and hospital-based settings. By connecting these forces to market outcomes, the research supports more credible forecasting, more informed sourcing decisions, and more resilient commercial plans.
Strategic Priorities for 2026 and Beyond
For executives entering 2026, the most valuable use of this intelligence is to translate market structure into prioritized action. First, clarify where your portfolio aligns with durable demand. Skin and soft tissue infections, hospital-acquired pneumonia, bacteremia and endocarditis, and C. difficile-related care all contribute meaningfully to utilization, but each carries distinct procurement rhythms, treatment duration profiles, and service-delivery requirements. Segmentation insight helps avoid overgeneralizing demand and enables targeted investment in the categories and channels where adoption is most likely to hold or accelerate.
Second, treat supply resilience as a strategic asset. With API cost inflation and concentrated sourcing patterns reshaping cost-to-serve, organizations should evaluate sourcing redundancy, contractual transparency, and inventory logic in relation to clinical criticality. For manufacturers and distributors, differentiated value may come from formulation convenience, storage flexibility, or reliable supply performance that reduces operational friction for hospitals. For buyers, it may come from structured supplier diversification and clear visibility into cost drivers.
Third, monitor the policy and reimbursement environment as a growth enabler or constraint. Susceptibility breakpoint changes, coding frameworks for injectable therapies, and institutional formulary review cycles can influence adoption trajectories at the margin. Early awareness of these shifts allows commercial and market access teams to prepare communication, evidence, and contracting strategies before demand signals fully materialize.
Finally, use competitive intelligence to sharpen positioning. In a market where the top five players hold a substantial share and the top three command an even larger portion, smaller or more specialized participants can still win by focusing on formulation advantages, supply reliability, and service responsiveness. The research provides the context needed to identify where differentiation is credible and where head-on volume competition should be approached with caution.
Closing Perspective
The glycopeptide antibiotics market is not defined by dramatic disruption, but by the cumulative effect of clinical reliance, formulation innovation, cost pressure, and supply concentration. That combination makes disciplined analysis especially valuable for 2026 decision-making. Growth is projected at a steady pace, demand is anchored in serious Gram-positive infections, and competitive advantage increasingly depends on execution quality as much as product portfolio. For organizations seeking to allocate resources with confidence, understand where share is being created, and anticipate the operational factors that will shape performance across 2026-2032, the full Worldwide Glycopeptide Antibiotics Market research provides the depth required to move from awareness to action.
Antimicrobial Peptides Market
For detailed analysis of this topic, please visit the official page: Worldwide Glycopeptide Antibiotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com