

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Medicine Packaging Adhesive Market to Hit $2.58B by 2032, Growing at 6.68% CAGR

Navigating the Future of Medicine Packaging Adhesives: Strategic Insights from the 2026 Global Market Intelligence
By the PW Consulting Strategic Advisory Team
The global pharmaceutical industry stands at a critical intersection of innovation, regulatory complexity, and sustainability imperatives. As drug delivery systems evolve and consumer expectations around safety shift, the adhesives that hold medical packaging together are no longer mere afterthoughts. They are enablers of compliance, guardians of product integrity, and increasingly, focal points for environmental stewardship. In this context, our newly released Worldwide Medicine Packaging Adhesive Market report arrives at a decisive moment for strategic planning. Anchored in historical performance from 2020 through 2025 and projecting forward across the 2026-2032 forecast horizon, this intelligence is engineered to convert market ambiguity into executable strategy.
For executives navigating capital allocation, supply chain partnerships, or product development roadmaps in 2026, the adhesive layer represents a high-leverage decision point. Understanding where value is accumulating, which material technologies are gaining favor, and how regulatory waves are reshaping compliance pathways is no longer optional. This market analysis does not simply chart revenue trajectories. It dissects the operational realities, competitive maneuvers, and substitution dynamics that will separate resilient organizations from those caught flat-footed as the decade unfolds.
A Market Expanding Beyond Steady Growth
The overall market has demonstrated consistent expansion over the historical window, reflecting the compounding influence of chronic disease prevalence, heightened cold-chain and sterile packaging requirements, and broader distribution footprints across emerging and developed economies. From a baseline exceeding $1.18 billion in 2020, the sector has progressed through successive annual increments, reaching approximately $1.64 billion by 2025. Moving into the forecast period, the trajectory continues its upward course, with the market projected to surpass the $1.77 billion mark in 2026 and climb toward roughly $2.58 billion by 2032. The compound annual growth rate across this entire forecast horizon rests at 6.68 percent, signaling durable demand rather than a temporary surge.
This momentum, however, does not distribute evenly across all technology families, application formats, or geographic corridors. The aggregate figures mask meaningful divergence in regional maturity, material substitution cycles, and application-specific performance thresholds. Decision-makers must look beyond the headline trajectory to understand where procurement flexibility, regulatory headwinds, and performance trade-offs are actively reshaping purchasing behavior. Our full study decodes these divergences with granular segmentation detail, enabling teams to benchmark their exposure against the pockets of highest volumetric growth and the segments facing the steepest margin pressure.
Core Components and Actionable Intelligence Within the Report
This publication is structured for immediate enterprise application rather than passive review. Each section has been designed to feed directly into sourcing strategy, product architecture, and risk mitigation workflows. Below is a structured overview of the operational content that decision-makers can deploy once they access the full dataset.
- Technology Landscape Evaluation: A detailed comparison of water-based, hot melt, solvent-based, UV-cured, and other adhesive variants, examining cure speeds, substrate compatibility, regulatory alignment, and total cost of ownership across high-speed packaging environments.
- Application-Specific Demand Mapping: In-depth coverage of blister packaging, flexible packaging, labels and tapes, and bottles and containers, including format shift trends, tamper-evident requirements, and performance sensitivities tied to pharmaceutical product classes.
- Regional Opportunity and Compliance Frameworks: A geographically segmented view that pairs demand concentration with local regulatory trajectories, enabling multi-market procurement strategies that balance cost efficiency against jurisdictional requirements.
- Competitive Positioning and Share Dynamics: Analysis of concentration patterns and strategic posturing among leading suppliers, including product roadmap signals, capacity investments, and partnership or acquisition behaviors that indicate where the market is heading.
- Raw Material Sensitivity and Margin Risk: An exploration of input price volatility, particularly around petrochemical-derived acrylics, synthetic rubbers, and tackifying resins, alongside mitigations such as formulation diversification, contract structuring, and dual-sourcing architectures.
- Regulatory and Sustainability Scenario Planning: Practical guidance on navigating FDA food-contact provisions, EMA-aligned European requirements, and the evolving patchwork of Extended Producer Responsibility laws, including considerations for exemptions, fee modulation, and recycled-content expectations.
- Strategic Recommendations and Growth Playbooks: Actionable pathways for adhesive manufacturers seeking to expand their pharmaceutical footprint, as well as for pharmaceutical packaging buyers evaluating supplier consolidation, qualification timelines, and future-proofing against regulatory change.
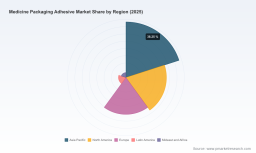
Each of these modules is supported by proprietary data cuts and forward-looking scenario analysis. The complete segmentation breakdowns, regional revenue detail, application share distributions, and concentration metrics are reserved for the full report, ensuring that only clients with access to the complete intelligence can operationalize the numbers at the level required for board-level planning.
The Competitive Arena: Leaders Shaping the Adhesive Ecosystem
Market concentration offers a clear signal of where influence is currently consolidated. The sector exhibits a moderate-but-firm leading position among top suppliers, with the three largest players holding roughly 38.45 percent combined share and the top five reaching approximately 52.1 percent. This concentration does not indicate a closed door for disruptors; rather, it highlights the premium placed on validated pharmaceutical-grade performance, regulatory documentation, and high-speed line compatibility. The leaders profiled in this research demonstrate how targeted formulation engineering and application-specific credentialing can sustain both volume growth and pricing resilience.
Worldwide Medicine Packaging Adhesive Market
Henkel AG & Co. KGaA has reinforced its position through hot melt systems engineered for high-speed pharmaceutical packaging lines, including carton-closing solutions and tamper-evident bonding formulations designed for difficult substrates. Recent activity underscores a continued push into faster curing and regulatory-aligned technologies, including LED-curable lines intended to improve throughput and compliance in device and packaging assembly. H.B. Fuller Company contributes medical-grade adhesive portfolios tailored to pharmaceutical surfaces and flexible medicine packaging, with biocompatible options that address bonding requirements across overwraps and specialty formats. 3M Company continues to supply packaging adhesives and hot melt solutions that support structural bonding and labeling needs across pharmaceutical applications. Arkema S.A., through its Bostik division, develops laminating adhesives and hot melt platforms optimized for medical and pharmaceutical packaging, with particular emphasis on flexible structures and high-barrier configurations. Avery Dennison Corporation extends its pressure-sensitive materials expertise into pharmaceutical labeling and secure packaging identification, supporting closure integrity and traceability requirements.
Dow Inc. rounds out the broader technology base with laminating adhesives and heat-sealable coatings designed for medicine blister and flexible packaging architectures. Alongside these global players, more specialized or regionally focused contributors such as artimelt AG, Jowat SE, Capital Adhesives, and BC Adhesives illustrate how product focus, line-speed compatibility, and tamper-evident or medical-grade credentials can create defensible niches even within a moderately concentrated market. artimelt AG, for example, has built meaningful relevance around hot melt solutions for tablet blister packs, security pouches, and tamper-proof labels. Jowat SE has emphasized formulations applicable to carton closing and pharmaceutical packaging line environments, while Capital Adhesives and BC Adhesives underscore the importance of supply continuity and medical-grade tamper-evident solutions for carton and overall packaging assemblies.
Recent corporate activity further illustrates the direction of travel. In late 2025, Henkel introduced LED-curable adhesives for medical applications with an emphasis on fast curing and regulatory compliance, reinforcing a shift toward process efficiency and precision bonding. That same year, Henkel Adhesive Technologies highlighted the TECHNOMELT SUPRA PRO 301 PLUS hot melt adhesive for pharmaceutical packaging, connecting tamper-evident bonding with sustainability objectives on high-speed lines. At the start of 2026, Dymax Corporation exhibited light-curable, CMR- and TPO-free adhesives for medical device assembly at MD&M West, drawing attention to low-risk formulation strategies in precision bonding for pharmaceutical packaging components. These moves collectively point toward a sector where regulatory confidence, curing efficiency, and formulation clarity are becoming competitive differentiators rather than table-stakes features.
Market Dynamics: Regulations, Materials, and Substitution Pressures
No strategic plan for this market can ignore the regulatory environment. Across multiple U.S. states, Extended Producer Responsibility frameworks for packaging have been implemented or passed, requiring producers to fund recycling programs, establish recycled-content minimums, and adopt fee structures that reward recyclability and post-consumer content. At the same time, several of these programs exempt certain pharmaceutical and medical packaging or products due to patient safety considerations, federal oversight, and regulatory duplication concerns. The practical implication for adhesive decision-makers is a bifurcated landscape: in some corridors, packaging producers face escalating recycling and content obligations; in others, medical and pharmaceutical exemptions create more stable compliance paths, but still demand rigorous documentation and safety alignment. Understanding where exemption boundaries sit and how fee modulation could evolve is essential for multi-state packaging strategies.
On the materials side, pressure-sensitive adhesives commonly depend on acrylic polymers supplied as aqueous emulsions, alongside synthetic rubber and tackifying resins such as hydrogenated hydrocarbon resins derived from petrochemical sources. This composition links performance, cost, and compliance directly to upstream volatility. Raw material pricing for these components remains sensitive to oil market fluctuations and monomer supply dynamics, meaning procurement teams cannot rely on static cost assumptions when modeling margins or negotiating long-term supply agreements. The full report incorporates scenario-based sensitivity views that connect input volatility to formulation choices, supplier diversification, and contract structures, enabling risk teams to stress-test sourcing plans rather than react after prices move.
Regulatory coherence across jurisdictions also remains a central concern. Pharmaceutical packaging adhesives and associated materials must align with FDA food-contact adhesive provisions under 21 CFR 175.105 and EMA-oriented European food-contact expectations under Regulation (EC) No 1935/2004 to support safety in medicine packaging applications. Even as exemptions exist in certain packaging EPR regimes, adhesive suppliers and packaging converters still need robust compliance documentation and formulation controls to satisfy customer audits, labeling integrity requirements, and health-safety expectations. This dual pressure of raw material volatility and regulatory documentation creates a market where formulation transparency and supplier credibility increasingly determine vendor selection.
Worldwide Powder Adhesive Market
Strategic Priorities for 2026 Decision-Making
As organizations prepare for the 2026 operating environment, several strategic imperatives emerge from the interplay of growth, concentration, regulation, and material risk.
- Align adhesive selection with line-speed realities and format performance: Prioritize formulations that can withstand high-speed pharmaceutical packaging operations without sacrificing tamper-evident integrity or substrate compatibility.
- Audit regulatory exposure across packaging corridors: Map where pharmaceutical or medical packaging exemptions apply, where recycled-content and EPR obligations intensify, and how fee structures could influence total packaging cost in different regions.
- Quantify raw material exposure early: Treat petrochemical-driven price variability as a planning variable, not an exception, by testing dual-sourcing options, formulation alternatives, and contract mechanisms before disruption arrives.
- Evaluate supplier concentration strategically: Recognize that market leadership is concentrated, but not prohibitive. Use detailed share and capability data to decide when to consolidate for validation efficiency and when to diversify to preserve continuity and negotiation leverage.
- Plan for curing and sustainability differentiation: Track product launches that emphasize fast curing, regulatory-aligned formulations, and lower-risk ingredient profiles, as these are becoming signals of where the market is heading beyond incremental performance gains.
The value of this market intelligence lies in its ability to connect these imperatives to specific, decision-ready data rather than broad narrative. Full regional breakdowns, application share distributions, technology revenue detail, and concentration metrics are intentionally reserved for the complete report so that only engaged stakeholders gain access to the numbers needed for board-level planning, sourcing review, and product roadmap decisions.
Accessing the Complete Intelligence
The Worldwide Medicine Packaging Adhesive Market study is designed to function as a decision-support asset rather than a static overview. It provides the segmentation depth, competitive profiling, regulatory context, and scenario framing necessary to transform market growth into a structured advantage. The summary presented here offers a credible window into the scope and rigor of the analysis while preserving the core segment data that makes the full publication actionable.
For executives seeking regional revenue clarity, application-specific demand splits, technology-level revenue comparisons, and detailed supplier positioning, the complete report delivers the missing pieces. These elements are built to support sourcing strategy, market entry evaluation, competitive benchmarking, and regulatory-aligned packaging planning. The full dataset can be accessed through the project page, where the complete segmentation, forecast tables, and company profiles are available for immediate operational use.
In a market increasingly shaped by compliance calibration, material volatility, and formulation differentiation, timely access to precise segment intelligence can determine whether a team responds reactively or plans proactively. The detailed figures and strategic readouts within the full analysis are intended to give decision-makers exactly that advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Medicine Packaging Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com